A credit card settlement is an agreement to pay a card company or debt collector less than the full balance in exchange for treating the account as resolved. It can end a debt you cannot realistically repay, but it usually comes with damaged credit, possible fees, a real risk of lawsuits along the way, and a tax bill you may not expect.
This guide is about the downside as much as the upside. Plenty of pages describe settlement as a clever discount; fewer explain what happens to your credit report, why the IRS can treat the forgiven part as income, and how the fee rules for settlement companies actually work. If you are weighing settlement against other routes, the goal here is to help you see the full price tag first.
Two sibling guides cover neighboring questions: what counts as real forgiveness versus a scam, and how to do the negotiating yourself. Here we stay on the three things the title promises: the risks, the taxes, and the credit damage.
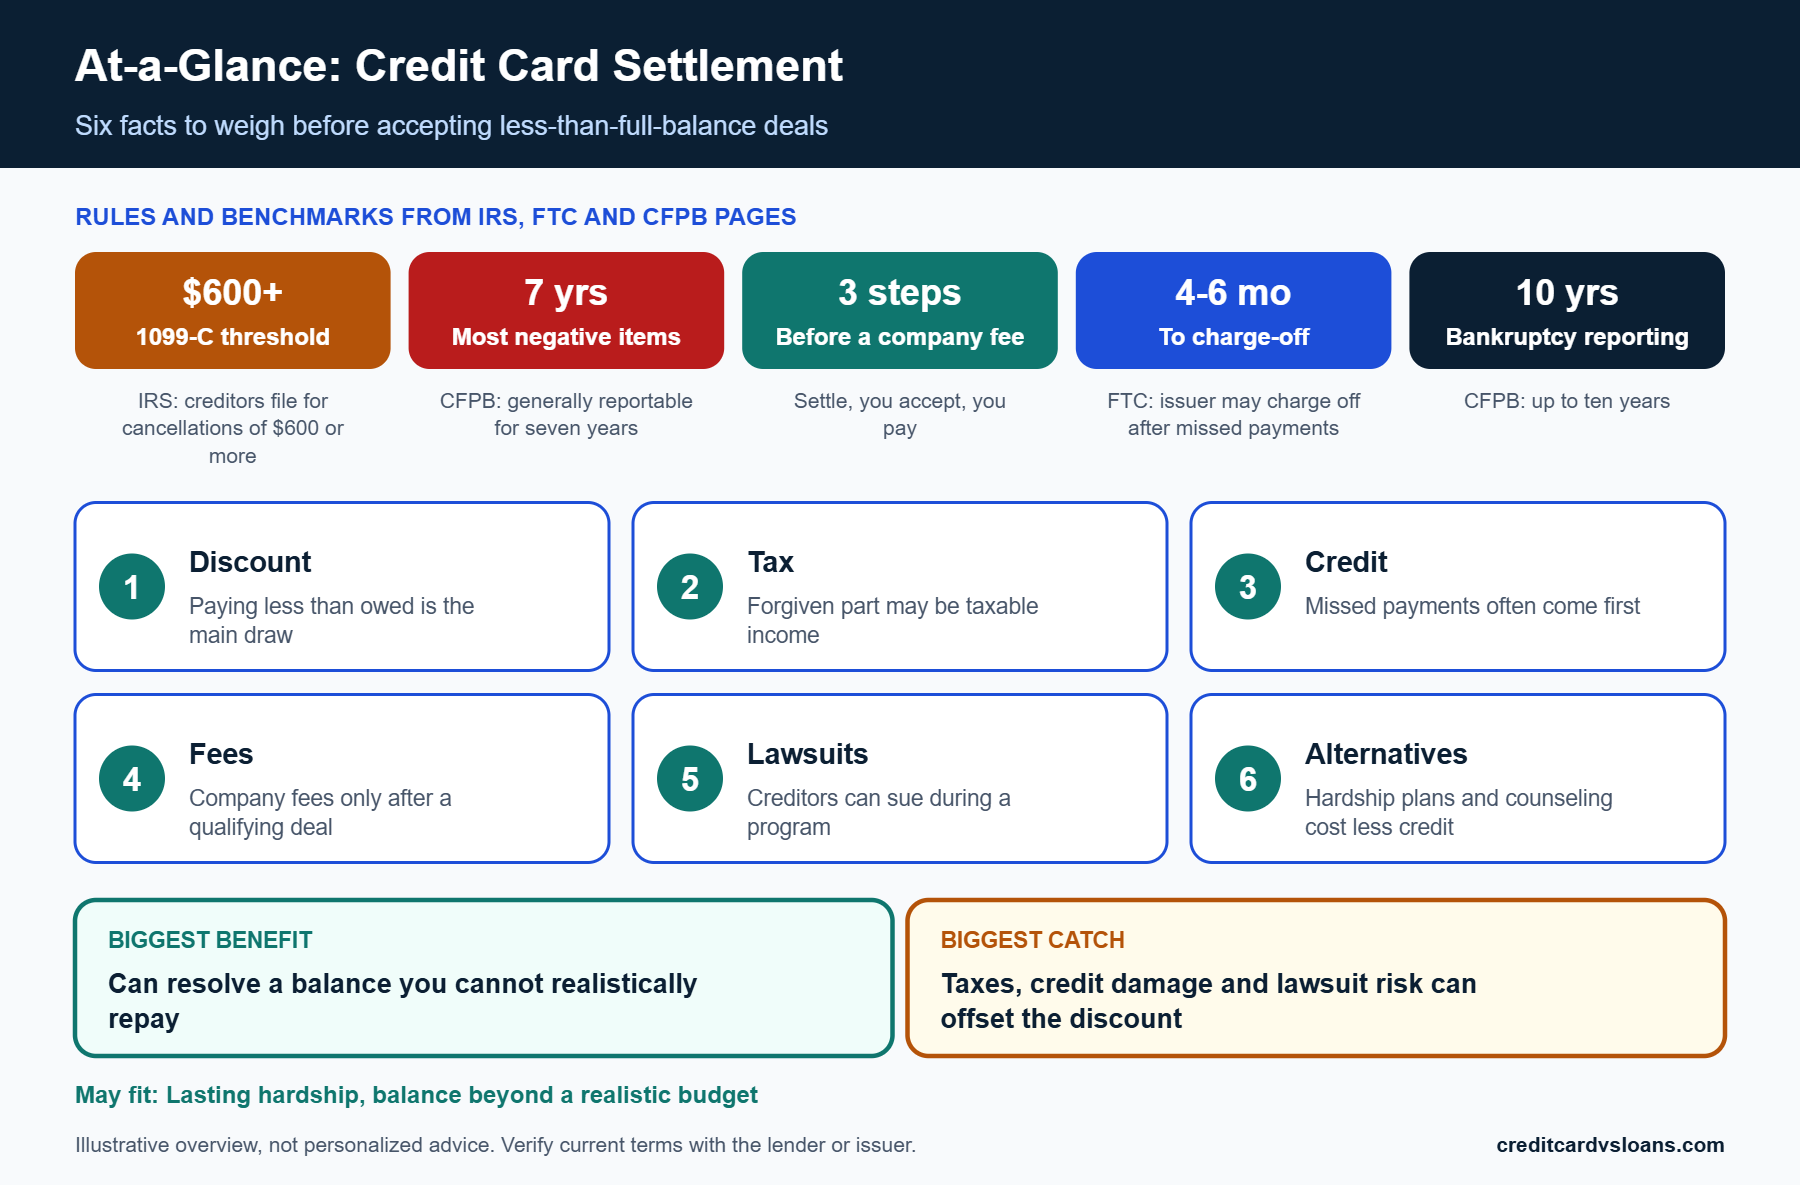
- Settlement means paying less than you owe, but the unpaid part can be taxable income, and a creditor may report it to the IRS on Form 1099-C.
- Credit damage is likely, both from the missed payments that often come before a deal and from the settled account itself. Most negative items can be reported for seven years.
- Companies that sell settlement programs generally cannot collect fees before they settle at least one of your debts, you agree to the deal, and you make a payment under it.
- If your debts exceed the value of your assets when a debt is canceled, the insolvency exclusion may reduce or remove the tax bill. Form 982 is how you claim it.
- Settlement is a late-stage tool. Cheaper options, such as a hardship plan or a nonprofit debt management plan, are worth ruling out first.
Tax and consumer-protection details here reflect IRS, FTC and CFPB pages as they read in October 2026. Individual card agreements, state laws and your own tax situation can differ, so treat the figures below as illustrations rather than quotes.
Credit card settlement in plain terms: what it is and who it fits
What a settlement actually is
A lump sum or short payment plan for less than the balance
In a settlement, a creditor or collector agrees to accept less than the full amount you owe. The payment may arrive as one lump sum or as a short series of payments, and the agreement should say that paying it resolves the account. The Consumer Financial Protection Bureau describes the basic steps as confirming you owe the debt, working out what you can realistically pay, and then making a proposal.
The amount forgiven is not a gift. Because the creditor gives up money it was owed, the tax rules treat the difference as canceled debt, which we cover in detail below. That is the first catch hiding inside a deal that looks like pure savings.
Why a creditor would agree to take less
A lender takes a settlement when it expects to collect less by waiting. If an account has been unpaid for months, the issuer may write it off internally, which the FTC says can happen after roughly four to six months of missed payments, and the debt may be sold to a collector. Even then, the FTC notes the debt is still owed and creditors may still negotiate after a charge-off.
That logic explains why settlement offers tend to come after hardship, not before it. A creditor has little reason to discount a balance you are paying on schedule. It also explains why a settlement is rarely available to someone who is merely tired of interest.
Who it may fit, and who should look elsewhere
Borrowers who may be candidates
Settlement may be worth investigating if you have a lasting loss of income, a balance far beyond what any realistic budget can repay, and no clear path to catch up through lower interest or a longer payment plan. Some people in that position have a lump sum available from savings or a family member, which is often what makes a creditor willing to talk.
It can also make sense when the alternative is a judgment or bankruptcy. Bankruptcy is a legitimate tool, and the FTC describes it as generally a last resort, so a candid comparison with a bankruptcy attorney or a nonprofit counselor is reasonable before you commit to settlement.
Borrowers who usually have cheaper options
If you are current on payments and mainly want a lower rate, settlement is the wrong tool; it would trade a manageable problem for credit damage. Ask your issuer for a lower interest rate or a hardship payment plan first, as the FTC suggests, and look at credit card debt consolidation options by credit profile if your credit is still in decent shape.
If you can afford the monthly payments but the balance feels heavy, a nonprofit debt management plan or a balance transfer may cost far less in credit damage. Our comparison of a debt consolidation loan versus a balance transfer card walks through that choice.
| Feature | What to know | Main drawback |
|---|---|---|
| What you get | A written agreement to resolve the account for less than the balance | The forgiven part may be taxable |
| Typical timing | Usually after missed payments or a charge-off | Credit damage often starts before the deal |
| Who negotiates | You, an attorney, or a for-profit settlement company | Companies cannot promise results and often cannot settle every debt |
| Fees | None if you negotiate yourself; company fees only after a qualifying settlement | Fees can still be a large share of the savings |
| Credit report | Negative items can generally be reported for seven years | Hurts future credit applications |
| Best fit | Lasting hardship with a balance beyond realistic repayment | Poor fit if you can still pay on schedule |
Notice how few rows in that table are purely good news. That is typical of settlement: the benefit is concentrated in one number, the discount, while the costs are spread across fees, taxes, credit and time.
How credit card settlement works, step by step
Settling directly with the issuer or a collector
The delinquency timeline that usually comes first
Most settlements follow a predictable arc. A payment is missed, late fees and interest keep building, the issuer calls, and eventually the account is charged off or placed with a collector. According to the FTC, missing minimum payments can hurt your score, and the issuer may charge off the debt after four to six months.
None of that makes the debt disappear. The balance still exists, interest and fees may still be added where the contract and state law allow, and collectors may contact you. Knowing where an account sits on this timeline tells you who you will be negotiating with and how much leverage each side has.
Making an offer and getting it in writing
The CFPB advises asking the collector for information about the debt, working out a total you can pay in one payment or several, and then making a proposal. It also stresses getting the plan and the collector’s promises in writing before you make a payment, including any promise to stop collection or treat the remainder as forgiven.
That written confirmation matters more than the discount. Without it, a payment can be applied as an ordinary partial payment, leaving a remaining balance that someone can still pursue. A separate guide on negotiating directly covers the mechanics in more depth.
Settling through a settlement company
The usual program design
The FTC describes debt settlement programs as for-profit services that negotiate with creditors to accept a lump sum smaller than the full debt. You typically deposit money into a dedicated account until there is enough to fund a settlement, and programs often encourage you to stop paying creditors directly in the meantime.
That last feature is the heart of the risk. While you save, accounts can go delinquent, late fees and interest can pile up, and creditors can sue. The FTC lists it plainly: you may not finish the program, you may owe fees for the debts that were settled and still owe the rest, and credit damage is likely.
What the dedicated account must look like
Under the FTC’s debt relief rule, a provider may require a dedicated account only if it sits at an insured financial institution, you own the funds and the interest they earn, and you can withdraw without penalty. The account administrator cannot be owned or controlled by the settlement company, and no referral fees can pass between them.
The FTC’s guidance also says that if you leave the program, the remaining balance, minus any fees the provider has legitimately earned, must be returned within seven business days. If a company asks you to send money to an account it controls, treat that as a red flag and walk away.
What credit card settlement really costs: payments, fees and interest
The fee rules that apply to settlement companies
When a company is allowed to charge you
The FTC’s rule on debt relief services says a for-profit provider may not collect a fee until three things have happened. At least one of your debts has been settled or reduced, you have accepted the resulting agreement, and you have made at least one payment to the creditor under it. The creditor’s terms must be in writing, and a blanket advance approval of future settlements does not count.
The FTC applies this rule to for-profit sellers who market debt relief by phone, which in practice covers much of the industry, and state laws can add further limits. Either way, the CFPB’s advice is simple: avoid companies that charge money in advance.
How fees are calculated across several debts
When you enroll more than one debt, the provider cannot front-load its fee. The FTC’s guidance gives two permitted methods. Under the proportional method, the fee tracks the share of your enrolled balance that was resolved: with a $600 total fee and three $1,000 debts, the provider could collect $200 once one debt is settled.
Under the percentage-of-savings method, the same percentage applies to every debt, so a 25 percent fee on $400 saved produces a $100 fee. Both methods are measured against the balance at enrollment, which is why a company’s quoted percentage deserves a close look before you sign.
The full cost stack, including what the discount hides
Payment, fees, interest and tax together
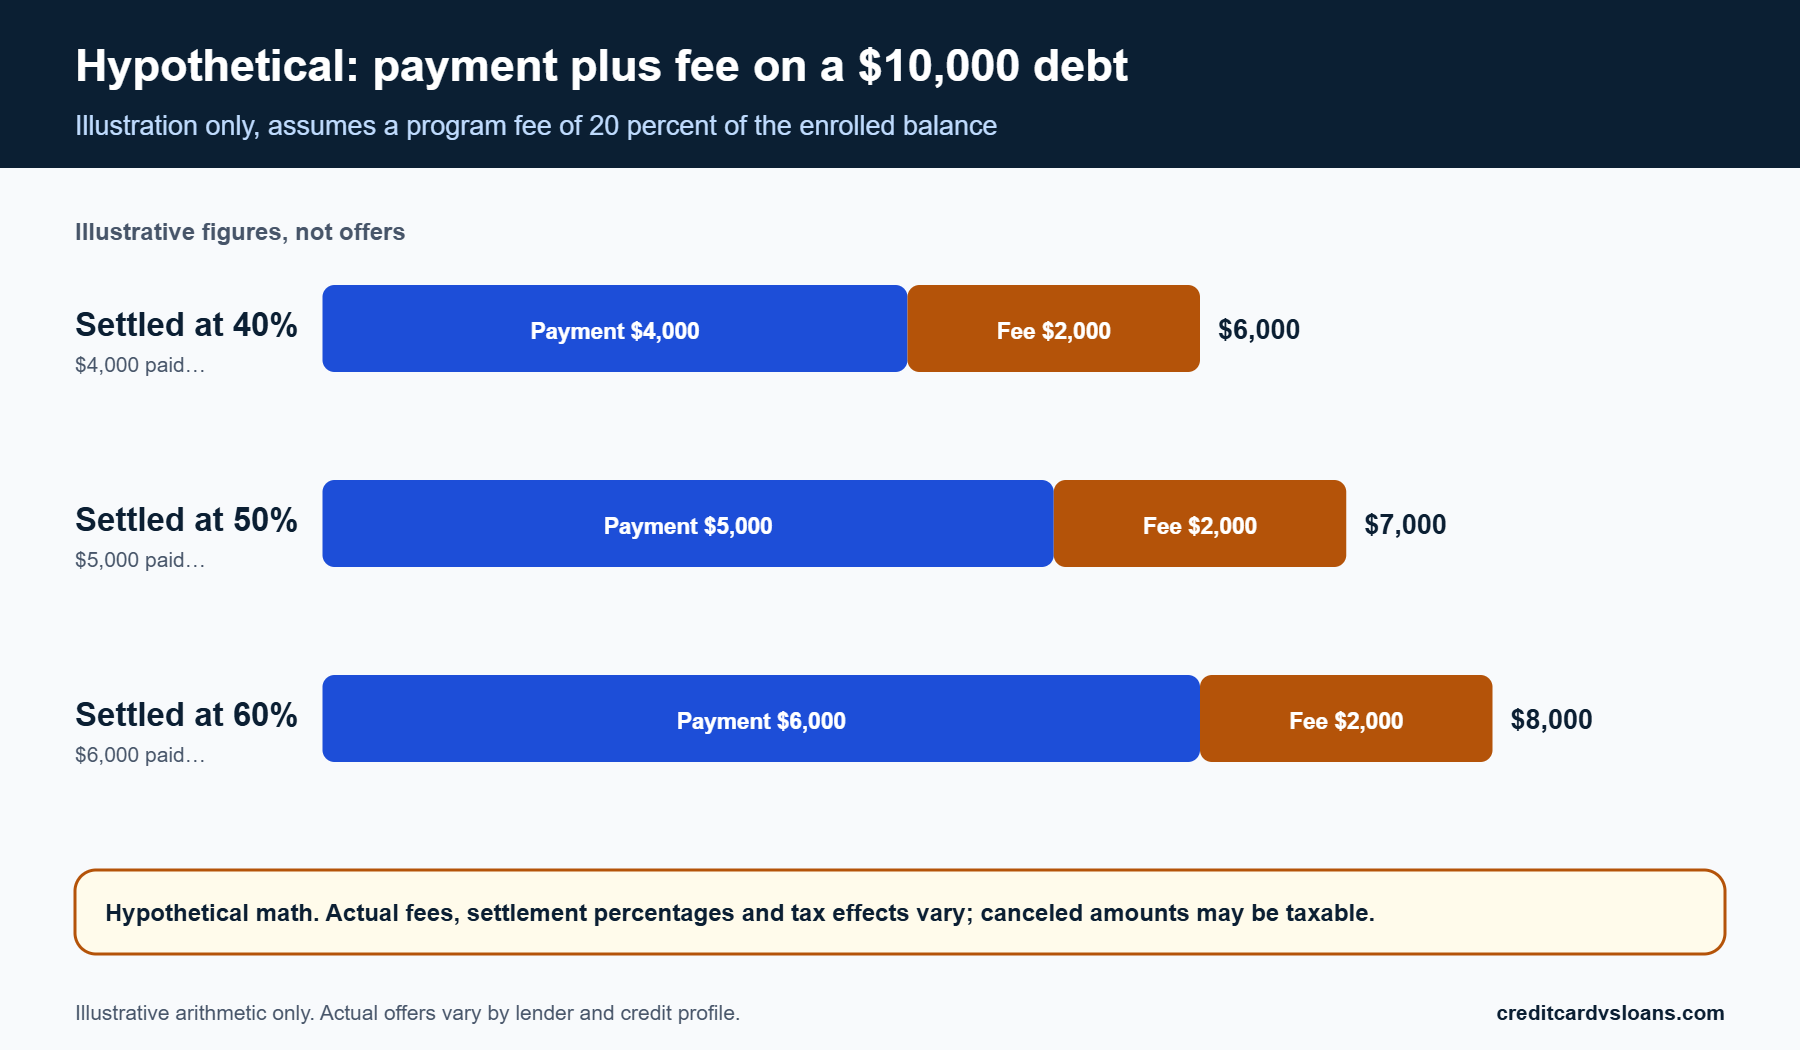
A fair comparison adds up everything you will pay or owe: the settlement payment, any program fee, interest and late fees that accumulated while accounts were unpaid, and the income tax on the canceled portion if no exclusion applies. Looking only at the discount percentage leaves out most of those items.
The hypothetical numbers in the chart below show how fees change the outcome. They are illustrations, not quotes, and your actual fees, settlement percentages and tax situation will differ.
Why waiting can raise the balance you negotiate against
Settlement programs often involve months of saving before a creditor is approached. During that time, the FTC warns that late fees and interest can grow on the unpaid accounts, so the balance you are settling may be larger than the balance you enrolled. The FTC’s own guidance requires savings claims to be measured against the enrolled amount for exactly this reason.
That is why it helps to ask a company, in writing, how it measures savings and what happens if an account is sold to a collector or sued on mid-program. Honest answers should be specific and should match the disclosures the rule requires, including how long results are expected to take.
| Route | Typical fee pattern | Repayment pattern | Credit effect | Main risk |
|---|---|---|---|---|
| Negotiate yourself | No program fee | Lump sum or short plan after an agreement | Late payments and settled status on the report | Verbal promises that are never written down |
| Settlement company | Charged only after a qualifying settlement | Monthly deposits into a dedicated account | Often follows stopped payments | Lawsuits and growing balances during the program |
| Nonprofit debt management plan | Ask for a written fee quote | One monthly payment, often 48 months or more | Varies by creditor; plan terms matter | Creditors may not accept the plan; confirm first |
| Consolidation loan or balance transfer | Origination or transfer fees may apply | Fixed or promotional payoff schedule | Hard pull, then utilization changes | Needs approval you may not get |
| Bankruptcy | Court filing fee plus attorney fees | Liquidation or three-to-five-year plan | Reportable up to ten years | Not all debts are discharged |
Table 2 shows why settlement is rarely the cheapest route in credit terms. Its main selling point is the size of the discount, not the damage avoided.
Credit damage from settling: before, during and after
The damage that happens before the deal
Missed payments do most of the harm
Payment history is the biggest single input into most scoring models, so months of missed payments often hurt your credit more than the final settlement entry does. Many settlement paths require falling behind first, either because the creditor will not negotiate on a current account or because a company tells you to stop paying while you save.
No one can promise a specific score change, and the size of the drop depends on where your score started and what else is on your reports. What can be said is that the damage is front-loaded, and every additional month delinquent adds another negative mark.
Utilization, closed accounts and new applications
A card that is closed after a settlement stops contributing available credit, which can raise your overall utilization if you carry balances elsewhere. A closed account can also reduce the average age of your open accounts over time, although older closed accounts typically continue to show on your report.
If you apply for new credit afterward, lenders see recent delinquencies and may decline or price the loan higher. Our guide on whether applying for a credit card hurts your credit score explains why every application should be deliberate while your file is still recovering.
The damage that lingers afterward
How long negative information can stay
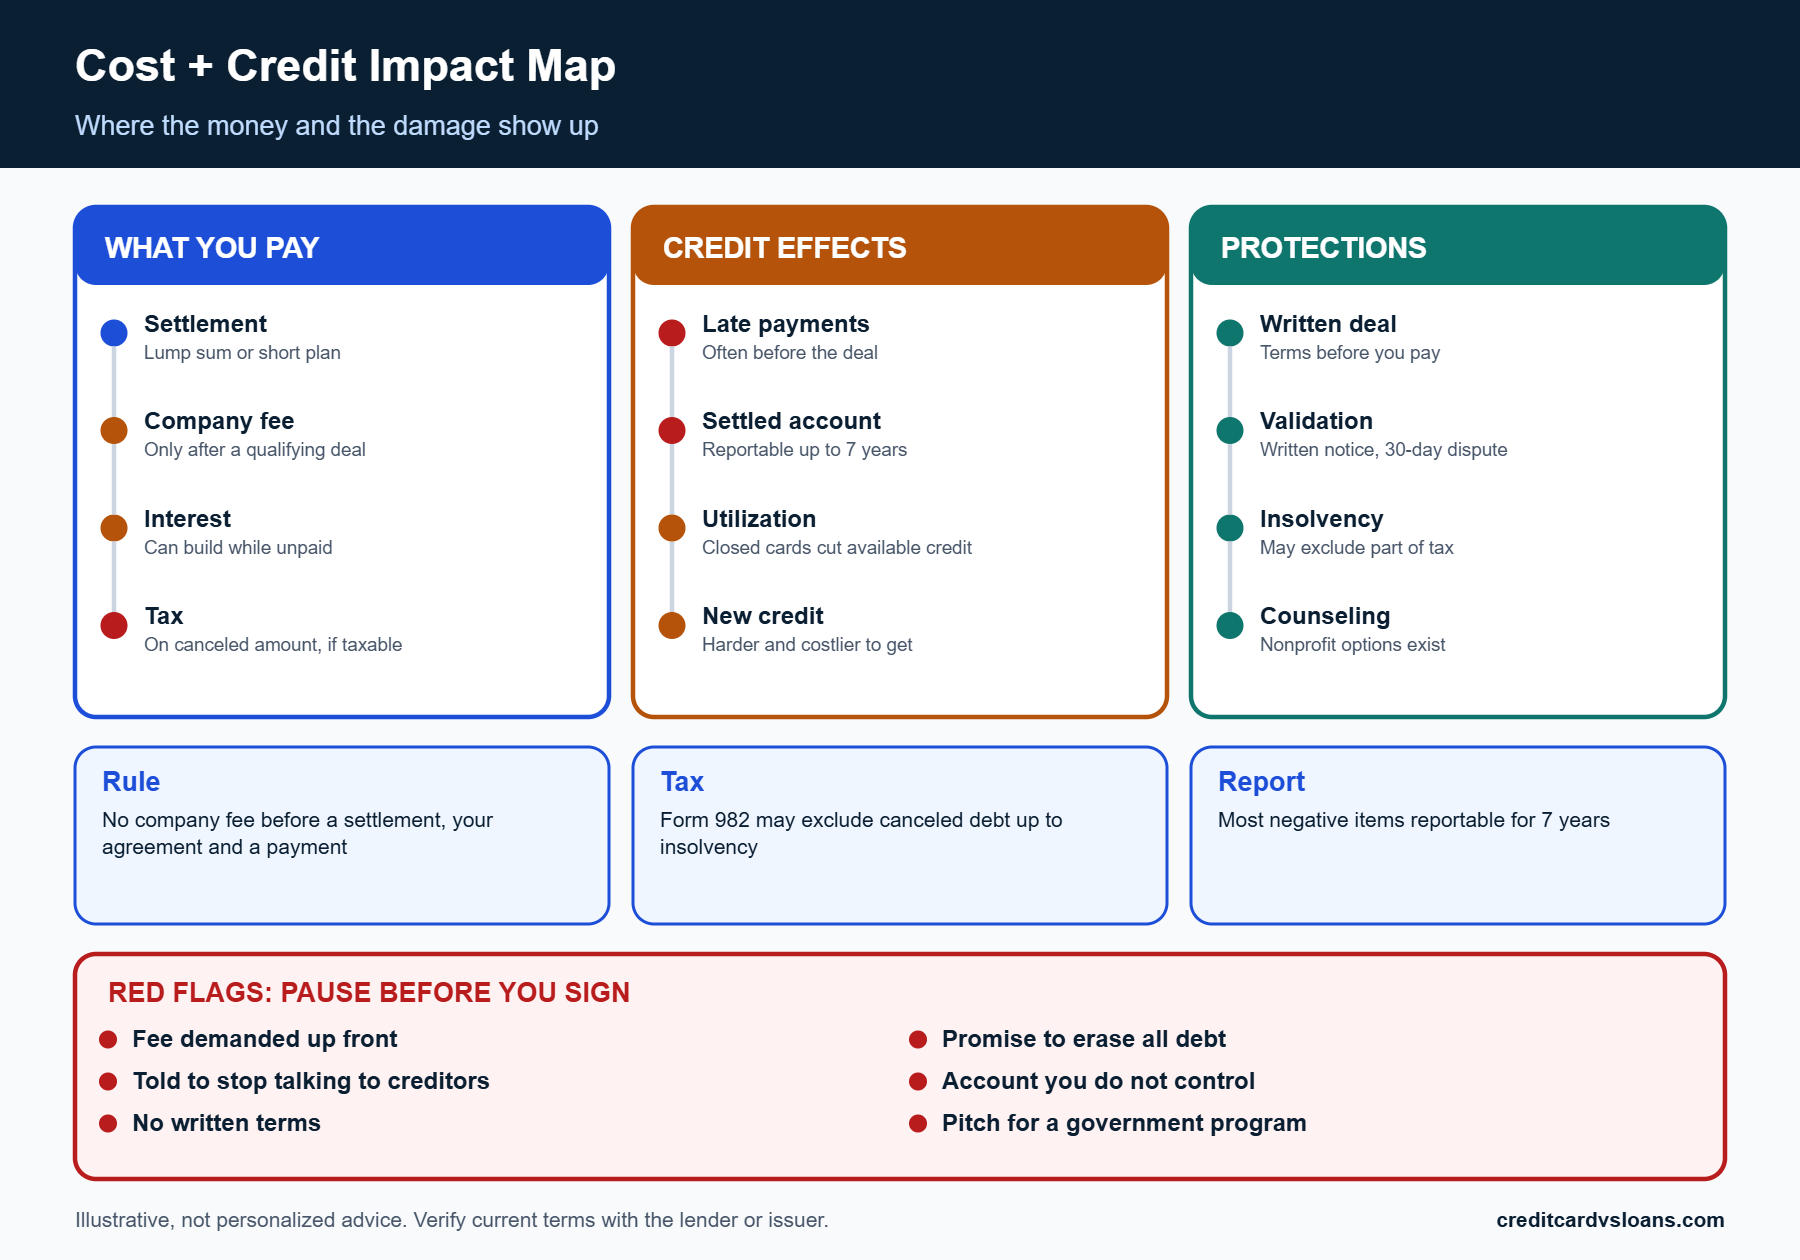
The CFPB says credit reporting companies can generally report most negative information for seven years. Lawsuits and judgments can be reported for seven years or until the statute of limitations runs out, whichever is longer, and bankruptcies can be reported for up to ten years.
The CFPB page does not address whether paying or settling a collection changes that timeline, so do not assume that settling shortens it. Ask the creditor how the account will be reported, and get the answer in writing alongside the settlement terms.
Rebuilding afterward
Recovery usually comes from on-time payments, lower balances and time. If your file is thin or damaged, a secured card or a credit-builder product can help create new positive history, and our overview of how to build credit without overspending covers beginner-friendly options in a structure that works for someone starting over.
Be wary of anyone offering to remove accurate negative items for a fee. The FTC says no one can legally remove accurate negative information from your credit reports; only time does that, though you can dispute genuine errors yourself at no cost.
Taxes on a credit card settlement: Form 1099-C and canceled debt
When forgiven debt counts as income
The general rule from the IRS
The IRS says canceled debt is generally taxable as ordinary income, reported for the year the cancellation occurred. A debt is canceled when it is forgiven or discharged for less than the full amount owed, which includes a credit card settlement. In IRS Publication 4681, paying $400 to settle a $1,000 debt leaves $600 of canceled debt.
The IRS also says that whether forgiven debt is taxable depends on your individual facts and circumstances, and that several exceptions and exclusions can apply. This article explains the basics, but a tax professional can apply them to your return.
What Form 1099-C tells you
A creditor that cancels $600 or more of a debt files Form 1099-C, Cancellation of Debt, according to the IRS form page. The form shows the canceled amount in box 2, which can include interest, fees and penalties, and box 6 shows the event code. One code, for example, covers a settlement agreement.
If the form is wrong, the IRS says to contact the creditor. If the creditor keeps collecting, the debt may not have been canceled at all. Either way, your obligation to report the correct taxable amount remains, and Publication 4681 says you must report canceled debt even if you never receive a 1099-C, unless an exception or exclusion applies.
Reducing or removing the tax bill
The insolvency exclusion and Form 982
Debt canceled while you are insolvent can be excluded from income up to the amount of your insolvency. The IRS defines insolvency as total liabilities exceeding the fair market value of all your assets immediately before the cancellation, and exempt assets such as retirement accounts count as assets in that calculation. Debt canceled in a bankruptcy case is handled by a separate exclusion.
To claim the exclusion, you attach Form 982 to your return and check the box for insolvency. The IRS notes that excluded amounts can require reducing certain tax attributes, such as loss carryovers or the basis of property, so the exclusion is not always a clean zero.
Two IRS examples that show how the math works
Publication 4681 includes a pair of credit card examples. In the first, a $5,000 credit card debt is canceled while liabilities are $15,000 and assets are $7,000, so the insolvency is $8,000 and the full $5,000 is excluded. In the second, liabilities are $10,000 and assets are $7,000, so the insolvency is $3,000: you exclude $3,000 and report the remaining $2,000 as ordinary income.
These are the IRS’s own examples, not predictions for your return. The point is that being insolvent by less than the canceled amount only shelters part of the debt.
| Situation | Canceled debt | Insolvency amount | Excluded | Reported as income |
|---|---|---|---|---|
| IRS Example 1 | $5,000 | $8,000 (liabilities $15,000, assets $7,000) | $5,000 | $0 |
| IRS Example 2 | $5,000 | $3,000 (liabilities $10,000, assets $7,000) | $3,000 | $2,000 |
| Not insolvent, no other exclusion | Any amount | $0 | $0 | Full canceled amount |
Lawsuits, collectors and old debts: the risks along the way
What can happen while you wait
Collection calls and lawsuits
A settlement program does not stop a creditor from suing. The FTC lists lawsuits among the risks of debt settlement, and it explains that a court judgment could lead to wage garnishment or a lien on your home. If you are sued, respond by the court deadline, since the FTC warns that ignoring a lawsuit can lead to a judgment and garnishment.
Collectors also keep their legal duties. The FTC’s debt collection guidance says a collector must send a written validation notice within five days of first contacting you, and that disputing the debt in writing within 30 days requires the collector to provide verification before resuming collection.
Why you should keep records of everything
Document every call, letter and payment, and keep the settlement agreement and any proof of payment indefinitely. If a collector later claims a balance remains, that paper trail is how you show the account was resolved.
The FTC also suggests that if you settle an old debt, you get a signed statement that the payment fully resolves it before paying. Treat that as a minimum, not an extra.
Old debts and the statute of limitations
Time-barred debt is not erased debt
The FTC explains that collectors have a limited time to sue, called the statute of limitations, and that once it expires the debt is time-barred. A time-barred debt may still be owed, and collectors can still contact you, but they cannot sue or threaten to sue on it.
Our guide to the credit card debt statute of limitations explains how the clock works and why it varies by state, which matters if you are negotiating an account that has been unpaid for years.
How a payment can restart the clock
The FTC warns that in some states a payment or written acknowledgment of a debt can restart the limitations clock, and in some states even a partial payment or a promise to pay can revive a debt. That risk is why the timing and wording of a first payment on an old account deserve care.
If an account may be time-barred, consider speaking with a consumer attorney or a nonprofit counselor before you pay anything or sign an acknowledgment. The CFPB and FTC both point to those resources.
Cheaper alternatives to compare before you settle
Options that keep more of your credit intact
Asking the issuer for a hardship plan
The FTC’s first suggestion for credit cards is to call the issuer and ask for a lower interest rate and a payment plan you can afford, and to get any agreement in writing. A hardship arrangement may keep the account in better standing than a settlement does, although terms vary by issuer and you should read them before accepting.
If you are still current, this is the lowest-damage way to test how much room the issuer has. It costs only a phone call.
Nonprofit credit counseling and debt management plans
The CFPB describes credit counseling organizations as usually nonprofit, with certified counselors who review your finances and may set up a debt management plan. You make one monthly payment to the organization, which pays your creditors, and the plan can lower payments, interest and fees. The FTC says plans can take 48 months or more.
Before paying a counselor anything, the CFPB recommends contacting your creditors to confirm they accepted the proposed plan. It also advises avoiding organizations that push a plan as your only option before reviewing your finances.
Consolidation and bankruptcy as comparison points
Consolidating when your credit still qualifies
If your credit file is intact, a consolidation loan or balance transfer may reduce interest without a settlement’s credit hit. Fees, rates and approval vary by lender, so compare actual offers apples-to-apples. Our overview of credit card debt consolidation by credit profile and the head-to-head on a consolidation loan versus a balance transfer show how to line options up.
The FTC cautions that some consolidation loans use your home as collateral, which turns missed payments into a risk to the house.
Bankruptcy as a legitimate last resort
The FTC says personal bankruptcy can discharge unsecured debts like credit card and medical debt and can stop collection activity, but it can remain on your credit report for up to 10 years and has costs. Chapter 7 liquidates non-exempt assets; Chapter 13 uses a three-to-five-year repayment plan.
Bankruptcy is not the right answer for everyone, but if a settlement would require years of risk and a tax bill, a consultation with a bankruptcy attorney can show whether it costs more or less overall.
Matching credit card settlement to your situation
Situations where settlement may be worth a serious look
Lasting income loss with a lump sum available
Picture a hypothetical borrower whose income dropped permanently and whose unsecured debts now exceed what any budget can repay. A family member offers a one-time sum. A creditor may be willing to discuss a lump-sum settlement, and the borrower may also qualify for the insolvency exclusion if liabilities exceed assets.
Even then, the next step is a written offer, a tax estimate and a comparison with a nonprofit counselor’s advice, not a signature on the first program that calls back. Settlement can fit here, but only with the cost stack in front of you.
Facing a lawsuit or judgment risk
If a creditor has already filed suit, settlement may be a way to stop a judgment, and a negotiated lump sum can be cheaper than the full balance plus court costs. Respond to the lawsuit by the court deadline either way, because an unanswered case can end in a default judgment and garnishment according to the FTC.
An attorney or legal aid office can tell you whether defenses such as a time-barred claim apply. Do not let a settlement company be your only source of advice on a live lawsuit.
Situations where settlement is usually the wrong tool
Still current, mainly wanting a lower payment
If you are making payments on time, deliberately falling behind to create settlement leverage can cost more in credit damage than the discount saves. A hardship plan, a nonprofit debt management plan or consolidation usually preserves more of your credit file.
That is especially true if you plan to borrow soon for a car or home. Recent delinquencies and a settled account can raise the price of that borrowing for years.
Dependent on a company’s promise of fast results
If the only reason settlement seems attractive is a sales pitch about erasing most of what you owe, slow down. The CFPB and FTC both warn that some settlement companies promise more than they can deliver, creditors may refuse to work with them, and they often cannot settle every debt.
A realistic provider will give you a written estimate of fees, timing and the savings threshold before you enroll, as the FTC rule requires. If it does not, you have learned something important for free.
| Scenario | Route to investigate | Why | What to confirm | When to avoid it |
|---|---|---|---|---|
| Current on payments, high rate | Hardship plan, consolidation or balance transfer | Preserves payment history | Fees, promotional terms, approval odds | If you will miss the new payment |
| Behind, steady income | Nonprofit debt management plan | One payment, possible lower interest | Creditors accepted the plan; fees in writing | If a counselor pushes it without reviewing your budget |
| Behind, lasting hardship, lump sum available | Direct settlement | No program fee; lump sum gives leverage | Written terms, tax effect, how it will be reported | If the debt may be time-barred and a payment could restart the clock |
| Behind, no realistic way to repay | Bankruptcy consultation | Court process can stop collection | Which debts are discharged, total costs | If most debts are non-dischargeable |
| Cold call promising to erase debt | Do not engage | Upfront fees and guarantees are scam signs | Report at ReportFraud.ftc.gov | Always |
Use Table 4 as a starting point for questions, not a verdict. Your state, your creditors and your own balance sheet change which row applies.
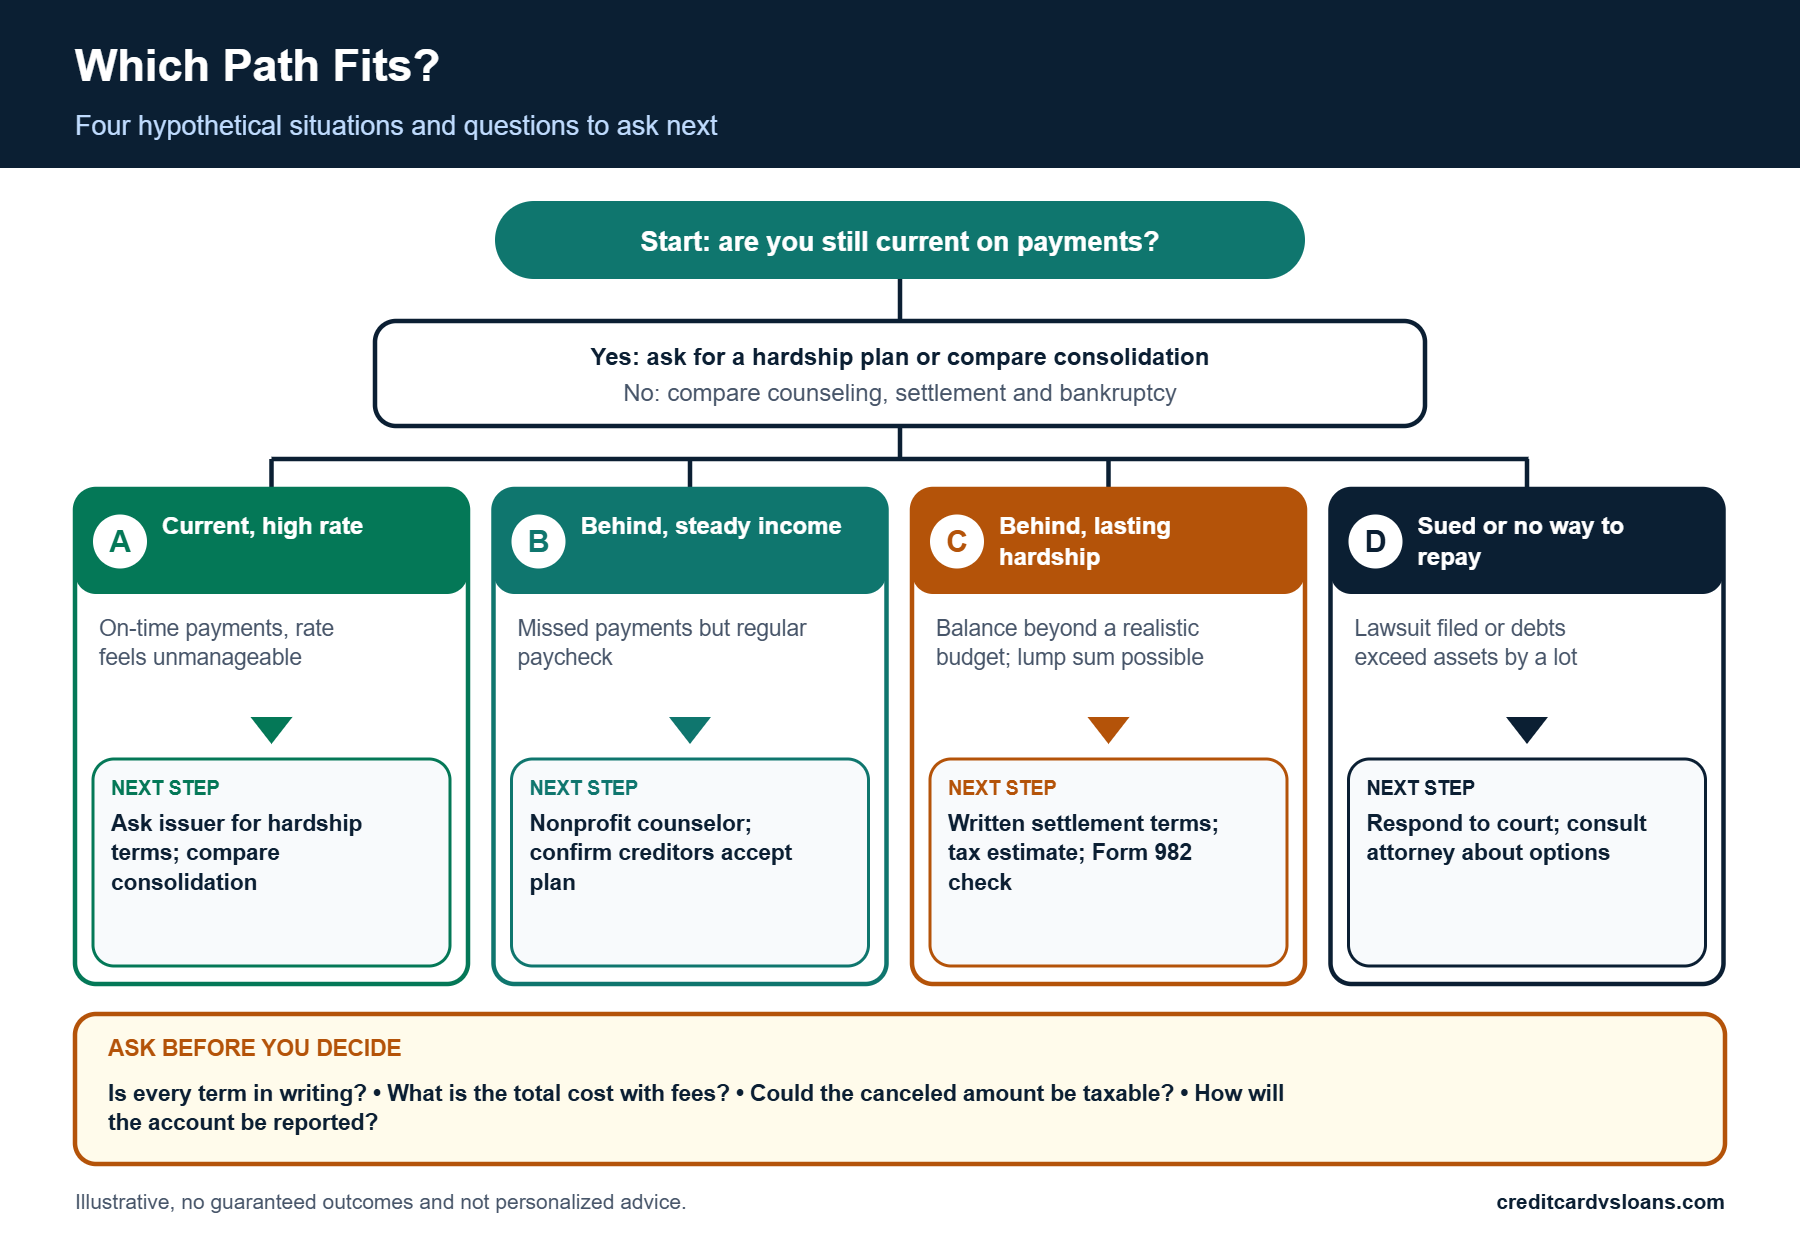
Checklist and next steps before you agree to a credit card settlement
Questions to answer before any offer
Know your numbers first
List every debt, the creditor or collector holding it, the balance, the date of your last payment and whether you have received a validation notice. Add your assets and liabilities so you can estimate whether insolvency might apply later, using the worksheet in IRS Publication 4681 as a guide.
Then decide the most you could pay in one payment or several. The CFPB’s advice is not to pay more than you can afford.
Confirm the terms in writing
Before sending money, get a written agreement that says the amount, the payment dates, and that payment resolves the account. Ask how the account will be reported to the credit bureaus and whether the creditor will send a Form 1099-C.
If a company is involved, ask for fee amounts, the savings threshold and the account structure in writing before enrolling. Searching the company’s name with the word complaint and checking with your state attorney general are free steps the FTC recommends.
Mistakes that make a settlement costlier
Paying before the terms are written down
The most expensive mistake is sending money on a verbal promise. A payment made without a written agreement can be treated as an ordinary partial payment, leaving a balance that can still be collected, and in some states it may even restart the limitations clock on an old debt. The CFPB and FTC both say to get the plan and the collector’s promises in writing before you pay.
Ask for a letter or email that names the account, states the amount, and says payment resolves the debt in full. Keep it with your bank record of the payment. If a representative resists putting the deal in writing, treat that as a reason to pause rather than a formality to skip.
Ignoring the tax form that arrives months later
A Form 1099-C can show up in the mail well after the settlement, and it is easy to dismiss as junk. The IRS says you remain responsible for reporting canceled debt that is taxable, and that you should contact the creditor if the form’s amount looks wrong.
Set a reminder to look for it in the following tax season. If you were insolvent when the debt was canceled, you will need Form 982 to exclude it, and that is easier to prepare when you kept a record of your assets and liabilities from around the date of the settlement.
Short answers to common questions
Will settling remove the debt from my credit report?
No. Settlement resolves what you owe the creditor; it does not erase the history. The CFPB says most negative information can generally be reported for seven years, and the FTC says no one can legally remove accurate negative items, only time does. Disputing genuine errors is free and worth doing.
The CFPB page does not say whether a paid or settled collection changes the reporting period, so do not rely on anyone who promises that it does. Ask the creditor how it will report the account and get the answer in writing.
Is a debt settlement company ever worth it?
Some people find a legitimate provider useful, particularly when they have several accounts and no capacity to negotiate. The FTC acknowledges that settling on your own is possible, but says programs carry the risks described above and that credit damage is likely. Whether the fee is worth the trade depends on how many debts get settled, at what discount, and what happens to accounts while you wait.
If you consider one, compare the written fee schedule against the hypothetical payment-plus-fee example earlier in this article, confirm the dedicated account rules, and check complaints with your state attorney general before enrolling.
A concrete next-step list
What to do this week
- Request validation of any collection account and keep copies of everything you send and receive.
- Call your issuer about a hardship plan before assuming settlement is the only option.
- Book a free or low-cost session with a nonprofit credit counselor, and confirm the organization with your state attorney general.
- Estimate your total liabilities and assets so you know whether the insolvency exclusion could apply.
- Talk with a tax professional before you sign anything that cancels a large balance.
The bottom line on settlement
Credit card settlement can resolve a balance you cannot repay, but the discount is only one line in the total cost. Credit damage, possible lawsuits, company fees and an income-tax bill on the forgiven amount all belong in the comparison. If a cheaper route is still open to you, use it first; if it is not, settle with written terms and a tax plan in hand.
Report any company that demands payment up front or promises to erase your debt at ReportFraud.ftc.gov, and file collection complaints with the CFPB.
- Student Credit Cards: How to Build Credit Without Overspending
- Credit Card Debt Consolidation: Best Options by Credit Profile
- Debt Consolidation Loan vs. Balance Transfer Card: Which Saves More?
- Credit Card Debt Statute of Limitations: What It Means and What It Doesn’t
- Does Applying for a Credit Card Hurt Your Credit Score?
- IRS: Topic no. 431, Canceled debt: Is it taxable or not?
- IRS: About Form 1099-C, Cancellation of Debt
- IRS: Publication 4681, Canceled Debts, Foreclosures, Repossessions, and Abandonments
- IRS: Instructions for Form 982
- FTC: How to Get Out of Debt (FTC publication, December 2025)
- FTC: Debt Relief Services and the Telemarketing Sales Rule: A Guide for Business
- CFPB: How do I negotiate a settlement with a debt collector?
- CFPB: How long do negative items remain on my credit report?
- CFPB: What is credit counseling?
- FTC: Debt collection FAQs
Last updated: October 22, 2026. Rates, fees and lender rules change; verify current terms before acting.
The information on creditcardvsloans.com is provided for general educational and informational purposes only. It is not financial, legal, tax, credit, accounting or investment advice, and reading it does not create an advisor-client, fiduciary or any other professional relationship. Nothing here is an offer, solicitation or recommendation to borrow, lend or apply for any product.
Credit scores, interest rates, fees, eligibility rules, lender policies and laws change frequently and vary by lender, location and individual circumstances. Examples, figures and scenarios are illustrative only, do not predict your results and do not guarantee approval, savings, a particular rate or a credit-score outcome. Always confirm current terms directly with the lender or issuer and read the full agreement before you apply or sign.
Although we aim for accuracy and use reputable sources, we make no representations or warranties, express or implied, about the completeness, accuracy, reliability or timeliness of the content. Content may be drafted with the assistance of automated tools, so errors or omissions may still occur. Links to third-party sites are provided for convenience; we don’t control and aren’t responsible for their content.
To the fullest extent permitted by law, creditcardvsloans.com and its owners, editors, authors, contributors and affiliates disclaim all liability for any loss, damage or expense arising directly or indirectly from your use of, or reliance on, this content. Before making financial decisions, consult a licensed professional, such as a qualified financial advisor, attorney, tax professional or nonprofit credit counselor, who can consider your complete situation.