To rebuild credit after bankruptcy safely, start by confirming what your reports show, then add one or two low-cost accounts you can pay in full, and let consistent on-time payments do the slow work. There is no shortcut and no legitimate service that can erase an accurate bankruptcy early. What you can control is the record you create from now on.
Bankruptcy is a legal process that wipes out or restructures many debts. It is not the end of your ability to borrow, but it does change how lenders see you for years. This guide is about the practical rebuild: what to check first, which tools tend to be safest, how to sequence them, and which offers to avoid. It does not give legal advice about whether to file or how your particular case is treated; for that, talk to a bankruptcy attorney or the court-approved resources your case provides.
If you are specifically weighing a personal loan as part of rebuilding, we cover that in our guide to taking out a personal loan to build credit, and the mechanics of how loans touch a score are in our explainer on the personal loan credit score impact. Here, we focus on the order of operations after a discharge or while in a repayment plan.
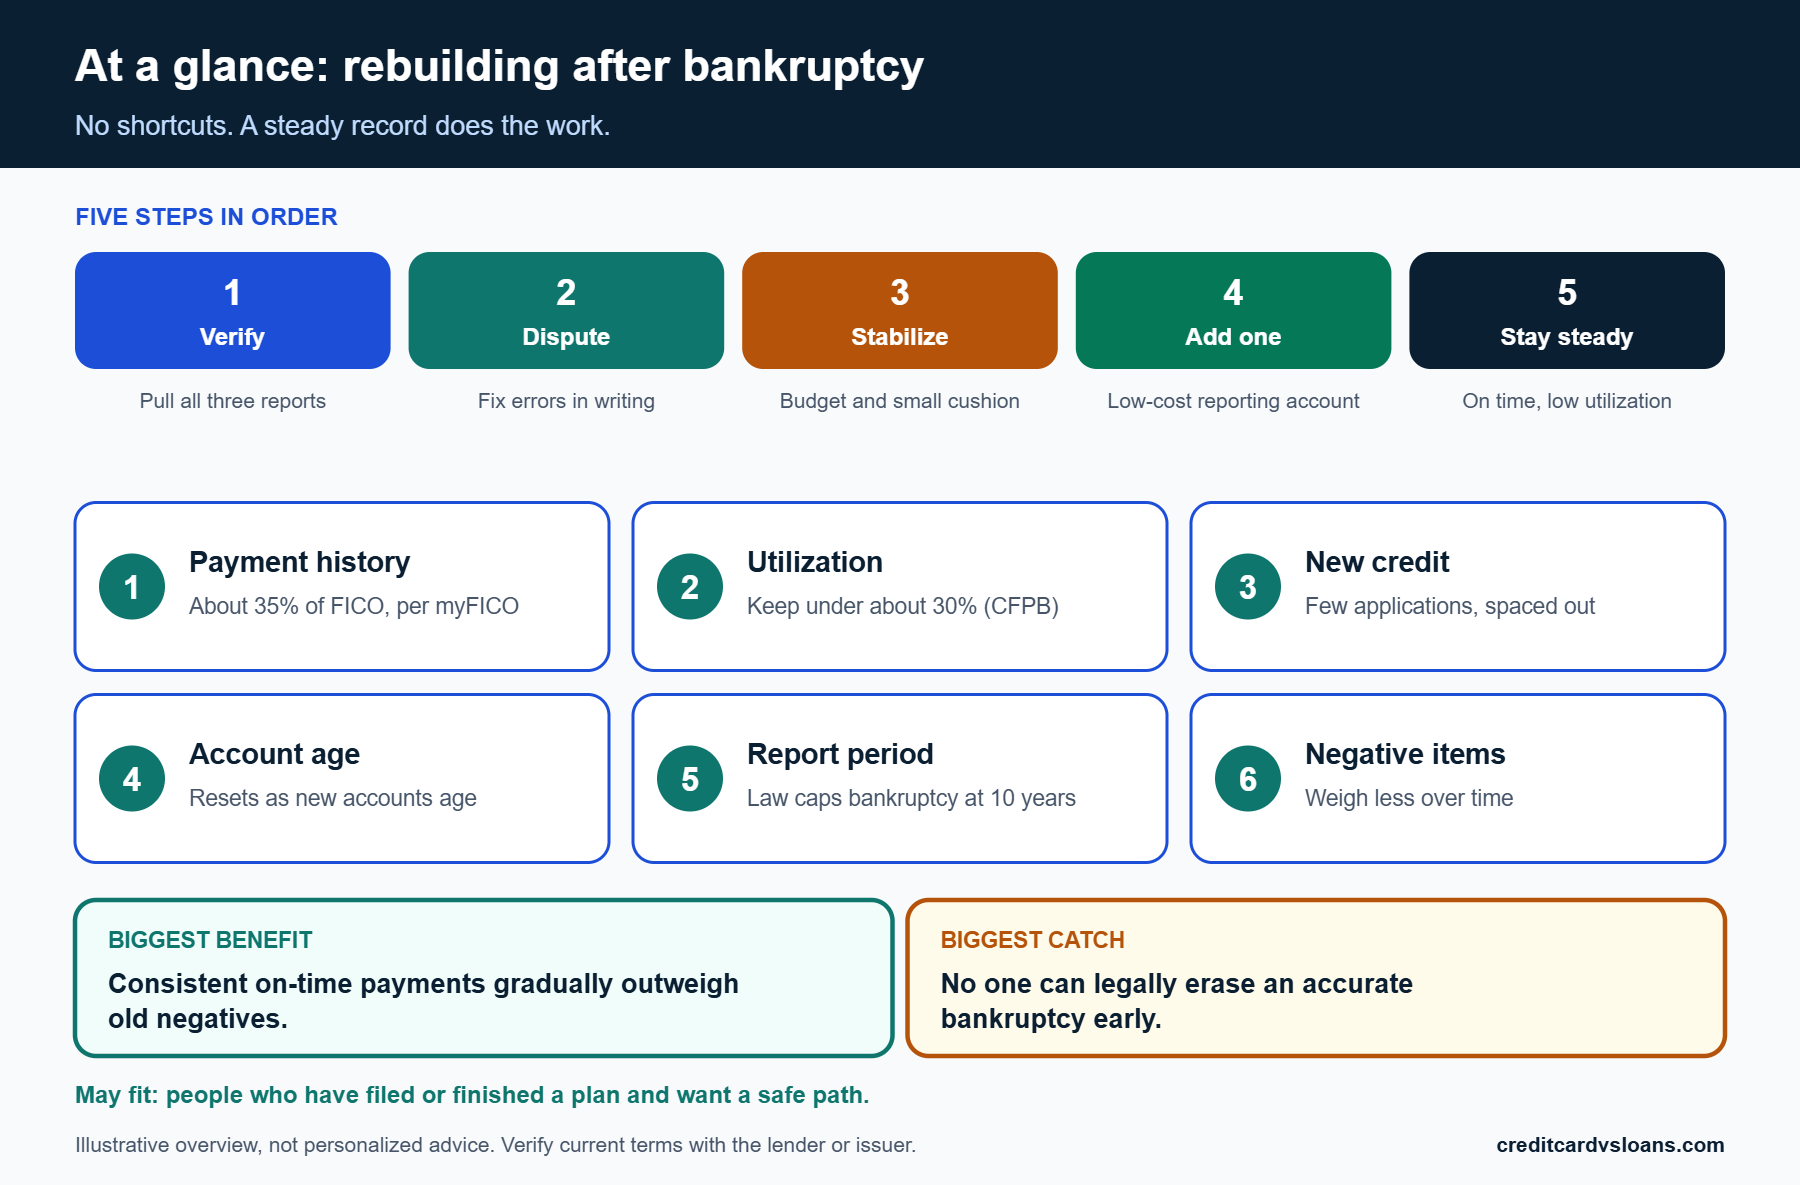
- Check your reports first. Make sure accounts included in the bankruptcy are reported accurately, and dispute mistakes with the bureau and the lender.
- Start small and cheap. The CFPB points people rebuilding credit to secured cards and credit-builder loans.
- On-time payments are the core. myFICO says negative items matter less over time as long as you keep paying on time.
- Be wary of promises. The FTC says no company can legally remove correct negative information, and credit repair firms cannot charge before they have done the work.
- Timelines differ. The law caps how long a bankruptcy can be reported; how fast your options improve depends on your whole file.
Reporting periods come from the Fair Credit Reporting Act as posted by Cornell Law (15 U.S.C. 1681c) and from myFICO. Court process details come from the U.S. Courts bankruptcy basics pages. Bankruptcy and consumer-reporting rules can vary in practice, so confirm details for your case with an attorney, and check your own reports.
The short answer: how to rebuild credit after bankruptcy
What to expect and what not to
Realistic expectations
Rebuilding is gradual. In the first months you are mainly establishing that new accounts are reported accurately and paid on time. Over the next couple of years, the record of consistent payments starts to outweigh the older negative entries in how lenders read your file. myFICO describes the effect of negative items as lessening over time, especially if you keep paying on time, until they eventually drop off the report.
What you should not expect is a fast jump. No one can promise a score by a date, and anyone who does is selling something. Scores also vary by model and bureau, as the CFPB explains, so your numbers may differ between sources.
The order that tends to work
The sequence we recommend is simple. First, verify your reports and fix errors. Second, stabilize your budget and build a small cash cushion so you do not need to borrow in an emergency. Third, open one low-cost account designed for rebuilding, such as a secured card, and use it lightly. Fourth, add a second type of account only if it makes financial sense. Fifth, wait, and keep paying on time.
Each step protects the next. A new account on top of a budget that cannot support it is how people end up with a second setback.
What this guide does not cover
Legal questions about your case
This article is general information and not legal advice. Questions about which debts were discharged, whether to reaffirm a debt, how a repayment plan works in your court, or when you can file again belong with a bankruptcy attorney or the trustee in your case. The U.S. Courts explain, for example, that some debts survive a discharge, including certain taxes, alimony and child support, and some student loans.
If a creditor contacts you about a debt you believe was discharged, keep records and consult your attorney before paying anything.
Whether to file in the first place
Nothing here is a recommendation for or against filing. If you are still deciding, the court requires individuals to complete credit counseling from an approved agency within 180 days before filing, according to the U.S. Courts, and a nonprofit credit counselor can help you compare options.
If you have already filed, the rest of this article is for you.
| Phase | Main goal | Typical tools |
|---|---|---|
| Weeks 1 to 4 | Verify and correct reports | Free reports, written disputes |
| Months 1 to 3 | Stabilize budget; build a cushion | Savings, bill calendar |
| Months 3 to 12 | Start a low-cost reporting account | Secured card, credit-builder loan |
| Years 1 to 3 | Show a steady pattern | On-time payments, low utilization |
| Ongoing | Avoid high-cost traps | Skepticism, written terms |
What bankruptcy does to your credit reports, and for how long
How long it can be reported
The statutory ceiling
Under the Fair Credit Reporting Act (15 U.S.C. 1681c), a consumer report generally may not include bankruptcy cases older than ten years, measured from the date of entry of the order for relief or the date of adjudication. Other adverse items, such as collection accounts and charge-offs, are generally limited to seven years, with collections and charge-offs counted from a point 180 days after the start of the delinquency.
That ten-year figure is a legal ceiling, not a promise that every case is reported for the full period. The statute sets the outer limit for what can be included.
Why you may see different numbers
You may read that a completed Chapter 13 stays for seven years while a Chapter 7 stays for ten. myFICO describes it that way, stating that a bankruptcy stays on the report up to 10 years from the filing date for Chapter 7 and 7 years from the filing date for a completed Chapter 13. The statute itself speaks of a ten-year limit measured from the order for relief. The difference reflects reporting practice by the credit bureaus and the way the dates are measured.
Because details vary, the dependable approach is to look at your own reports. Each bureau shows the bankruptcy with dates. If something looks off, you can dispute it, and an attorney can explain how the dates apply to your case.
What should and should not appear
Accounts included in the bankruptcy
After a discharge, accounts that were included in the bankruptcy should be reported accurately, usually with a zero balance or a notation that they were included. Mistakes are common enough to be worth checking: an old balance still showing as owed, a discharged account marked as past due, or a debt reported as open when it should be closed.
The CFPB explains how to dispute errors: contact the credit reporting company in writing with supporting documents, and also dispute with the furnisher, the business that gave the information. Furnishers generally must investigate and respond within 30 days of receiving your dispute.
Debts that were not discharged
Some debts survive bankruptcy. The U.S. Courts list examples such as certain taxes, alimony and child support, and some student loans, and note that a discharge does not remove a lien on property. These debts can continue to appear on your reports and can still be collected under their own rules.
If you are unsure about the status of a debt, ask your attorney and ask the creditor to confirm in writing. For older debts and the question of when collection is time-barred, see our guide to the credit card debt statute of limitations, which explains what that concept does and does not mean.
The first 90 days: get your footing before you borrow
Reports and records
Pull all three reports and read every line
Request your reports from the three nationwide bureaus. The FTC points consumers to AnnualCreditReport.com for free reports, and the CFPB advises checking your reports at least once a year. Requesting your own reports does not hurt your score, per the CFPB.
Read each report slowly. Note the bankruptcy entry and its dates, each account included in the case, any accounts you do not recognize, and any collection entries for debts that should have been discharged. Make a list, and attach the relevant pages of your bankruptcy paperwork to each item you plan to dispute.
Dispute what is wrong, in writing
The CFPB recommends explaining the problem in writing, including supporting documents (copies, not originals), and also writing to the furnisher. Consider certified mail with a return receipt and keep copies of everything. If the furnisher finds its information was wrong or cannot verify it, it must correct or remove it and notify the credit reporting companies.
The FTC also notes you can do this yourself for free. There is no need to pay a company to send dispute letters you can send yourself.
Cash flow and cushion
Write a bare-bones budget
After bankruptcy, the most protective step for your credit is a budget that works. List income, fixed bills and essentials, and see what is left. If the number is thin, the right move is to hold off on new credit until it is not, because a missed payment on a new account is the surest way to extend your recovery.
If you need help with the budget, the FTC suggests asking your credit union, university or military personal financial manager about nonprofit credit counseling programs.
Build even a small emergency cushion
A modest savings balance prevents the typical spiral: a surprise bill, a high-cost loan, then a missed payment. The target depends on your situation, and there is no one-size answer. Even a few hundred dollars can keep a flat tire from becoming a default.
Keep the cushion in an account that is separate from your daily checking so you do not spend it without noticing. If your bank offers a no-fee savings account, use it.
New credit applications right after a discharge can add hard inquiries and accounts you cannot yet afford to carry. Applying for a lot of credit in a short period can signal financial trouble to lenders, as the CFPB notes. Slow is safer.
Choosing rebuilding tools: costs and trade-offs
Secured credit cards
How a secured card works
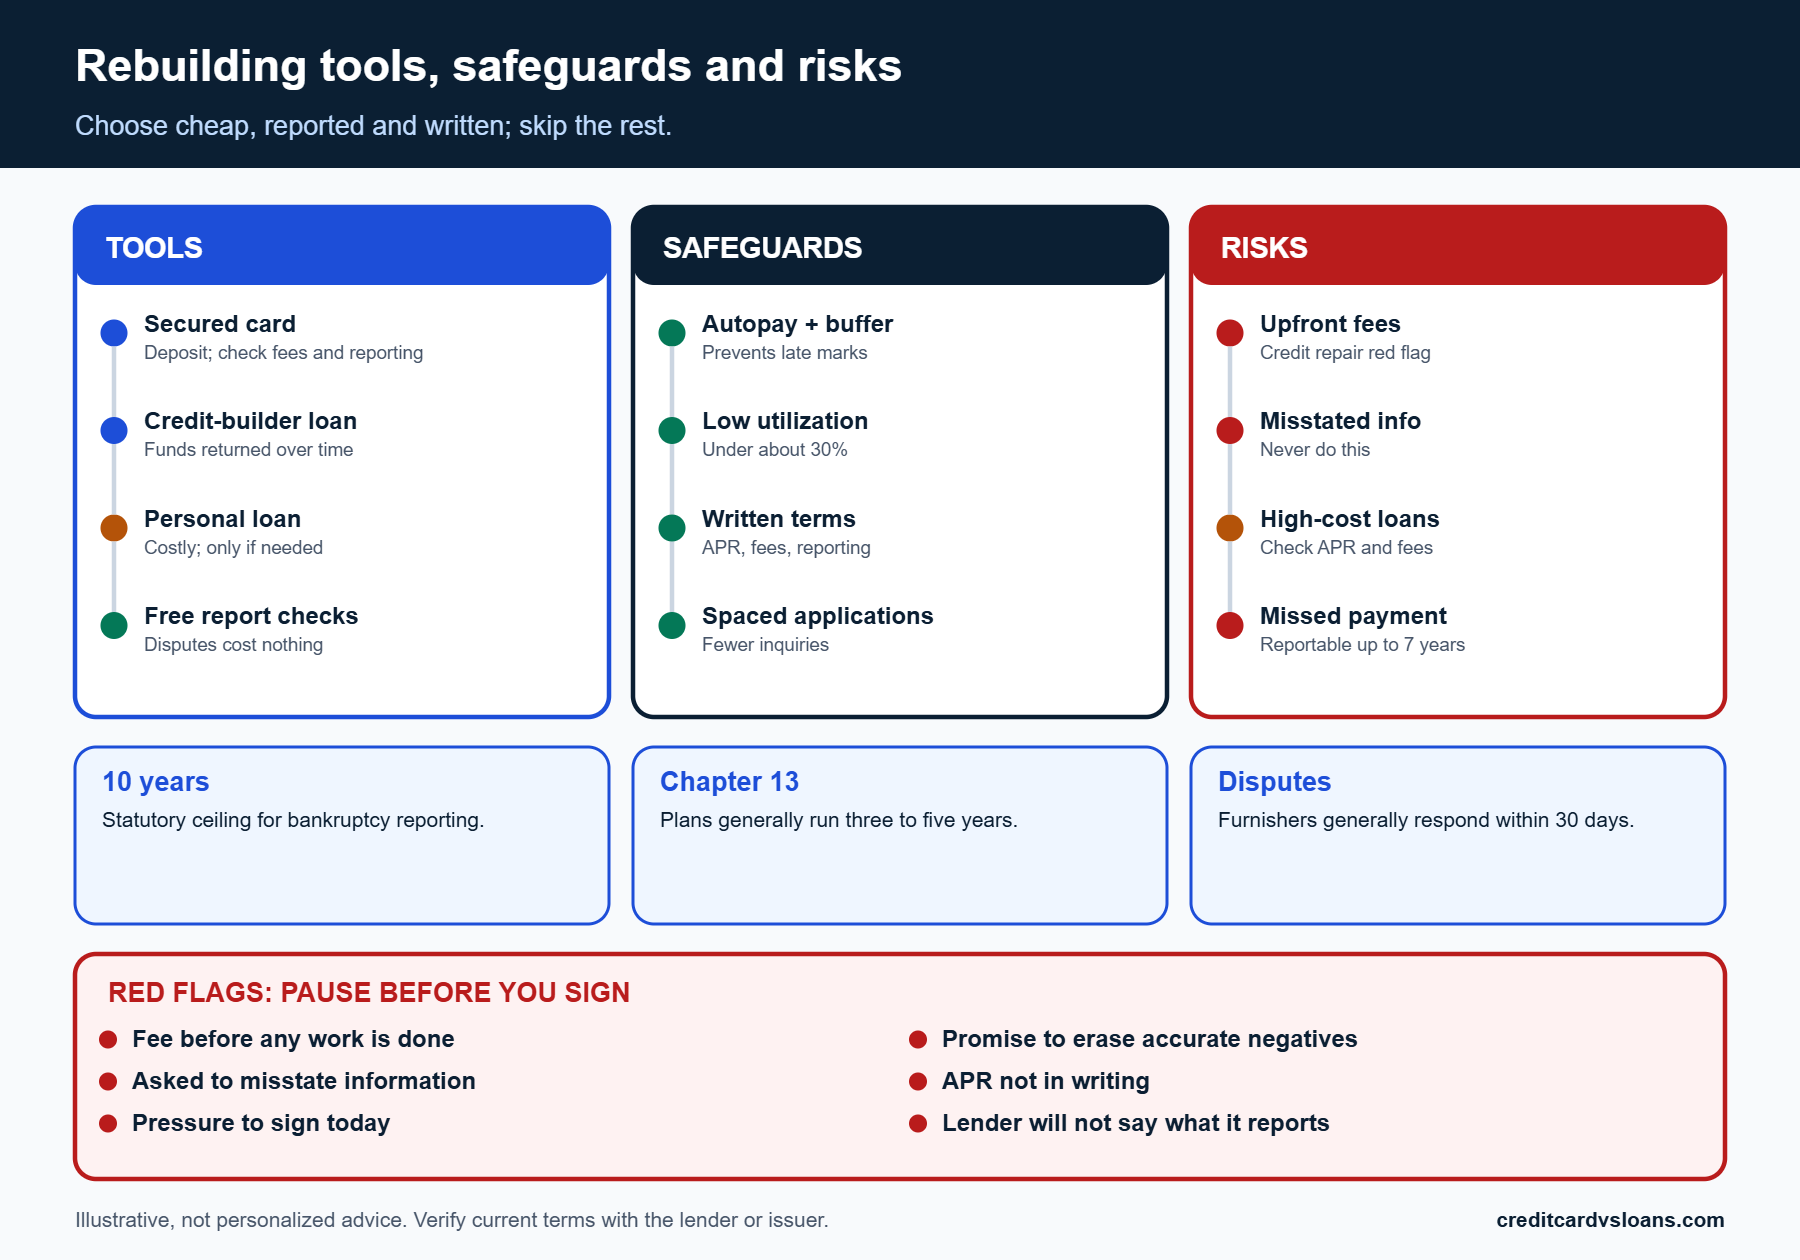
A secured card generally requires a cash deposit that serves as your credit limit or backs it, and the issuer reports your activity to the credit bureaus. The CFPB lists secured cards among the tools for people new to credit or rebuilding. Used for one or two small purchases and paid in full, a secured card creates a clean monthly record without interest.
Before applying, compare annual fees, other fees, whether the issuer reports to all three bureaus, how the deposit is returned, and whether there is a path to an unsecured card. If the terms are unclear, choose another product. We discuss starter-card basics and how limits and utilization work in our student credit card guide, which applies to anyone with a thin or reset file.
Keeping utilization low on a small limit
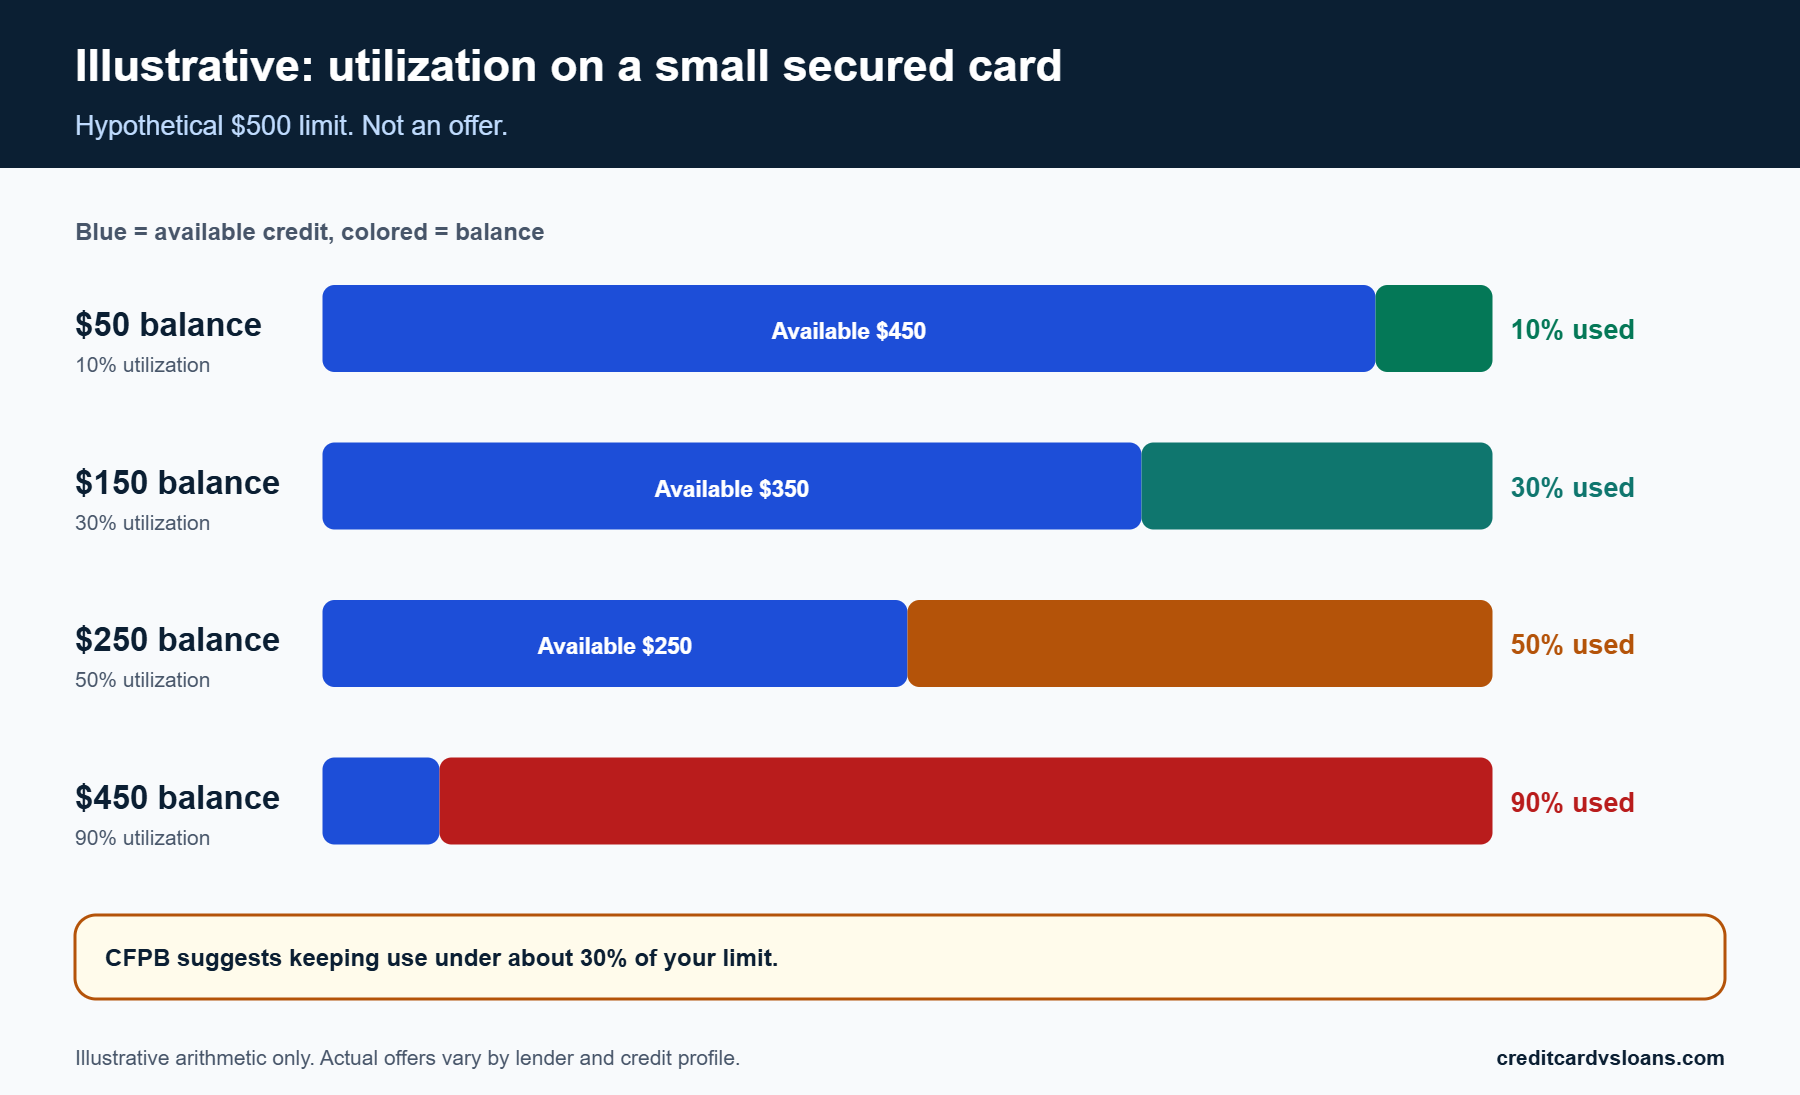
A small limit means a small purchase can be a large share of it. The CFPB suggests keeping credit use under 30% of your total limit. The chart below uses a hypothetical $500 limit to show how quickly the share rises with a few purchases. It is an illustration only.
One practical approach is to charge a single recurring bill, set autopay to pay the statement balance in full, and leave the card alone otherwise. That keeps both utilization and risk low.
Credit-builder loans and other options
What the CFPB found
The CFPB describes a credit-builder loan as one where the lender places an amount equal to the loan into a locked savings account, you make monthly payments, and the lender returns the payments to you minus interest and fees. These loans were typically $300 to $1,000, and the lender reports payment history to the three major credit reporting agencies as a standard installment loan.
In the CFPB's study of one credit union's product, borrowers with no existing debt were more likely to have a score and saw scores rise by up to 60 points on average from a starting score of 560. For borrowers with existing debt, the benefits were much smaller, and the loan slightly lowered scores on average, suggesting they struggled to fit the payments into existing bills. About 40% of participants made at least one late payment. It was one product at one credit union, so results will vary.
Where a personal loan fits, if at all
A regular personal loan is an expensive way to add an installment account, and approval may be limited or pricier right after a bankruptcy. Our guide on borrowing to build credit compares it to cheaper options. If you do consider one, borrow only what you need, prequalify with soft pulls, and confirm bureau reporting.
Whatever you choose, favor products with clear written terms, no upfront fees and reporting to all three bureaus.
| Tool | Typical cost | Reporting | Main risk |
|---|---|---|---|
| Secured card | Deposit; check fees | Confirm all three bureaus | High utilization on a small limit |
| Credit-builder loan | Interest and fees; funds returned over time | Typically reported as installment, per CFPB | Late payments; terms vary |
| Personal loan | Interest; may be high after bankruptcy | Ask the lender | Payment strain, fees |
| Dispute and monitor reports | Free | N/A | Takes time |
A realistic timeline for the first few years
Year one: prove the pattern
Open one account, then wait
Choose a single low-cost account and use it in a way that is nearly boring: a small recurring charge, paid in full by autopay, every month. Resist the urge to open several accounts at once. Each application can add an inquiry, and each new account lowers the average age of your accounts.
According to myFICO, only inquiries from the last 12 months are considered in a FICO Score, and one extra hard inquiry lowers a score by fewer than five points for most people. That is small, but several together look like urgency, and urgency is what you are trying to avoid communicating.
Check in at set points
Check your reports about one to two months after opening the account to confirm it reports, and again at about six months and a year. Look for the right limit, the right balance and a clean payment record. If the account is not reporting to all three bureaus, ask the issuer why.
Avoid obsessing over the score in between. Month-to-month changes can come from model, bureau or timing differences, as the CFPB notes, and they do not necessarily mean anything about your behavior.
Years two and three: widen carefully
Graduating or adding a second account
After a year or more of clean reporting, you may be offered a higher limit or a chance to move to an unsecured card. Take it if the terms are reasonable and the card costs nothing extra. A second account type, such as an installment loan you would take anyway, can be considered once your cash flow is steady.
Weigh any new account against its cost. If you would not take the loan without the credit-building angle, revisit our guide on borrowing to build credit before you sign.
Looking toward bigger loans
If you are planning a car or home purchase, talk to the lender early about their requirements after bankruptcy. Some lenders have waiting periods or extra documentation requirements after bankruptcy, and these differ by lender and loan type, so we cannot give you a number that applies to everyone. Ask directly, and ask what a recent new account would do to your application.
A lender that works with post-bankruptcy borrowers may price the loan higher. Compare offers apples-to-apples using APR and fees, and keep applications within a short window and limited in number.
| When | What you do | What to confirm |
|---|---|---|
| Month 1 | Review reports; dispute errors | Bankruptcy and included accounts are accurate |
| Months 3 to 6 | Open one low-cost account | It reports; utilization stays low |
| Month 12 | Review limit and fee terms | No new negatives; payment record clean |
| Years 2 to 3 | Consider a second account if needed | Cost and fit, not the score, drive the decision |
| Before a major loan | Ask the lender about requirements | Waiting periods and documentation |
Offers to avoid while rebuilding
Credit repair and "fresh start" promises
What the FTC says is a warning sign
The FTC's consumer alert of January 7, 2026 lists these warning signs: companies that offer to remove accurate negative information from your report, requests for payment before any work is done, pressure to misstate information on credit applications, and claims that they can do more than they can. It adds that such companies cannot legally remove correct and up-to-date negative information, must provide a written contract with a three-day right to cancel, and may not take payment before performing services.
Someone claiming they can wipe a bankruptcy off your reports for a fee fits those warning signs. myFICO is equally direct that no one can remove a legitimate negative item from your credit report.
Pitches that ask you to hide information
Any scheme that asks you to leave information off an application, use a different identifier, or otherwise misstate your history is a path to bigger legal and financial trouble. The FTC specifically lists pressure to misstate information on credit applications as a red flag. Decline, and report it if you can.
If you are unsure whether an offer is legitimate, take it to a nonprofit credit counselor or your state attorney general's consumer office before you pay.
High-cost credit after bankruptcy
Why post-bankruptcy borrowers are targeted
After a bankruptcy, a borrower can feel that any approval is a gift. Some lenders know this and price accordingly, with high interest, heavy fees, or terms that are difficult to meet. The pressure to accept the first yes is the problem.
Our guide to predatory lending warning signs details specific patterns: fees demanded before funding, loan terms left blank, rollovers and payment structures that keep you in debt.
A short test before you sign
Ask five questions. What is the APR in writing? What fees are charged, and when? Is there a prepayment penalty? Which bureaus does the lender report to? What happens if I miss a payment? If the lender will not answer in writing, do not sign.
If the cost seems out of proportion to the amount, step back. A cheaper tool, even if it is slower, is almost always the safer one.
Do not pay anyone to erase an accurate bankruptcy, do not hand over bank logins, and do not sign an agreement with blanks. If something feels rushed, it is.
Special situations after bankruptcy
Chapter 7 versus Chapter 13
If you received a Chapter 7 discharge
The U.S. Courts explain that individual debtors usually receive a discharge in Chapter 7, which releases them from personal liability for most debts, and that the court typically issues the discharge 60 to 90 days after the date first set for the creditors' meeting unless someone objects. Once the discharge is entered, you can begin rebuilding right away. Many people start by correcting reports and opening a secured card within a few months.
Keep your discharge paperwork. If an old creditor reports or collects on a discharged debt, the paperwork is your evidence.
If you are in or finished a Chapter 13 plan
In Chapter 13, the U.S. Courts explain that the debtor makes fixed payments to a trustee under a plan that generally runs three to five years, depending on income, and may receive a discharge after completing all plan payments. During the plan, taking on new credit usually requires the trustee's or court's permission, so ask your attorney before opening anything. After the plan is complete, the rebuilding steps above apply.
Making all plan payments on time is itself a long record of payment behavior, though how it shows up in your reports depends on how each creditor reports. Check what is shown.
Household and life events
Shared accounts and co-signers
Joint accounts and co-signed debts can complicate the picture, because a bankruptcy filed by one person does not necessarily resolve a co-signer's or joint holder's obligation. If you share accounts with a spouse or someone who co-signed for you, ask your attorney how those accounts were treated and what the other person's reports should show.
Keep joint accounts current if they remain open. A late payment on a joint account can affect everyone named on it.
Housing and employment concerns
Landlords and some employers may look at credit reports, with the rules depending on the situation. If you are applying for housing, be ready with a brief, factual explanation of the bankruptcy, proof of steady income and, if possible, a record of recent on-time payments. A calm, documented story helps more than an apology.
If an adverse decision is based on your report, you generally have the right to a notice naming the reporting company. Use it to check that company's report for errors.
| Question | Why it matters |
|---|---|
| Which of my debts were discharged, and which survived? | Tells you what should show as zero and what you still owe |
| How should included accounts appear on my reports? | Gives you a basis for accurate disputes |
| Can I take on new credit during my plan? | Chapter 13 plans may require permission |
| What are the waiting periods for a home or auto loan? | They differ by lender and loan type |
| What are the rules if I need to file again? | Eligibility depends on prior discharges and chapter |
Habits that protect a rebuilt file
Payment habits
Automate the minimum, pay the statement balance
Set autopay to at least the minimum so a forgotten date never produces a late mark, and add a reminder to pay the full statement balance. The CFPB notes that you do not need to carry a balance to build a good score and that paying in full each month gives the best scores and the lowest interest costs. After bankruptcy, interest is a cost you can avoid entirely with a small, fully paid card.
Keep a buffer in the checking account that funds autopay. A payment that bounces creates a fee at your bank and may trigger a late mark at the lender.
Treat every due date as non-negotiable
Under the Fair Credit Reporting Act, most adverse items can be reported for up to seven years, so a late payment during your rebuild is a setback with a long tail. Calendar due dates for every account, including utilities and phone bills that can go to collections, and pay those first when money is tight.
If you see a problem coming, contact the creditor before the due date. Options vary by creditor and are not guaranteed, but silence is rarely the better choice.
Monitoring habits
Quarterly report checks in year one
During the first year, review your reports about every few months, focusing on new accounts, balances and any collection entries. The CFPB advises watching old, unused accounts for signs of identity theft, which is a risk for anyone with a complicated history. If you spot something unfamiliar, dispute it and consider additional protections.
After year one, a yearly review is generally enough unless something changes.
Keep documents in one place
Store your discharge or plan completion papers, dispute letters, certified-mail receipts and account statements in a single folder, paper or digital. When a lender asks for proof, or when a bureau asks for supporting documents, you will have them on hand.
A tidy paper trail also reduces stress. Rebuilding is a multi-year project, and small organizational habits make it easier to sustain.
Questions people ask after the paperwork is done
Timing questions
How soon can I apply for new credit?
There is no single legal waiting period for opening a secured card or similar product after a discharge, but approval depends on each issuer. Many people begin within a few months, after reports are corrected and a budget is stable. Larger loans such as mortgages and car loans can carry lender-specific waiting periods, so ask the lender.
Prequalify where possible using soft pulls, which, per the CFPB, do not affect your scores, and avoid scattering formal applications.
When will my score recover?
Nobody can say, and a number promised in advance is a warning sign. Recovery depends on your starting score, the accounts and payment patterns you build, the scoring model, and the bureau. myFICO says negative items weigh less over time as long as you keep paying on time, which is the dependable part.
Measure progress by milestones you control: reports are accurate, accounts are paid on time, utilization is low, and no new negatives appear.
Cost questions
Is it worth paying for a credit-building service?
Usually not. Disputes and report checks are free, secured cards and credit-builder loans are products you can compare yourself, and nonprofit credit counseling is available through many credit unions and community organizations. A paid service that promises results is the pattern the FTC warns about.
If you do pay for something, get a written contract, understand the cost and cancellation rights, and never pay before services are performed for a credit repair company, which the FTC says is not permitted.
Should I close the accounts I have left?
Not automatically. Closing an account removes its limit from your utilization math and can shorten your average account age over time. If an account has a fee you cannot justify, compare the cost to the benefit, and ask the issuer about a no-fee version before closing.
When in doubt, an open account with a zero balance and no fee is generally harmless.
Addressing the causes, not just the score
Understanding what led to the filing
Separate one-time shocks from structural gaps
Bankruptcy often follows a shock such as a medical event, a job loss or a divorce, but sometimes it follows a long gap between income and expenses. The rebuild looks different depending on which it was. After a one-time shock, restoring a normal budget and a small cushion may be enough. After a structural gap, new credit can recreate the same trap unless the monthly numbers change.
Write down, in a few sentences, what happened. It sounds simple, but a clear account of the cause helps you choose tools sensibly and explain your history calmly to a future lender or landlord.
Choose guardrails that fit your pattern
If overspending on cards was part of the story, a secured card with a small limit is itself a guardrail: it cannot grow beyond your deposit. If irregular income was the issue, a larger cushion and a lower fixed-payment load matter more than any score tactic. If medical or family costs drove it, ask about hospital financial assistance and payment plans before using credit.
The point is to build structures that make the good outcome the default, because willpower alone tends to fail in the month when money is tightest.
Working with a counselor
What nonprofit counseling can and cannot do
Nonprofit credit counselors can review your budget, explain options and sometimes help set up payment arrangements for debts that remain. They cannot erase accurate negative items or promise a score. The FTC suggests asking a credit union, university or military personal financial manager about nonprofit credit counseling programs.
Ask any counselor how they are paid, what they charge, and whether you will receive everything in writing. A reputable program will be clear about fees before it begins.
Questions to ask before you start
Ask whether the organization is a nonprofit, what services are free, what any fee covers, and how long the arrangement lasts. Ask what happens to your credit if you stop. If answers are vague, look elsewhere.
A good counselor will also tell you when you do not need their service, and that honesty is itself a sign you are in the right place.
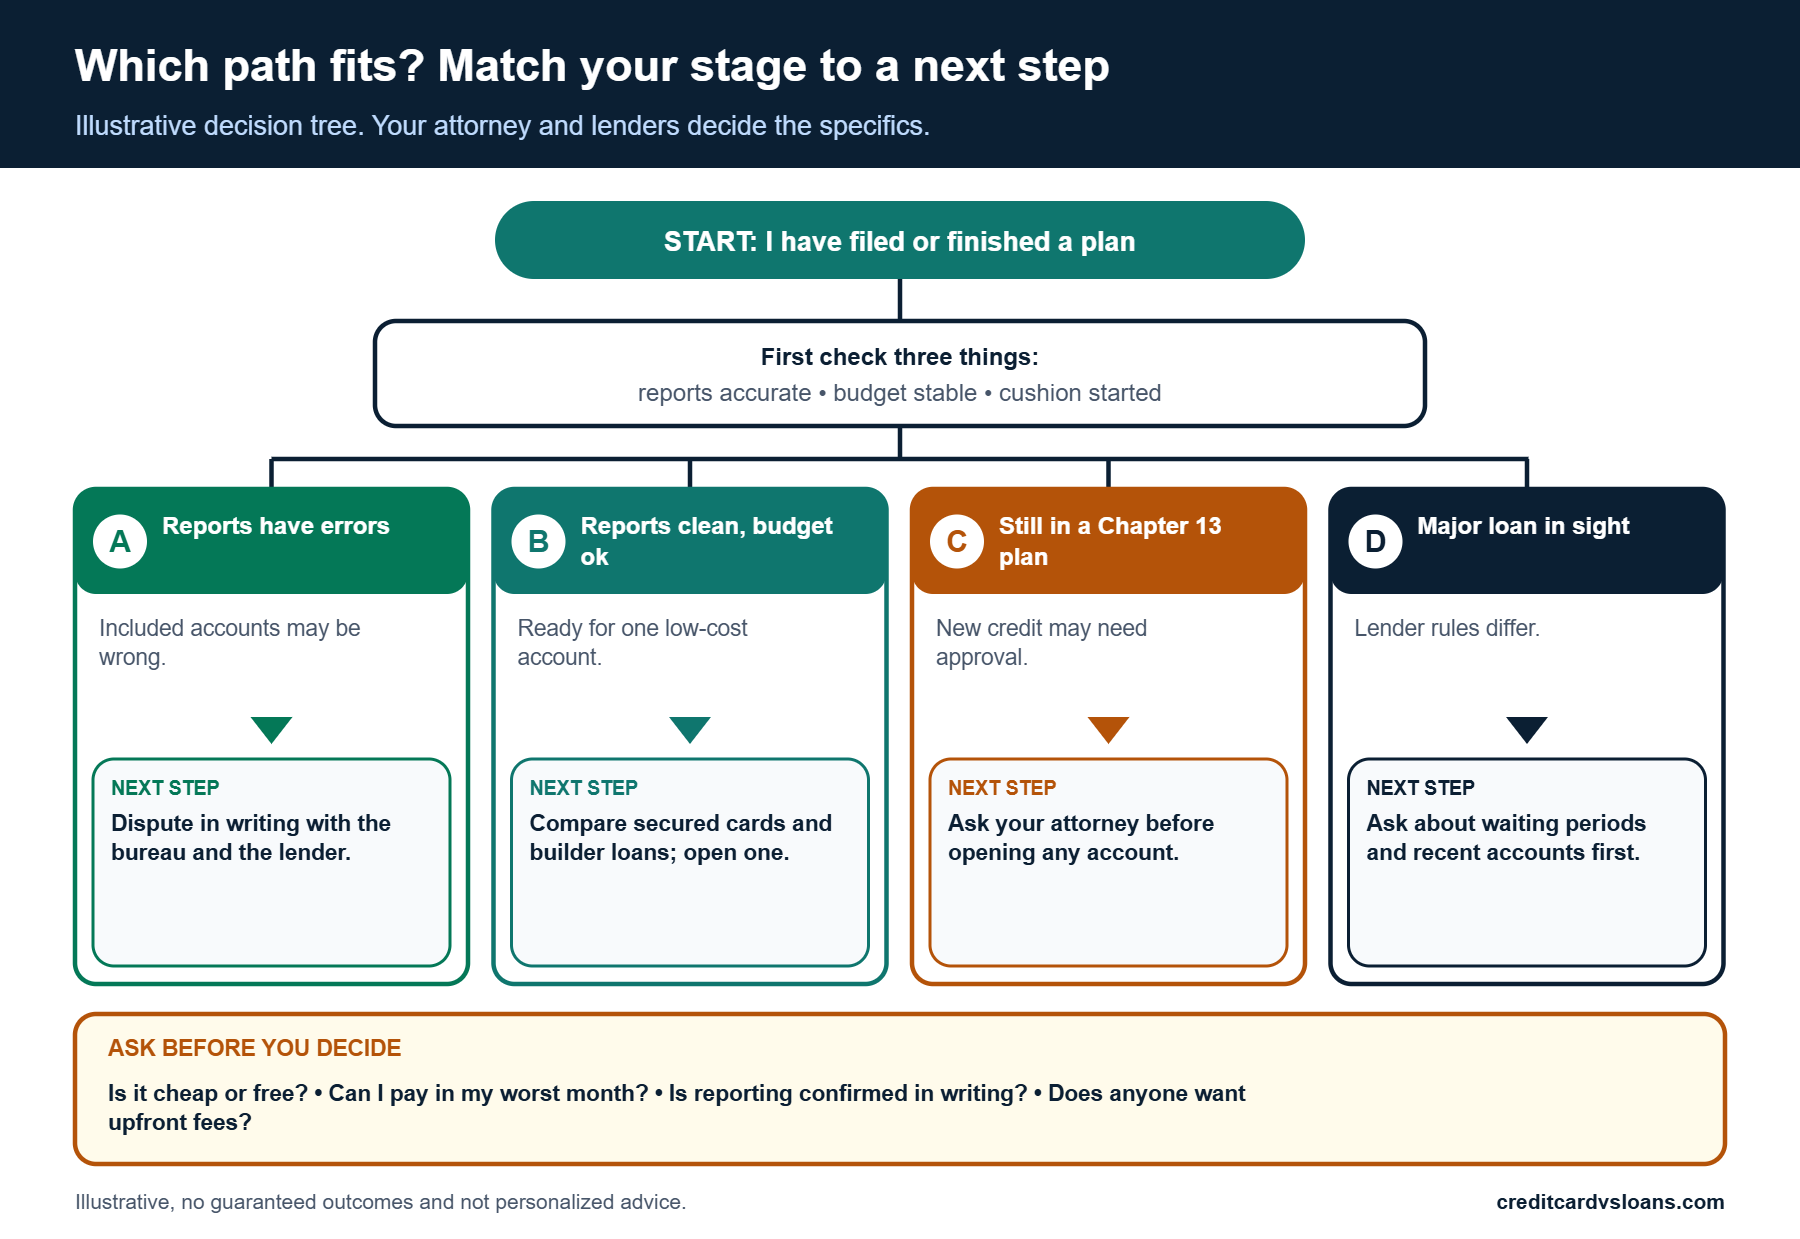
Decision checklist and next steps
Putting the plan together
The decision in plain terms
To rebuild credit after bankruptcy safely, work through three tests before each move. Is it cheap or free? Can I pay it in full or on time under my worst normal month? Is it reported to the bureaus, and in writing? A move that passes all three is usually safe. A move that fails any should wait.
The tests also help you skip temptations. A fast-approval offer with fees fails the first test. A big loan with a stretched payment fails the second. A lender that will not say what it reports fails the third.
What patience looks like in practice
Patience here is not passive. It is a quiet monthly routine: pay on time, keep balances low, check reports at set points and say no to offers that do not pass the tests. Over time, the accurate positive entries accumulate while the bankruptcy ages toward the end of its reporting period.
That is the whole mechanism. Everything else is detail.
Verify your reports, stabilize your budget, add one low-cost reporting account, and pay it on time for years. Skip anyone who promises to erase an accurate bankruptcy.
Your next steps
A step-by-step list
- Get your reports from AnnualCreditReport.com and mark every error or unfamiliar item.
- Send written disputes to the bureau and the furnisher, with copies of supporting documents.
- Write a bare-bones budget and start a small emergency cushion.
- Compare one or two secured cards or credit-builder loans on fees, deposit terms and bureau reporting.
- Open one account, set autopay to pay in full, and keep utilization low.
- Check your reports a month or two later, then at about six months and a year.
- Before any major loan, ask the lender about post-bankruptcy requirements and how recent accounts will be viewed.
For the pitfalls around loans and debt relief offers, read our guide to predatory lending warning signs, and for the mechanics of how installment loans move scores, see our credit score impact explainer.
When to ask for help
Ask a bankruptcy attorney about discharge scope, reaffirmation and filing rules. Ask a nonprofit credit counselor about budgets and debt options. If a creditor or collector acts improperly, you can file a complaint with the CFPB or your state attorney general.
The earlier you ask, the more options you usually have. Waiting until a missed payment is already on your report narrows them.
- Should You Take Out a Personal Loan Just to Build Credit?
- How a Personal Loan Can Affect Your Credit Score
- Credit Card Debt Statute of Limitations: What It Means and What It Doesn’t
- Student Credit Cards: How to Build Credit Without Overspending
- Predatory Lending: Warning Signs in Personal Loans and Debt Relief Offers
- Fair Credit Reporting Act: 15 U.S.C. 1681c – Requirements relating to information contained in consumer reports (Reporting periods for bankruptcies and adverse items)
- myFICO: Reviving my credit after bankruptcy
- U.S. Courts: Chapter 7 – Bankruptcy Basics
- U.S. Courts: Chapter 13 – Bankruptcy Basics
- FTC: Spot the scams when fixing your credit (Jan. 7, 2026)
- CFPB: Credit Builder Loans: Ideas for financial educators and financial practitioners (July 2020)
- CFPB: How do I get and keep a good credit score?
- CFPB: How do I dispute an error on my credit report?
- CFPB: What is the difference between a credit report and a credit score?
- CFPB: What is a credit inquiry?
- myFICO: How long do hard inquiries stay on your credit report?
Last updated: October 22, 2026. Rates, fees and lender rules change; verify current terms before acting.
The information on creditcardvsloans.com is provided for general educational and informational purposes only. It is not financial, legal, tax, credit, accounting or investment advice, and reading it does not create an advisor-client, fiduciary or any other professional relationship. Nothing here is an offer, solicitation or recommendation to borrow, lend or apply for any product.
Credit scores, interest rates, fees, eligibility rules, lender policies and laws change frequently and vary by lender, location and individual circumstances. Examples, figures and scenarios are illustrative only, do not predict your results and do not guarantee approval, savings, a particular rate or a credit-score outcome. Always confirm current terms directly with the lender or issuer and read the full agreement before you apply or sign.
Although we aim for accuracy and use reputable sources, we make no representations or warranties, express or implied, about the completeness, accuracy, reliability or timeliness of the content. Content may be drafted with the assistance of automated tools, so errors or omissions may still occur. Links to third-party sites are provided for convenience; we don’t control and aren’t responsible for their content.
To the fullest extent permitted by law, creditcardvsloans.com and its owners, editors, authors, contributors and affiliates disclaim all liability for any loss, damage or expense arising directly or indirectly from your use of, or reliance on, this content. Before making financial decisions, consult a licensed professional, such as a qualified financial advisor, attorney, tax professional or nonprofit credit counselor, who can consider your complete situation.