How to finance professional licensing starts with a different question than most borrowing guides ask: how much of the cost can someone else pay, and how soon will the license start paying you back? The answer usually runs in this order: employer or program money first, your own cash flow second, and borrowing last, in the smallest amount that keeps the exam date on your calendar.
Licensing costs are unusual because they arrive before the income they unlock. You may owe an exam fee, an application fee, a background check, prep materials and travel in the same few weeks, often while you are between jobs or early in a new career. A card or loan can bridge that gap, but the right choice depends on how certain the payoff is.
This guide walks through the cost components, the funding that may exist before you borrow, the borrowing options and what they can cost, and the risks that are specific to licensing, such as retake fees and processing delays. If you are comparing a holiday or other seasonal expense with a work cost, our guide to financing holiday expenses step by step uses the same cheapest-first logic on a different bill.
- Fees, exam rules and renewal requirements vary by profession and by state or licensing board, so start with your board’s current fee schedule, not an average.
- Check for money that is not a loan: employer reimbursement, workforce programs through your local American Job Center, military spouse relicensing reimbursement and board or provider payment plans.
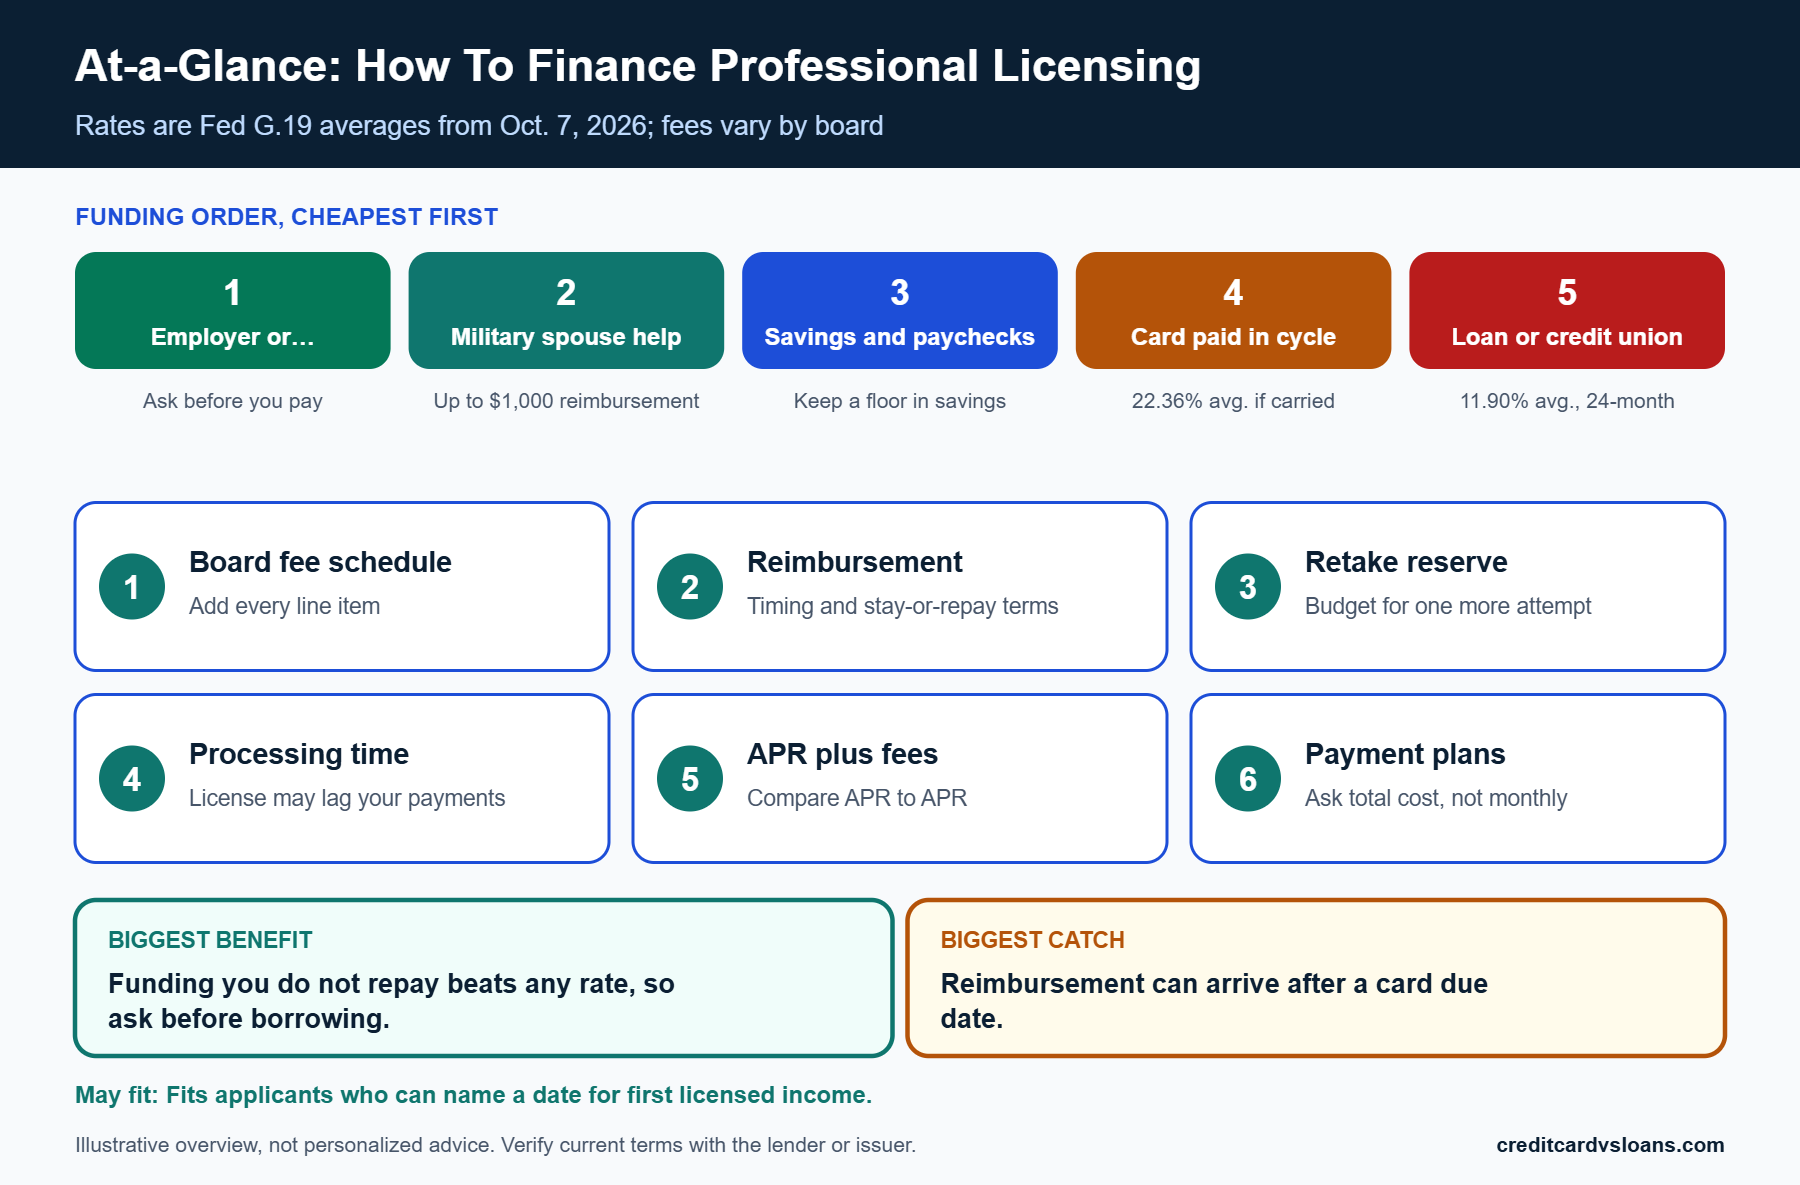
- As of the Federal Reserve’s G.19 release of Oct. 7, 2026, card accounts assessed interest averaged 22.36% (August 2026, preliminary) and 24-month bank personal loans averaged 11.90%.
- A small balance cleared quickly on a card you already have often costs less than a new loan, because there is no origination fee and no new application.
- Build in the cost of a possible retake and the time between passing and your first licensed paycheck before choosing a repayment term.
Rate figures are dated to the Federal Reserve’s G.19 release of Oct. 7, 2026. Licensing fees change often and differ by board, so the dollar amounts in the examples below are hypothetical illustrations, not fee schedules.
Table of contents
How to Finance Professional Licensing: The Short Answer
The order that usually costs least
Money you do not repay first
Reimbursement and program funding come before any loan, because every dollar you do not borrow costs nothing in interest. Ask your employer whether licensing, exam and renewal fees are reimbursed, and whether reimbursement comes after you pass or is paid up front. Check whether your local American Job Center can point you to training or support funds in your area.
The CareerOneStop site, run by the U.S. Department of Labor, lists several sources of money for training, including veterans’ education benefits, WIOA programs for certain dislocated workers, SNAP Employment and Training, federal grants and loans through the FAFSA, and scholarships. It notes that services vary by state and does not mention license or exam fees specifically, so ask your program provider or the American Job Center whether a given fee is covered.
Then your cash flow, then the smallest loan
After outside funding, cover what you can from savings and the next few paychecks. Whatever is left is the amount to finance, and that number is usually smaller than the total cost of the license. Small balances are where an existing card, paid down quickly, tends to beat a new loan, since a personal loan can carry an origination fee that is large relative to the amount.
If the leftover is larger or the payoff will take many months, compare a fixed-rate loan or a promotional card on total cost. Our side-by-side comparison of borrowing options explains how to read those offers against each other.
Why licensing is a special case
The income comes after the spending
With many expenses, you borrow and then repay from a steady paycheck. With a license, the fee often comes first and the higher pay, or any pay at all, comes later, after you pass, receive the license and find or start the work. That gap is the main reason to keep the borrowed amount small and the repayment plan conservative.
Plan for the payments to start before the raise does. If the first payment is due in thirty days and the license takes ninety days to process, the arithmetic does not work unless another income source covers it.
A pass is not guaranteed
Exams can be failed, applications can be returned for missing documents and boards can take weeks to issue licenses. Any plan that assumes a pass on the first try with immediate licensure is a plan with no margin.
The safer approach is to price the process as if one extra fee or one extra month might occur, and to avoid borrowing for amounts you could not repay if the payoff were delayed. This is not pessimism; it is the same buffer logic that applies to any plan with a hard deadline.
What a License Really Costs Beyond the Application Fee
The line items to price
One-time costs: exam, application and background checks
Most licenses involve an application fee paid to the board, an exam fee paid to the board or a testing vendor, and sometimes fingerprinting or a background check. Each may be charged separately, and some are charged again if you retake the exam or reapply.
Get the board’s own fee schedule and add each line. Do not rely on an article’s average, since fees differ by profession and by state. The total on the board’s page is the cost you will actually face, and you may find that parts of it are due at different times.
Preparation: courses, materials and time off
Prep courses, study guides, practice exams and test-site travel are often the largest costs outside the board’s fees. Unpaid time off to study or sit for the exam is a cost too, even though it does not show up on a bill.
Before paying for a prep package, ask what is included, whether a pass guarantee has conditions, and whether the provider offers its own payment plan. Compare any financing the provider offers with a card or credit union loan on APR and fees, since in-house financing can have terms that differ from what the marketing page suggests.
Costs that recur
Renewal, continuing education and insurance
Licenses usually need renewing, often with continuing education requirements. Some professions also require liability insurance or bonding. These costs do not belong in the starting loan, but they belong in your plan for the first year, since they affect how much room you have for repayments.
List the renewal date, the fee and the continuing education hours required, and compare that to your budget for the next two years. A license you cannot afford to keep is a poor use of borrowed money.
Moving between states
If you already hold a license and move, your new state may require a new application, reciprocity paperwork or additional testing. Military One Source notes that many states offer expedited applications, temporary licenses or reciprocity for military spouses, which can reduce or eliminate relicensing, and the Department of Labor keeps a Military Spouse License Recognition Map of state rules.
For anyone, the first step in a move is checking whether your existing license transfers before you pay for a new one. The answer can change a $1,000 problem into a $100 one.
| Line item (illustrative amount) | Who may cover it | Main advantage | Main drawback | Primary cost driver |
|---|---|---|---|---|
| Exam fee ($400) | Employer, workforce program or you | Often reimbursed after a pass | May need to be paid first | Retake fees |
| Application fee ($250) | Employer, board payment plan or you | Fixed and known | Usually due at filing | Reapplication if incomplete |
| Prep course and materials ($400) | Employer, provider payment plan or you | Can be spread out | In-house financing terms vary | Provider financing APR and fees |
| Background check and fingerprints ($150) | You, or employer if onboarding | Small and one-time | Easy to forget | Repeat checks if delayed |
| Renewal and continuing education | Employer or you | Predictable schedule | Recurring every cycle | Course costs and late fees |
Money You May Not Have to Borrow
Employer and program funding
Employer reimbursement and how it really works
Many employers cover licensing costs for roles that require them, either by paying the board directly or by reimbursing you afterward. Ask for the policy in writing, and find out three things: which fees are covered, whether you need approval before you pay, and whether you must stay with the company for a set time or repay the amount if you leave.
Reimbursement after the fact still leaves a gap in your cash flow. If you pay the exam fee on a card you can clear in full when the reimbursement arrives, the borrowing may cost nothing. If the reimbursement takes longer than your billing cycle, you may pay interest in the meantime, so ask how long it takes.
Workforce programs and training funds
Local American Job Centers can explain training funds, including WIOA-funded programs for eligible workers. The CareerOneStop page on paying for training says services under programs like WIOA Dislocated Worker vary by state, and recommends checking with the training provider or your local center on what a specific program covers.
These programs often have eligibility rules and approval steps that take time, so start early. A program that pays for the prep course but not the board’s exam fee, for example, still leaves you needing a plan for the second cost.
Special programs and payment plans
Military spouse relicensing help
According to Military One Source, under the 2018 National Defense Authorization Act each service branch can reimburse military spouses up to $1,000 for relicensure and certification costs after a move across state lines, including moves from overseas to the U.S., with the application process set by the sponsoring branch. It also notes that if relicensing takes a long time or costs a lot, a spouse may qualify for unemployment compensation, so ask the state employment office.
If this applies to you, apply before you pay anything out of pocket, since requirements for reimbursement can include documentation of the expense. Keep every receipt and the board’s confirmation of fees paid.
Board and provider payment plans
Some licensing boards and prep providers allow fees to be split or deferred, and some offer fee waivers for low-income applicants or certain applicant groups. Availability depends entirely on the board and the profession, so ask directly and read the board’s published policies.
A provider’s payment plan is not automatically the cheapest option. Ask for the total amount you will pay, any interest or fees, and what happens if you miss a payment, then compare that with a card you already have. The CFPB’s guidance on medical payment plans makes the same point for any provider financing: ask about the APR, when interest starts and what fees apply before agreeing.
Borrowing Options for Licensing Costs: Compared on Cost and Risk
The main borrowing choices
A card you already hold
For amounts you can pay down within a month or two, an existing card is usually the least expensive way to bridge a licensing fee. The CFPB notes that on most cards you can avoid interest on purchases by paying your balance in full each month by the due date. There is no new application and no origination fee, and a card can also give you stronger dispute rights if a vendor does not deliver than a debit payment would.
If the payoff will take several months, the rate matters. The Federal Reserve’s G.19 release of Oct. 7, 2026 reported an average of 22.36% on card accounts assessed interest in August 2026 (preliminary), which makes a long payoff on a card the most expensive of the common options.
A 0% purchase offer
If your credit qualifies and the fee is large enough to be worth an application, a card with a 0% introductory APR on purchases can bridge a few months at little cost. The catch is the ending: the CFPB explains that under a deferred-interest promotion, a balance remaining at the end of the period, or a minimum payment more than 60 days late, can lead to interest being charged for each month back to the original purchase date.
Apply only if you are likely to be approved and certain about the payoff date. If your licensing timeline could slip, a promotional window that ends before your first licensed paycheck is a poor match.
A personal loan or credit union loan
A personal loan gives you a fixed payment and a set number of months. The Federal Reserve’s G.19 release of Oct. 7, 2026 reported an average 24-month personal loan rate of 11.90% at commercial banks. The CFPB notes that fees on personal installment loans can include origination fees, documentation fees, optional insurance and late fees, so compare the APR, which includes the lender’s additional fees, across offers.
Federal credit unions may offer payday alternative loans of up to $2,000 for one to twelve months with an application fee capped at $20 under National Credit Union Administration rules, though not every credit union offers them and membership generally applies. Ask yours directly.
What it can cost (hypothetical)
A $1,200 licensing bill
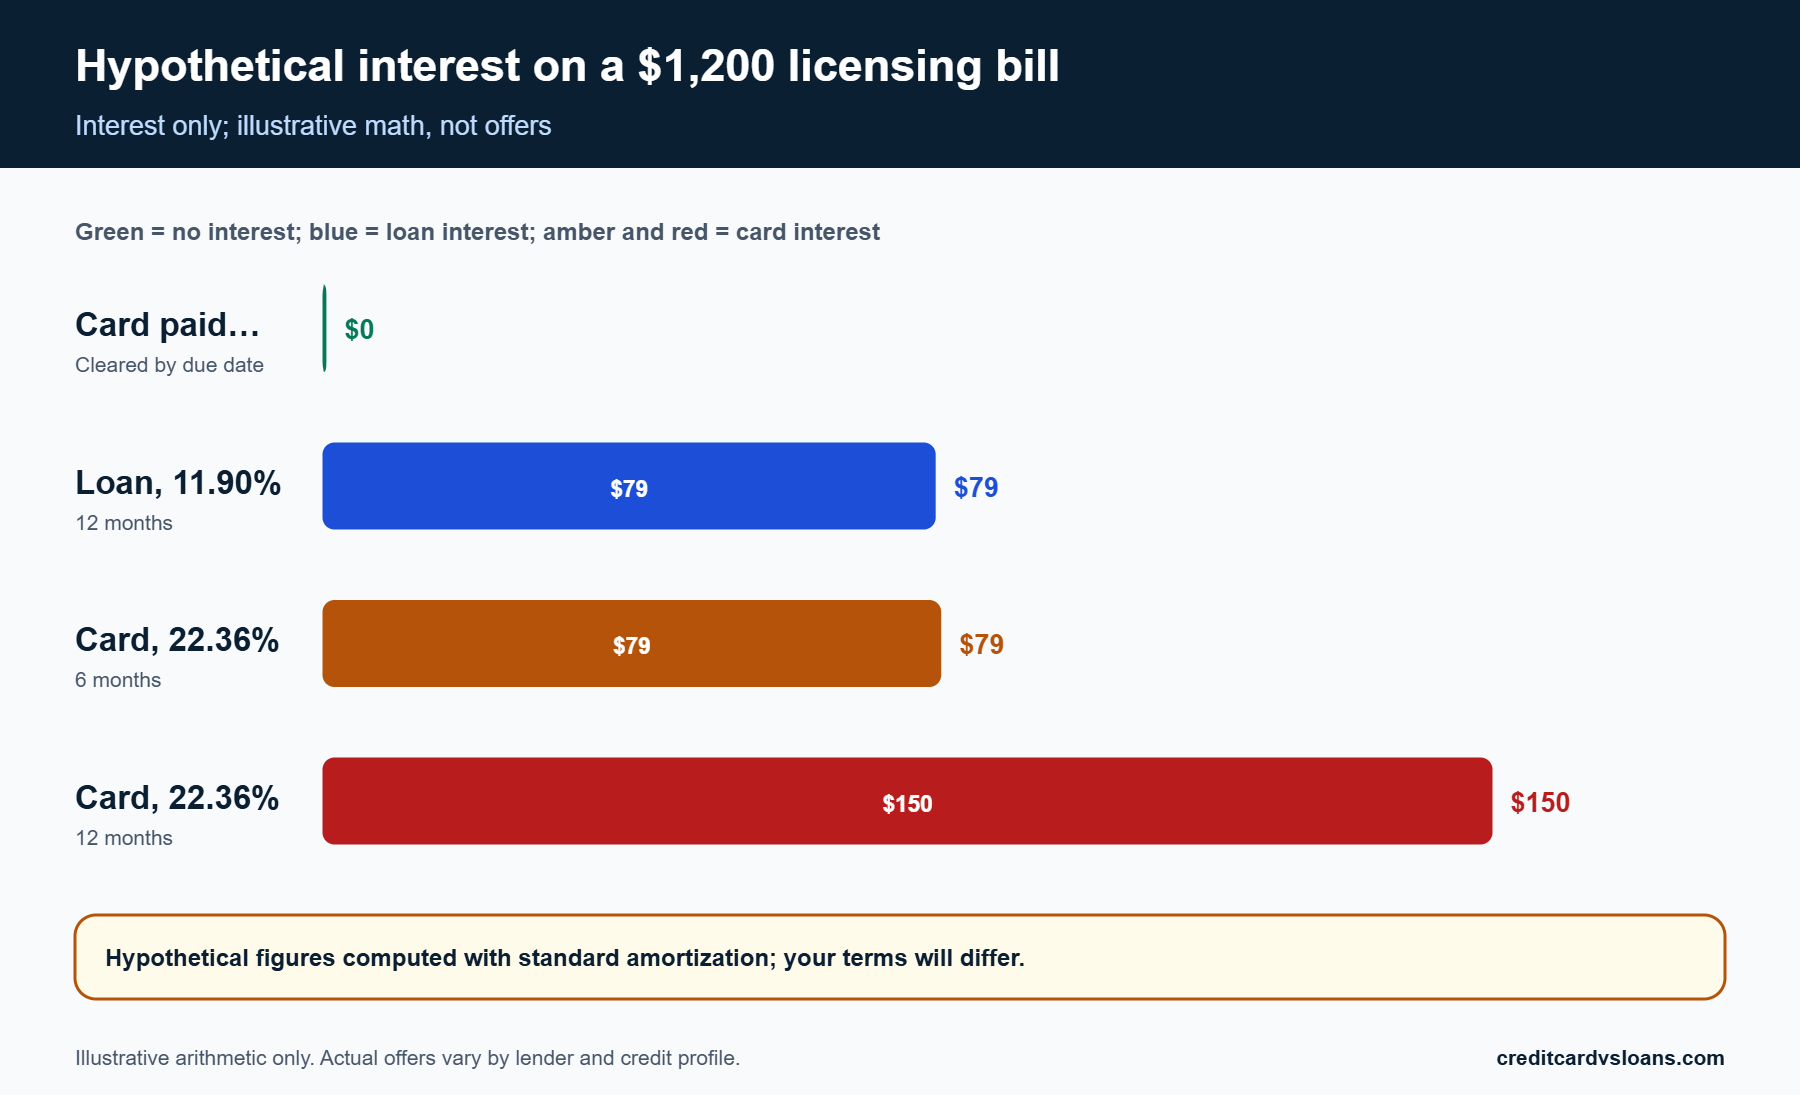
Take a hypothetical $1,200 total: a $400 exam fee, a $250 application fee, $400 in prep materials and a $150 background check. These are illustrative amounts, not any board’s fees, and the interest math uses standard amortization.
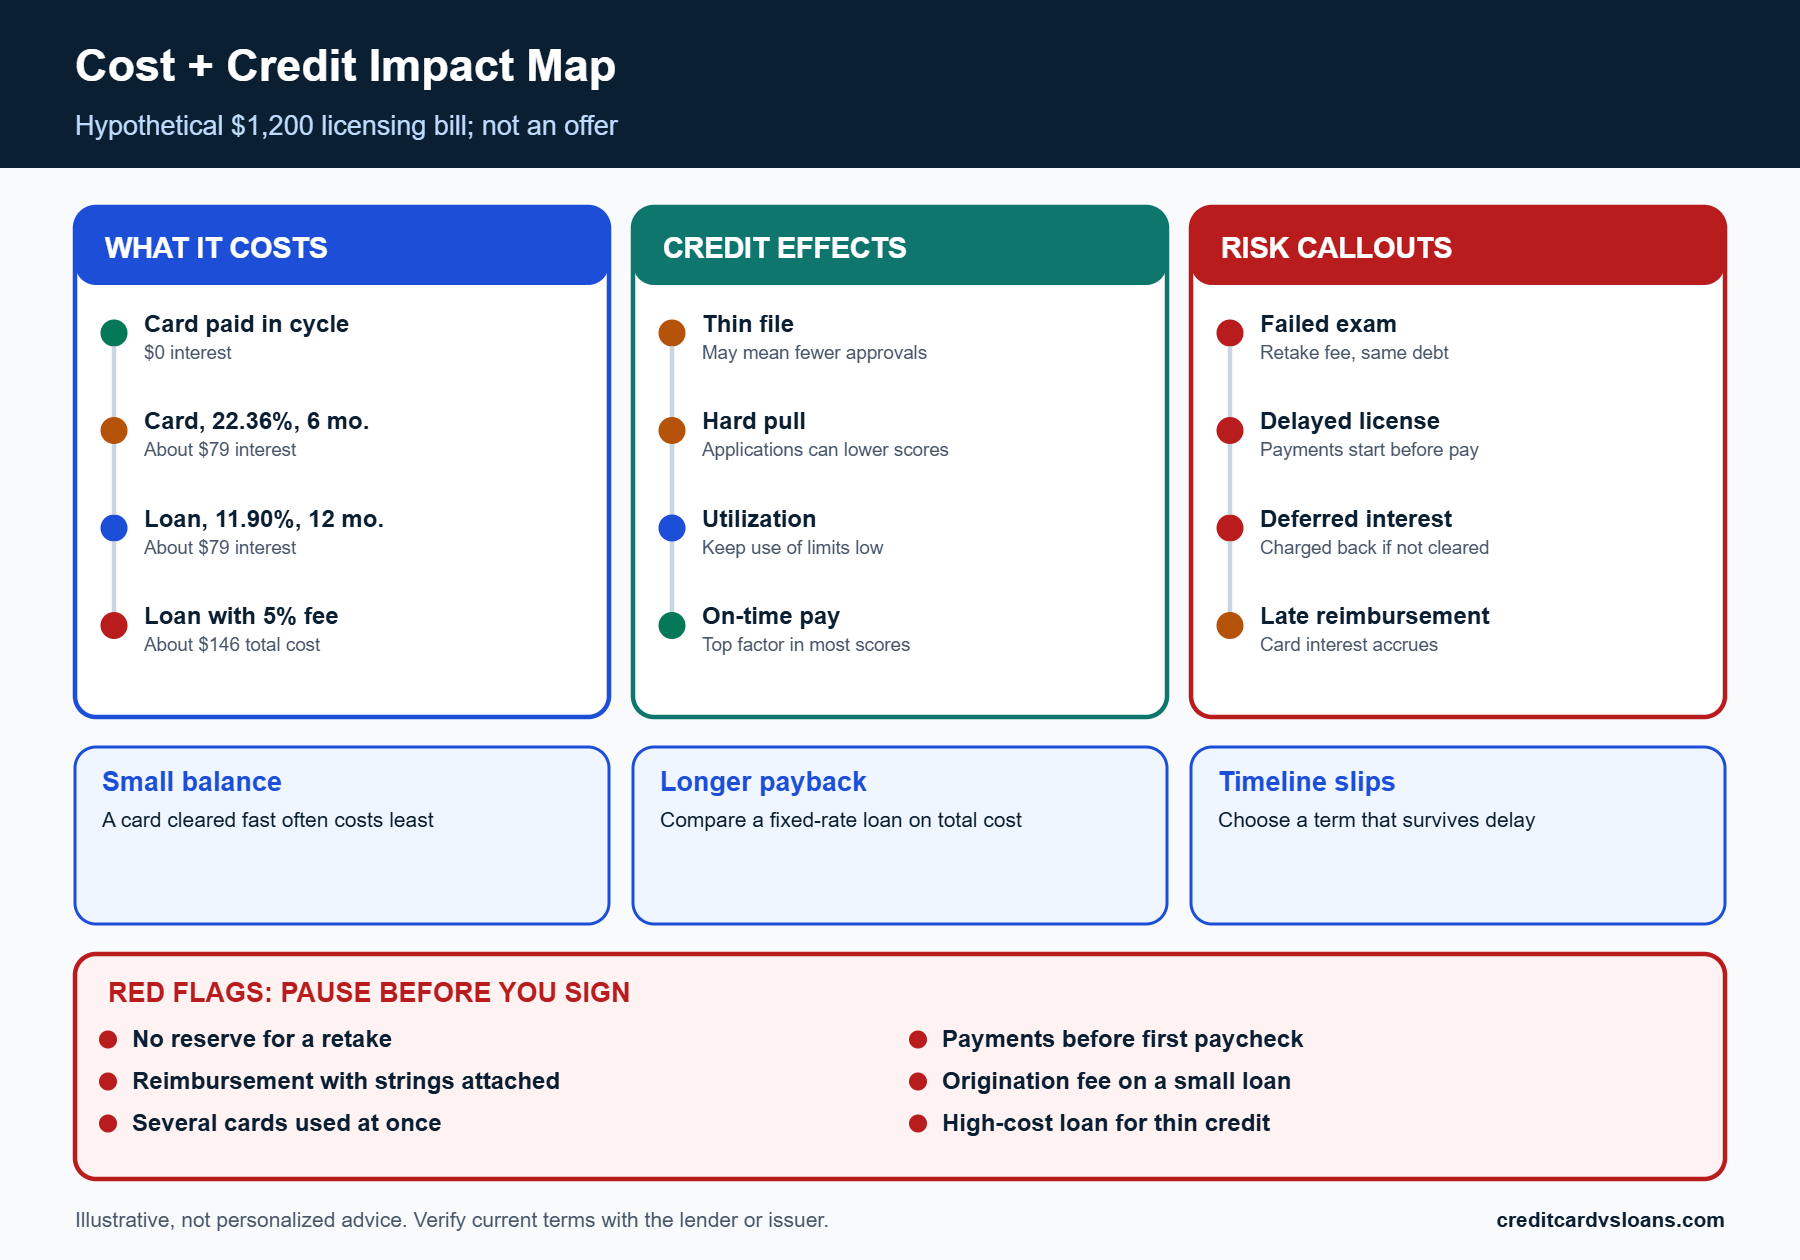
At 22.36% on a card, repaying $1,200 over six months costs about $79 in interest with payments near $213, and over twelve months costs about $150 with payments near $113. At 11.90% on a loan with no fee, twelve months costs about $79 with payments near $107. If the loan had a hypothetical 5% origination fee and you borrowed about $1,263 to net $1,200, the twelve-month cost would be roughly $146, which is why comparing APR matters.
| Option (illustrative) | APR or rate type | Repayment pattern | Monthly payment | Interest and fees | Credit and risk notes |
|---|---|---|---|---|---|
| Existing card, paid in cycle | No interest if paid in full | One payment | $1,200 | $0 | No new inquiry; needs cash at the due date |
| Card, carried 6 months | 22.36% (Fed average) | 6 equal payments | About $213 | About $79 | Utilization rises while carried |
| Loan, no fee | 11.90% (Fed 24-month average) | 12 equal payments | About $107 | About $79 | Hard pull; fixed end date |
| Loan, 5% fee | 11.90% on about $1,263 | 12 equal payments | About $112 | About $146 | Fee withheld from proceeds |
| Card, carried 12 months | 22.36% (Fed average) | 12 equal payments | About $113 | About $150 | Cost nearly doubles with time |
When a small loan is not worth it
On a balance this size, a loan with a fixed fee can cost as much as a card paid down quickly, and some lenders have minimum loan amounts above what a licensing fee requires. If your only choice is a loan with a high fee, consider whether a payment plan from the board or provider would cost less.
The reverse is also true. If you need a year to repay, a fixed-rate loan can cost less than a card at the average rate. The best choice depends on your timeline, your credit and the exact terms in your offer.
Timing: Matching Payments to When You Start Earning
Building the timeline
Map the dates from application to first licensed paycheck
Write the sequence on one page: when each fee is due, the exam date, how long the board takes to issue the license after you pass, and when you expect to be able to work under it. Then place your loan or card payments against it.
The common mistake is picking a repayment term by what looks affordable today and ignoring that licensure may take weeks or months to finish. If the first payment is due before the license can generate income, you need another source for that payment, or a payment structure that starts later.
Choose a term that survives a delay
A twelve-month fixed-rate loan has a smaller total cost than a twenty-four-month loan at the same rate, but a higher monthly payment. On the hypothetical $1,200 at 11.90%, a 24-month term costs about $154 in interest with payments near $56, compared with about $79 and $107 for twelve months.
A longer term can protect your cash flow during a delay, at a higher cost. If you take a longer term, check for a prepayment penalty first, and plan to pay extra once the license produces income. The CFPB advises reading the loan disclosures for fees before you agree.
Cash-flow protection
Keep a floor under your savings
Spending all your savings on a license leaves nothing for the gap between passing and getting paid. Keep a floor in savings for essentials, and finance a little more rather than cutting the floor to nothing.
The Federal Reserve’s report on household economic well-being in 2025 found that 63% of adults would cover a hypothetical $400 emergency expense with cash or its equivalent. If you are among those with limited cushion, protecting it is part of the financing plan.
Ask about timing flexibility
Boards sometimes have filing windows, exam scheduling blocks and deadlines for submitting documents. Paying fees in a different order, or choosing a later exam date, can let you spread costs over two billing cycles without borrowing.
If your employer plans to reimburse you, ask for the payment date. A reimbursement that arrives after your card due date may mean a month of interest on a balance that would otherwise be interest-free, so time the charge right after your statement closes.
Credit and Approval When You Are Early in Your Career
How lenders will see you
Thin credit files and limited history
Career changers and recent graduates often have a thin credit file, meaning few accounts or a short history. The CFPB says that length of credit history matters because scores rely largely on how you have managed accounts over time. A short file does not mean a bad one, but it can mean fewer approvals and higher rates.
If your file is thin, look at what you already have. A card paid in full each month builds history without interest. A credit union may weigh more than your score, and a cosigner can help, though a cosigner takes on legal responsibility for the debt and the risk to that relationship is real.
Hard pulls and rate shopping
The CFPB notes that when you apply for a credit card or line of credit, the issuer reviews your credit report and the application can lower your score. Prequalification tools often use a soft pull and can show estimated terms, which makes them a better first step than formal applications.
Apply for only what you need. The CFPB cautions that applying for many new accounts in a short period can make you look like you are facing financial setbacks, which is the opposite of the impression you want to give a lender while you are also paying for a license.
If approval is uncertain
Options that do not depend on a high score
If you are not approved for the cheapest products, look at what does not need strong credit: employer reimbursement, program funding, board or provider payment plans, a credit union small loan, or a smaller scope, such as paying for the exam now and the prep materials later.
Splitting the license into stages can turn one large, hard-to-finance bill into two smaller ones that fit existing resources.
Be careful with high-cost products
If a lender approves you quickly at a very high rate, treat the speed as a warning rather than a relief. High-cost loans can turn a few hundred dollars of fees into a much larger debt, and the cost of a retake or delay compounds the problem.
Our guide to personal loans for bad credit explains the cost structure and safer alternatives before you sign anything that is aimed at borrowers with limited credit.
Risks That Are Specific to Licensing Debt
When the license does not arrive on schedule
Failed exams and retake fees
If you fail, you may owe another exam fee and may have to wait before you can retest. A plan that financed only the first attempt now needs additional money, and payments on the original debt continue meanwhile.
Price the first attempt and set aside a small reserve for a retake, even if you expect to pass. If the reserve is not used, it can go toward paying down the debt faster.
Processing delays and returned applications
A missing document or a background check that takes longer than expected can add weeks. During that time, the loan payment continues and any 0% window runs down.
Submit complete applications early, track the status, and keep a copy of every submitted document. If you are on a promotional card, build extra months into your payoff plan rather than aiming for the last day.
Debt before income
The interest clock runs before the raise starts
Each month between taking on debt and earning from the license is a month of payments with no extra income to fund them. That is the cost of timing, and it is separate from the interest rate.
To manage it, borrow the smallest amount that works, choose the lowest-fee structure and revisit the plan monthly. If the license does not lead to the income you expected, you want the debt to be small enough to carry.
Using the card for everything
It is tempting to put application, prep, travel and even living costs on one card. A single large balance pushes your utilization up, and the CFPB advises keeping your use of credit at no more than 30 percent of your total credit limit. A high balance can also be harder to pay down than several small ones.
Track licensing costs in one list so you can see how much of the card balance is for the license and how much is not. If the total exceeds what you planned, pause and reprice before charging more.
Scenarios: Which Funding Path Fits?
Four hypothetical situations
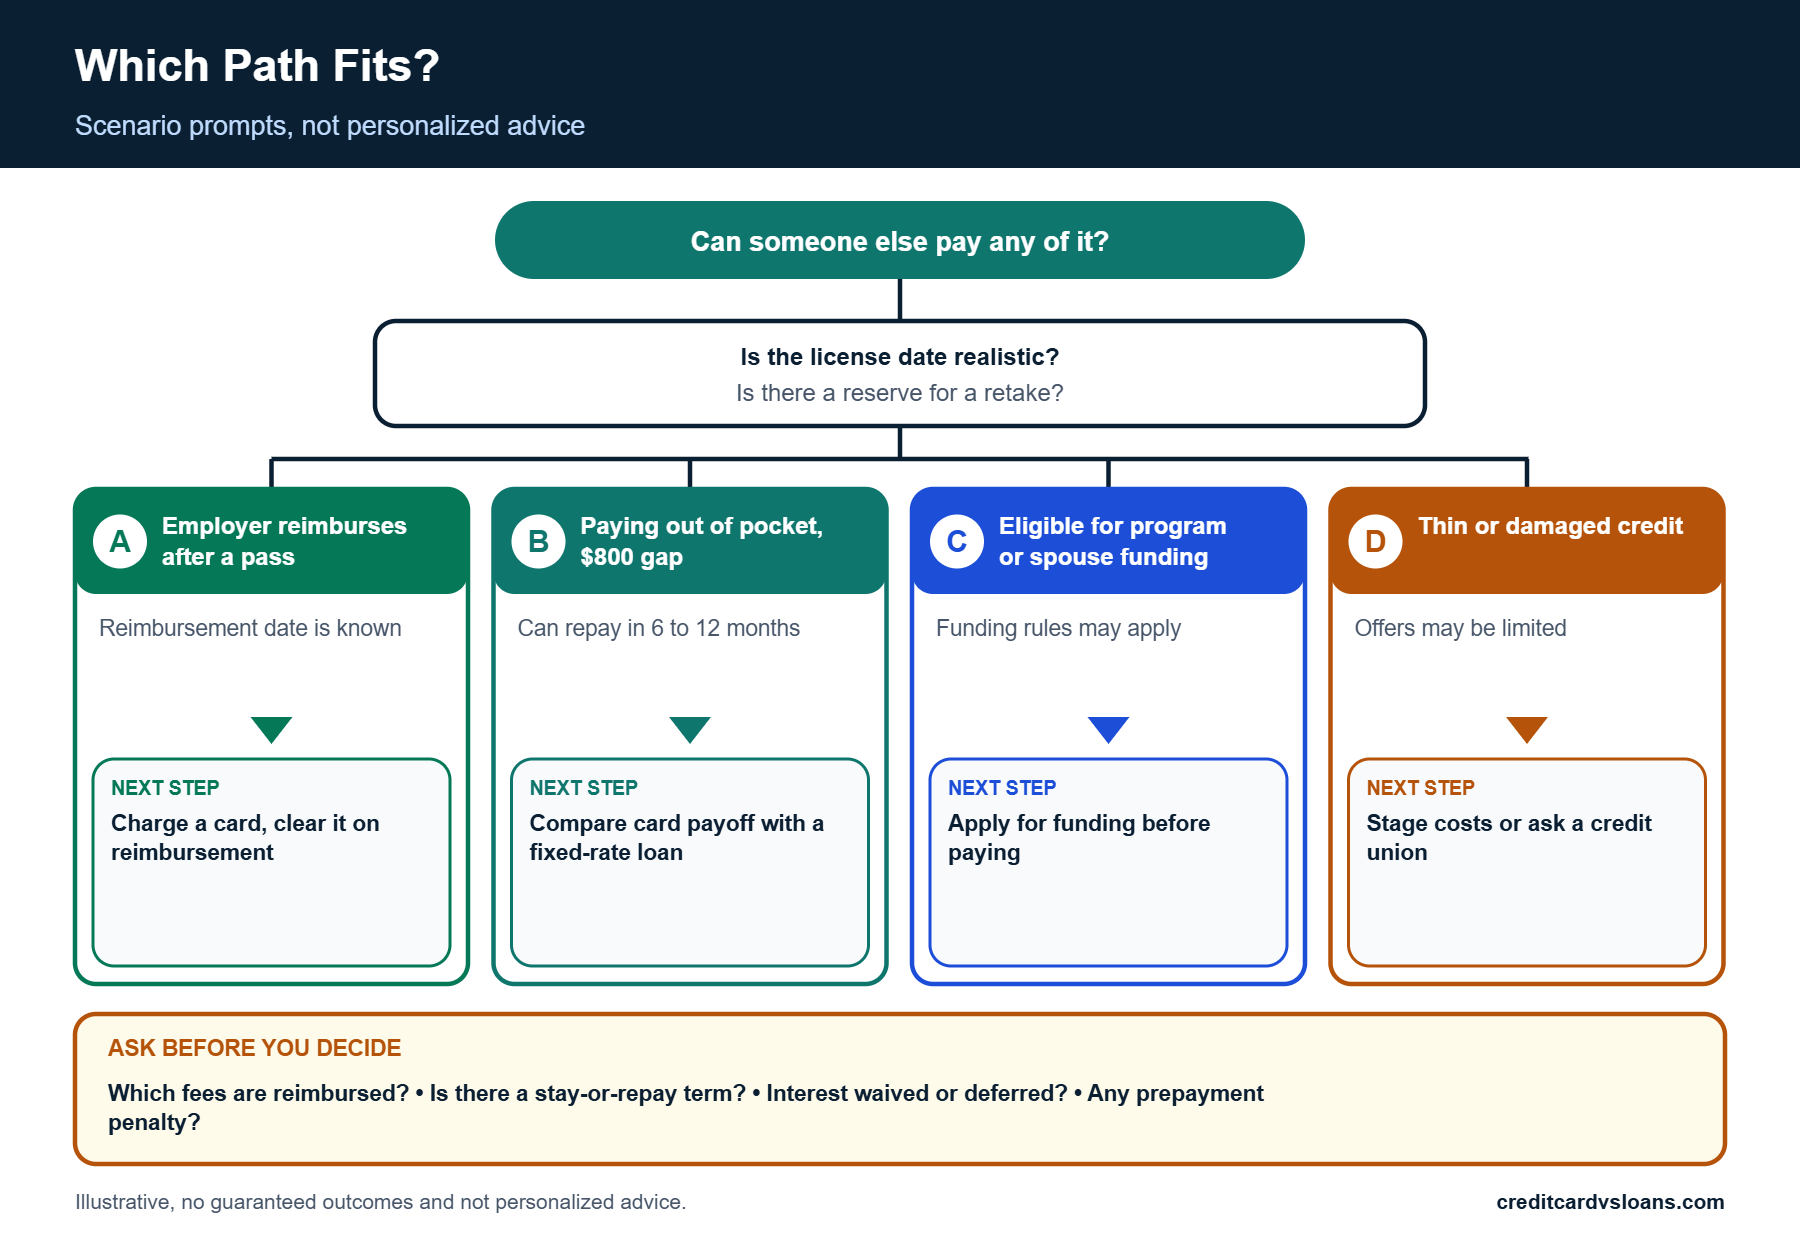
Employer reimburses after you pass
A new hire is told the company reimburses the exam and application fees after a pass, about 45 days later. The fees total $650. Paying on an existing card right after a statement closes, then clearing the balance with the reimbursement before the due date, can cost nothing in interest. The risk is a delayed reimbursement, so the plan needs a way to pay the card if the money is late. For a similar reimbursement-style cash gap in another setting, see how to finance a veterinary emergency, where timing of payments also drives the cost.
The question to ask before charging: does the reimbursement policy require staying with the employer for a period, and what happens if you leave?
Career changer paying out of pocket
A career changer has no employer help and needs $1,200 for the full process. Savings cover $400, and the rest is a gap of $800. With a payment of about $140 a month, the household can clear the gap in six months on an existing card at the average rate for about $53 in interest, or choose a loan that gives a longer, lower payment.
If six months is realistic, the card may be the lowest-cost route. If a delay in licensure is likely, a twelve-month loan with no fee costs about $52 in interest on $800 and gives breathing room, at a similar total cost. Each option still depends on the offer received.
Military spouse relicensing after a move
A military spouse moving to a new state may qualify for reimbursement of up to $1,000 for relicensure costs through the sponsoring service branch, and may also benefit from expedited applications or reciprocity. The financing question is only about the gap before reimbursement arrives.
Applying for reimbursement right away, keeping receipts and using a card paid off after the reimbursement lands is a common-sense path. A longer-term loan is rarely the right tool for a cost that is expected to be reimbursed.
Thin credit, limited options
A recent graduate with a thin credit file may find card offers limited. A smaller first step, such as paying the exam fee now and the prep materials after the first paycheck, or asking a credit union about a small loan, may be the better plan.
This approach trades speed for lower cost. If the exam date is flexible, it can be worth it. If the date is fixed, ask the board or provider about payment plans before turning to high-cost credit.
Reading the decision matrix
What the matrix does and does not say
The table below turns the scenarios into a quick lookup for the first option to investigate. It cannot know your credit, your board’s rules or your offers, so it works as a starting point for questions, not as a recommendation.
Using the matrix with your own numbers
Replace the scenario labels with your actual situation, then fill in the blanks: the total from your board’s fee schedule, the amount covered by outside funding, the gap, and the number of months you can realistically repay. Once you have those four numbers, the row that matches you becomes the first option to price.
Price that option and one alternative on total cost using the exact payment schedule you would follow. If the two come within a few dollars of each other, choose the one with the more forgiving terms, such as no prepayment penalty and a later first payment, since licensing timelines tend to slip.
| Borrower scenario | Option to investigate first | Why | What to confirm | When to avoid it |
|---|---|---|---|---|
| Employer will reimburse | Existing card, cleared on reimbursement | No interest if the balance is cleared by the due date | Reimbursement timing and any stay-or-repay terms | If reimbursement could arrive after the due date |
| Small gap, can repay in 3 to 6 months | Existing card or board payment plan | No new application or fee | Grace period and plan terms | If you already carry a balance |
| Gap needing 12 months | Fixed-rate or credit union loan | Set payment and payoff date | APR with fees, prepayment terms | If the fee is large for the amount |
| Eligible for program or military spouse funding | Apply for funding first | Money you do not repay | Eligibility, documentation, timing | Do not pay out of pocket before confirming rules |
| Thin or damaged credit | Stage the costs or ask a credit union | Smaller steps fit existing resources | Membership, fees, flexibility of dates | High-cost loans that make a delay costly |
Checklist Before You Pay for Anything
Before you apply or borrow
Costs and funding
- The board’s current fee schedule, with every line added up.
- Written employer policy on reimbursement and any stay-or-repay terms.
- A call to your local American Job Center about training funds.
- Eligibility for military spouse reimbursement, if relevant.
- Any board or provider payment plan, with its total cost.
Terms to confirm in writing
For any card or loan, write down the APR with fees, the term, the payment, the due date and any prepayment penalty. For a promotion, confirm whether interest is waived or deferred and what happens if the balance is not cleared on time.
Compare at least two offers on a total-cost basis, and use soft-pull prequalification where it is offered before submitting a formal application.
After you pay
Protect the plan
- Autopay for at least the planned amount.
- A calendar reminder for the reimbursement date and any promotion end date.
- A reserve for a possible retake.
- A monthly check on the balance and the license status.
Document everything
Keep receipts, confirmation emails and the board’s records. They matter for employer reimbursement, program funding, military spouse reimbursement and, in some cases, tax questions. Tax treatment of licensing costs depends on whether you are an employee or self-employed and on current rules, so ask a tax professional or check IRS guidance for your situation.
When the license arrives, update your plan: redirect the extra income to the remaining balance first.
Common Questions About Paying for a License
Funding questions
Can education aid cover exam and application fees?
CareerOneStop lists federal grants and loans through the FAFSA among sources of money for training, but aid is generally tied to an eligible program, and fees paid directly to a licensing board may not count as part of a program’s cost. Ask the financial aid office of your school or training provider what is covered before you assume anything.
If part of the cost is covered by aid, you may only need to finance what is left, which makes a smaller, lower-risk borrowing amount.
What if my employer will pay, but only after a waiting period?
Some employers reimburse only after a probationary period or after you pass. Ask for the policy in writing and plan the cash flow for the full period. If the wait is long, a card paid off on the reimbursement date is workable only if you can cover the payment on time if the reimbursement is late.
It also helps to ask whether the employer can pay the board or testing vendor directly, which removes the need for you to borrow at all.
Credit and repayment questions
Will a licensing loan make it harder to borrow later?
A new account adds a hard inquiry and a new payment, and a high card balance raises your utilization, which the CFPB says scoring models consider. If you plan to apply for a mortgage, auto loan or apartment soon, keep the licensing balance as small as possible and avoid applying for other new credit at the same time.
On-time payments on an installment loan or card help your history over time, but borrowing only to build credit is not a reason to take on a loan with fees.
Is it a good idea to pay the balance off early?
In most cases, paying early saves interest, which makes it attractive once the license starts producing income. Before you sign for a loan, ask whether any prepayment penalty applies, and choose an offer without one if the rest of the terms are similar.
On a promotional card, paying ahead of schedule is the best way to protect against deferred interest. Aim to finish with at least a month to spare.
Conclusion and Next Steps
The short version
Funding first, then the smallest bridge
To finance professional licensing at the lowest cost, look for reimbursement and program funding first, use your own cash flow second, and borrow only the remaining gap with the tool that fits your timeline. For small balances you can clear in a month or two, an existing card often costs the least. For longer paybacks, compare fixed-rate loans and promotional offers on total cost and on what happens if the license is delayed.
The step that most affects cost is the size of the borrowed amount. Everything else, including the rate, matters less on a small balance than it does on a large one.
Keep a margin for delays
Licensing timelines slip. Choose a repayment plan that still works if the exam is retaken or the license arrives a month late. Use the same logic as the cheapest-first plan in our guide to financing back-to-school costs, where timing also drives the choice.
Next steps
This week
- Get the board’s fee schedule and total every line.
- Ask your employer or program about reimbursement and funding.
- Decide how much you can pay from savings and the next two paychecks.
Before borrowing
- Prequalify with soft pulls where available and compare APR to APR.
- Write the payoff date and confirm the payment fits if the license is delayed.
- Set up autopay and reminders, and keep every receipt.
- How to Finance Holiday Expenses: Credit Cards, Loans and Lower-Cost Options
- How to Finance Back-to-School Costs: Credit Cards, Loans and Lower-Cost Options
- How to Finance a Veterinary Emergency: Credit Cards, Loans and Lower-Cost Options
- Best Way to Pay for Holiday Expenses: Compare Borrowing Options Before You Commit
- Personal Loans for Bad Credit: Costs, Risks and Safer Options
- Federal Reserve: Federal Reserve G.19 Consumer Credit, release of Oct. 7, 2026 (Credit card and 24-month personal loan rates, August 2026 (preliminary))
- Federal Reserve: Economic Well-Being of U.S. Households in 2025 (May 2026)
- CareerOneStop (U.S. Department of Labor): Find money for training
- Military OneSource (Department of War): Transferring Professional Licenses
- CFPB: I got a credit card promising no interest for a purchase if I pay in full within 12 months. How does this work?
- CFPB: Do personal installment loans have fees?
- CFPB: What should I know about medical credit cards and payment plans for medical bills? (Questions to ask about any provider payment plan)
- CFPB: How do I get and keep a good credit score?
- CFPB: When can a credit card company look at my credit reports?
- NCUA / Federal Register: Payday Alternative Loans (final rule)
Last updated: October 22, 2026. Rates, fees and lender rules change; verify current terms before acting.
The information on creditcardvsloans.com is provided for general educational and informational purposes only. It is not financial, legal, tax, credit, accounting or investment advice, and reading it does not create an advisor-client, fiduciary or any other professional relationship. Nothing here is an offer, solicitation or recommendation to borrow, lend or apply for any product.
Credit scores, interest rates, fees, eligibility rules, lender policies and laws change frequently and vary by lender, location and individual circumstances. Examples, figures and scenarios are illustrative only, do not predict your results and do not guarantee approval, savings, a particular rate or a credit-score outcome. Always confirm current terms directly with the lender or issuer and read the full agreement before you apply or sign.
Although we aim for accuracy and use reputable sources, we make no representations or warranties, express or implied, about the completeness, accuracy, reliability or timeliness of the content. Content may be drafted with the assistance of automated tools, so errors or omissions may still occur. Links to third-party sites are provided for convenience; we don’t control and aren’t responsible for their content.
To the fullest extent permitted by law, creditcardvsloans.com and its owners, editors, authors, contributors and affiliates disclaim all liability for any loss, damage or expense arising directly or indirectly from your use of, or reliance on, this content. Before making financial decisions, consult a licensed professional, such as a qualified financial advisor, attorney, tax professional or nonprofit credit counselor, who can consider your complete situation.