The debt consolidation credit score impact is not one event but a long arc. In the first weeks, a hard inquiry and a new account tend to matter most. Over the following one to three years, the payment record and the balance on the new account take over. After that, the account ages, the loan closes and the file settles into whatever habits you built along the way. No single point on that arc predicts the rest, and nobody can promise where your score will land.
This guide takes the long view. It follows a consolidation across five horizons, from the first 90 days to year five and beyond, and compares how different consolidation routes behave over those horizons. If you want the behavior-by-behavior scenarios, see what happens to your credit score after debt consolidation; for the balance transfer side of the mechanics, see how a balance transfer can affect your credit score.
All examples are hypothetical arithmetic, not predictions, and your results depend on your file and the scoring model used.
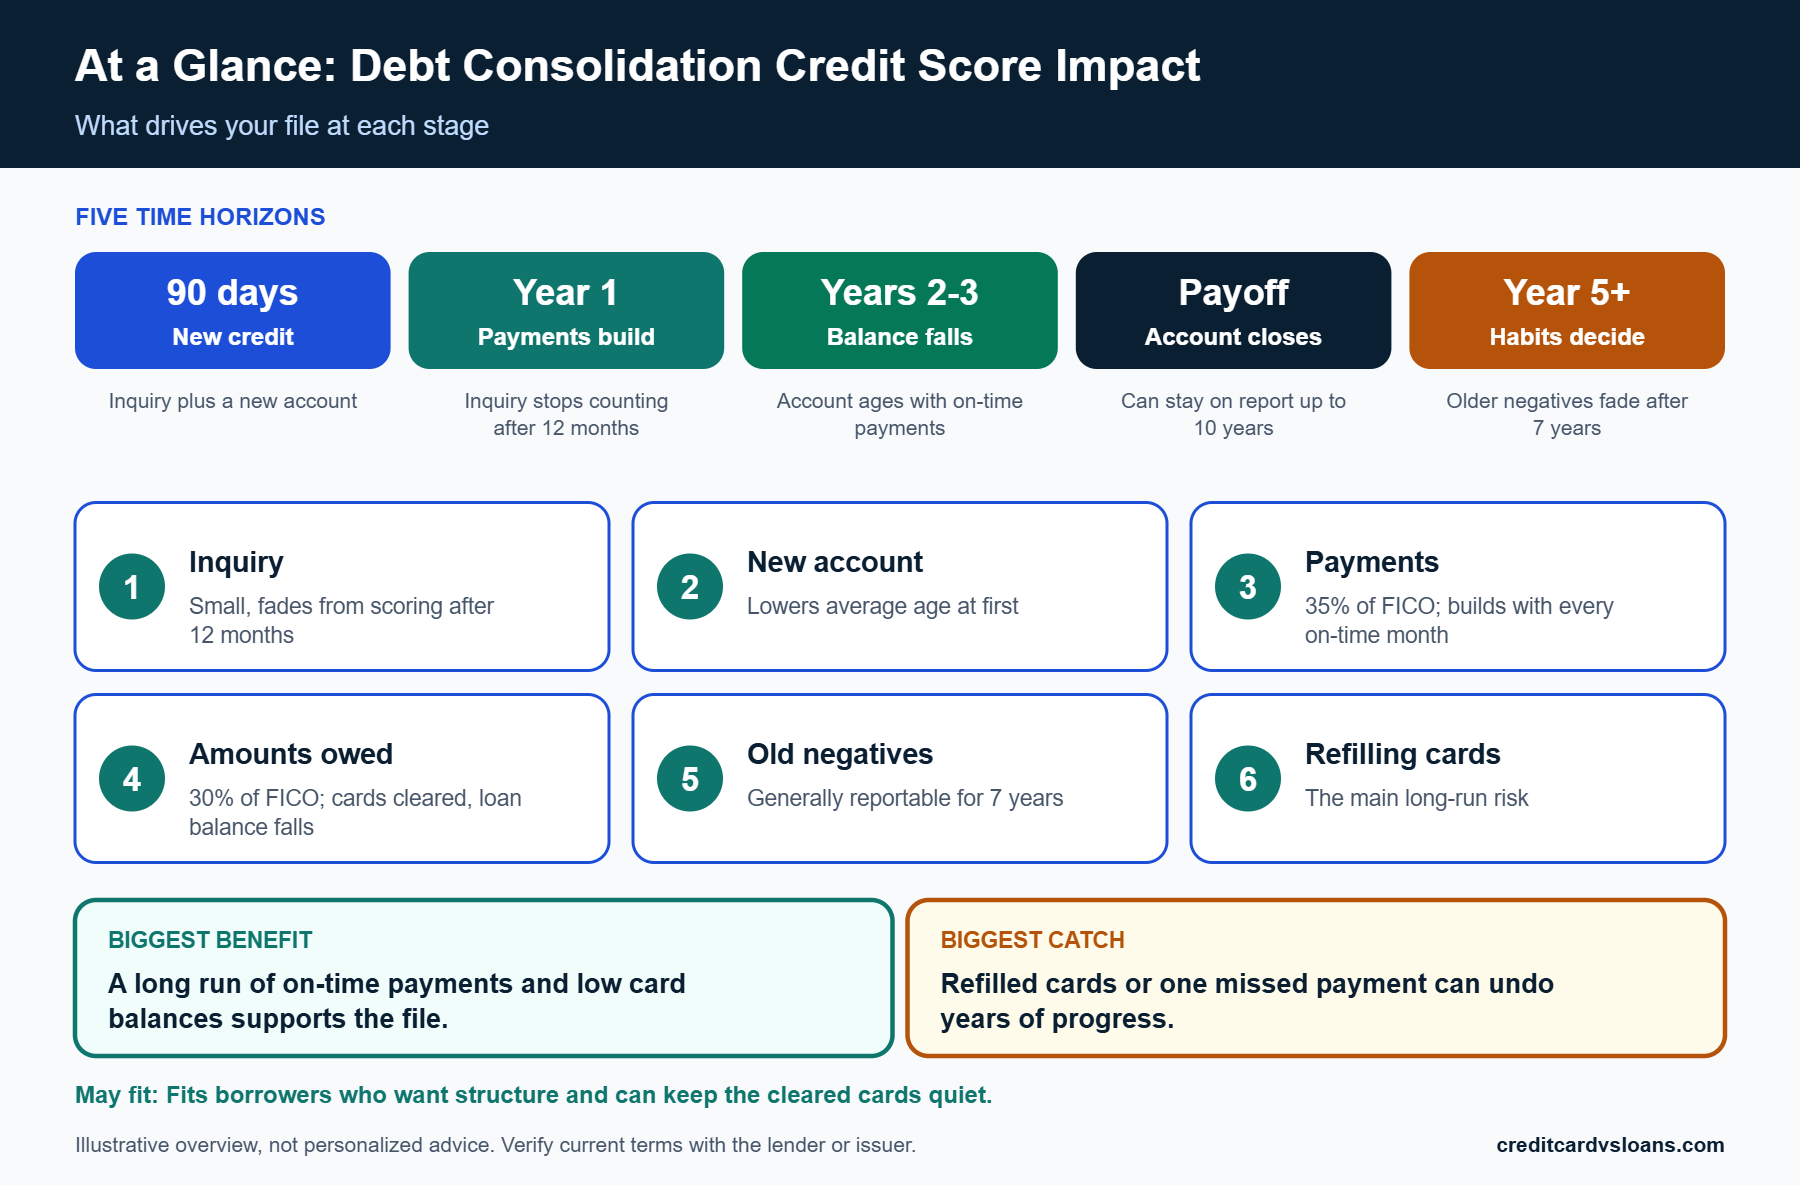
- Early effects (inquiry, new account) are usually small and fade; later effects (payments, balances, account age) tend to matter more.
- FICO weights payment history at 35% and amounts owed at 30%, so years of on-time payments and lower balances carry the most long-term weight.
- Most negative information can be reported for seven years, and closed accounts in good standing can stay on reports for up to 10 years.
- Consolidation changes the shape of debt (revolving to installment, for example) without changing how much you owe.
- Re-borrowing on cleared cards is the most common way the long-run picture turns worse.
- The horizons below are illustrations; your own timeline will differ.
Market rate context comes from the Federal Reserve G.19 consumer credit release of October 7, 2026 (August 2026 data). Offers vary by lender and borrower, so confirm your own terms.
Table of contents
Debt consolidation credit score impact: the long view in one table
Short run versus long run
What tends to happen first
According to myFICO, new credit makes up 10% of a FICO Score, inquiries stay on your report for two years but only those from the last 12 months are considered, and opening an account lowers the average age of your accounts. The CFPB says hard inquiries can lower your scores. These early effects are real but usually modest.
They are also the effects people notice most, because they arrive quickly and are easy to link to the loan.
What tends to matter later
Over longer periods, FICO’s two biggest categories take over: payment history at 35% and amounts owed at 30%. A year of on-time payments and a lower revolving balance carry more weight than a one-time inquiry. myFICO also says a longer credit history has a positive effect, which is why an account that stays open and in good standing becomes more helpful with time.
This is the basic reason that a score can dip in month one and look different by month twelve, without any trick involved.
How to use this guide
The five horizons
The guide is organized around five horizons: the first 90 days, the first year, years two and three, the end of the loan, and year five and beyond. Table 1 summarizes what each horizon is mostly about.
Where related questions live
Questions about qualifying for a loan are covered in the guide to the best debt payoff options by credit score. How personal loans work as a category is covered in the personal loan credit impact guide. Utilization has its own explanation in the credit utilization guide.
| Horizon | Main forces at work | Typical tone (not a prediction) | What you control |
|---|---|---|---|
| First 90 days | Hard inquiry, new account, card balances reported at zero | Mixed: small dip from new credit, possible help from utilization | Whether you apply once and how you handle the old cards |
| First year | On-time payments accumulate; loan balance declines | Building | Autopay, a payment you can sustain |
| Years 2 and 3 | Account ages; inquiry no longer counts; balance keeps falling | Steadier | Staying out of new card debt |
| End of the loan | Installment account closes in good standing | Neutral to slightly mixed | Whether you keep other accounts active |
| Year 5 and beyond | Closed accounts age off; history reflects later habits | Depends on what came after | Everything you do next |
The first 90 days: inquiry, new account and reporting lag
What shows up first
The inquiry and the new account
A formal loan application typically produces a hard inquiry. A soft inquiry, such as a prequalification check or looking at your own report, does not affect your scores, according to the CFPB. The loan then appears as a new installment account, which lowers the average account age, particularly on a short history.
Both effects are small relative to the rest of the file, but they are the ones you may see first.
Reporting lag
Lenders report on their own schedules, so the loan and the card payoffs may not appear at the same time. During the first weeks, your report may show the new loan balance and still show old card balances, which can make the picture look worse than it is. A month later, the cards report zero.
Judging the effect in week one is like reading a thermometer before it settles.
The utilization step
How a payoff changes revolving balances
Imagine $10,000 across three cards with $15,000 in combined limits, about 67% utilization, paid off with a $10,000 loan. If the cards report zero, revolving utilization falls to 0%. FICO describes amounts owed as 30% of a score and includes how much of your available credit you use. Lower utilization is generally viewed favorably.
The loan balance still counts as debt owed, however, and total debt did not change.
The first months of payments
Each month, the loan payment is reported as on time or late. At a hypothetical 12% APR over 36 months, the payment would be about $332. Every on-time month adds to a payment record that myFICO calls the strongest predictor of whether you will pay debts as agreed.
The first 90 days are therefore less about the score and more about setting up systems that protect the payment record.
Years one to three: the payment record builds
What the loan balance does
An amortization snapshot
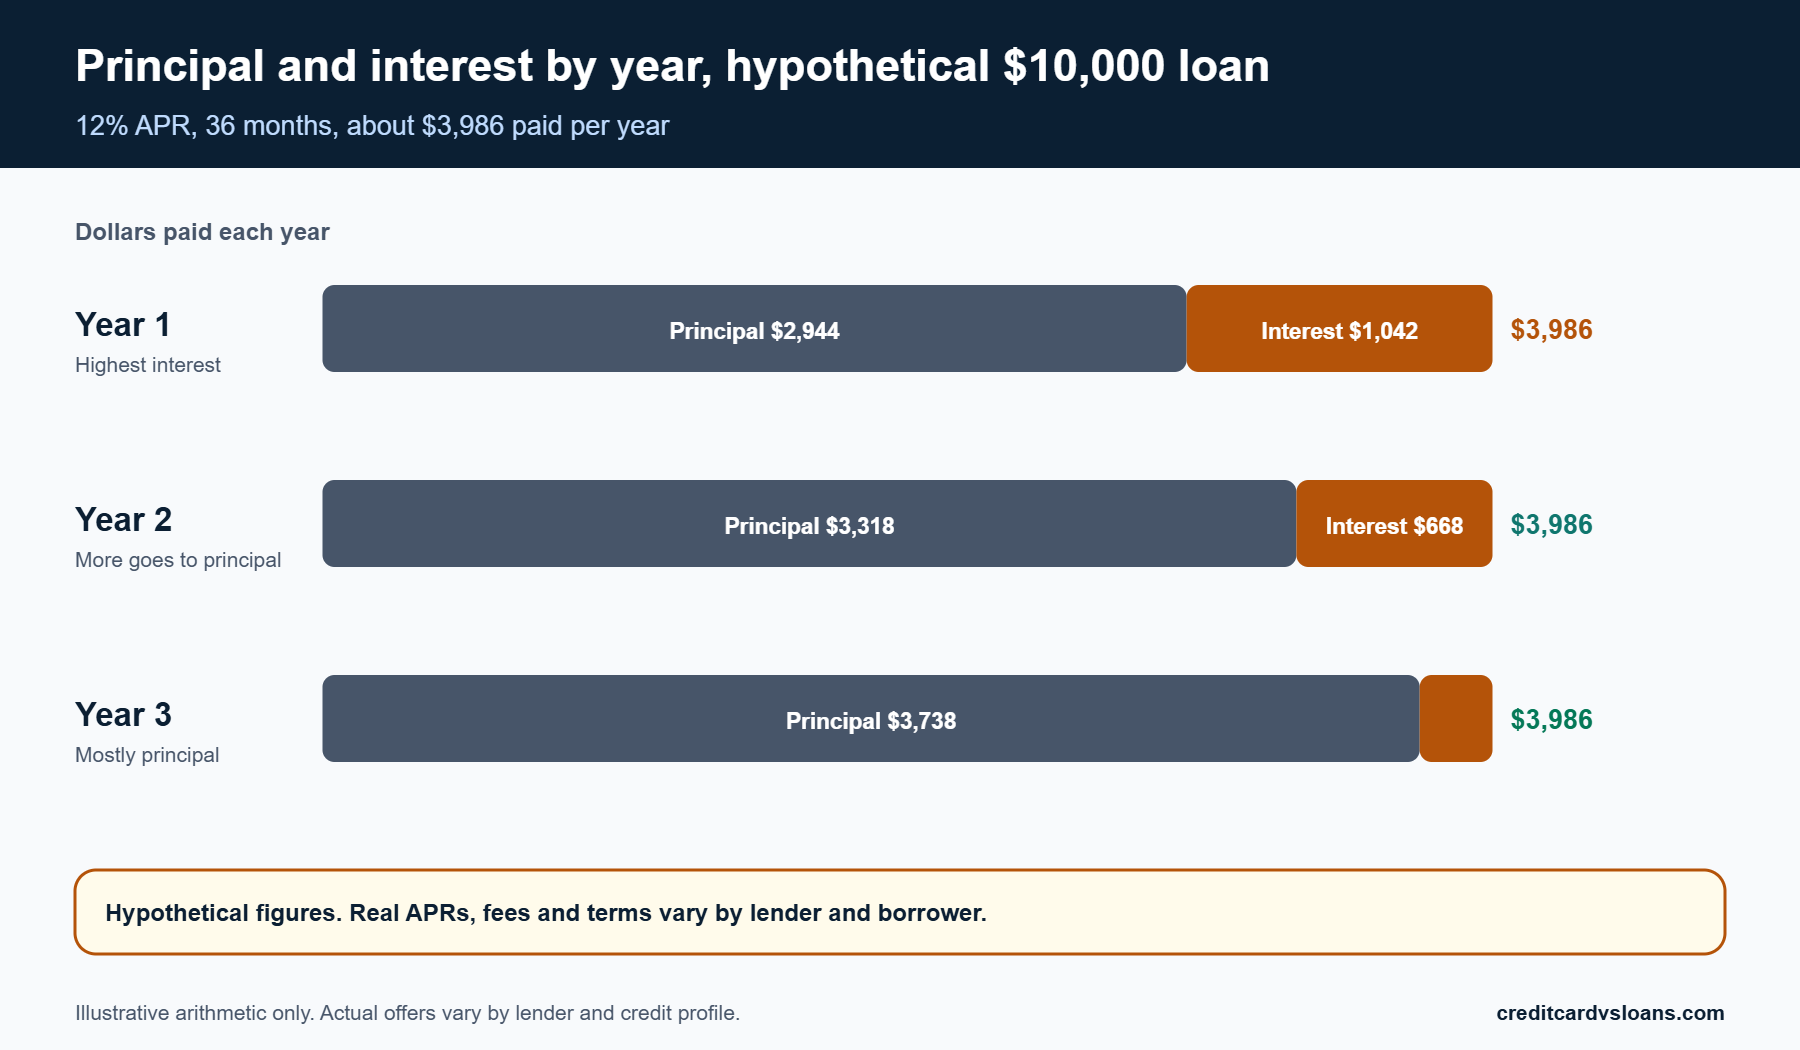
On the hypothetical $10,000, 12%, 36-month loan, the balance would be roughly $8,572 after six payments, $7,056 after twelve, $3,738 after twenty-four and zero after thirty-six. In the first year, about $1,042 of the $3,986 paid would be interest; in the second year about $668; in the third year about $248. The shape is front-loaded interest, then more principal.
This is arithmetic for the example only, and your terms will differ.
Why it matters for your file
An installment balance that steadily declines tells a different story from a revolving balance that stays near the limit. FICO does not simply compare the two, but a falling loan balance with a clean payment record is generally a favorable pattern. Your credit mix also now includes an installment account, which myFICO describes as part of the 10% credit mix category.
None of this overrides what happens if a payment is late, which is the next point.
Account age and the aging inquiry
The inquiry drops out
After 12 months, the hard inquiry from the application is no longer considered by FICO scores, though it remains on the report for two years. By the end of year two, it disappears from the report. The effect that people worried about at the start is gone.
Other scoring models may handle inquiries slightly differently, so a particular lender’s score could vary.
The new account matures
The loan’s age starts at zero and grows by a month each month. By year three, it is a three-year-old account, and it has a record of 36 on-time payments if you paid as planned. In myFICO’s description, length of credit history considers the age of your oldest account, newest account and the average of all accounts.
The long-run effect of the loan on account age is positive if it stays on your report in good standing.
What each route costs and what it does to your file over time
Comparing the main routes
Four ways to restructure card debt
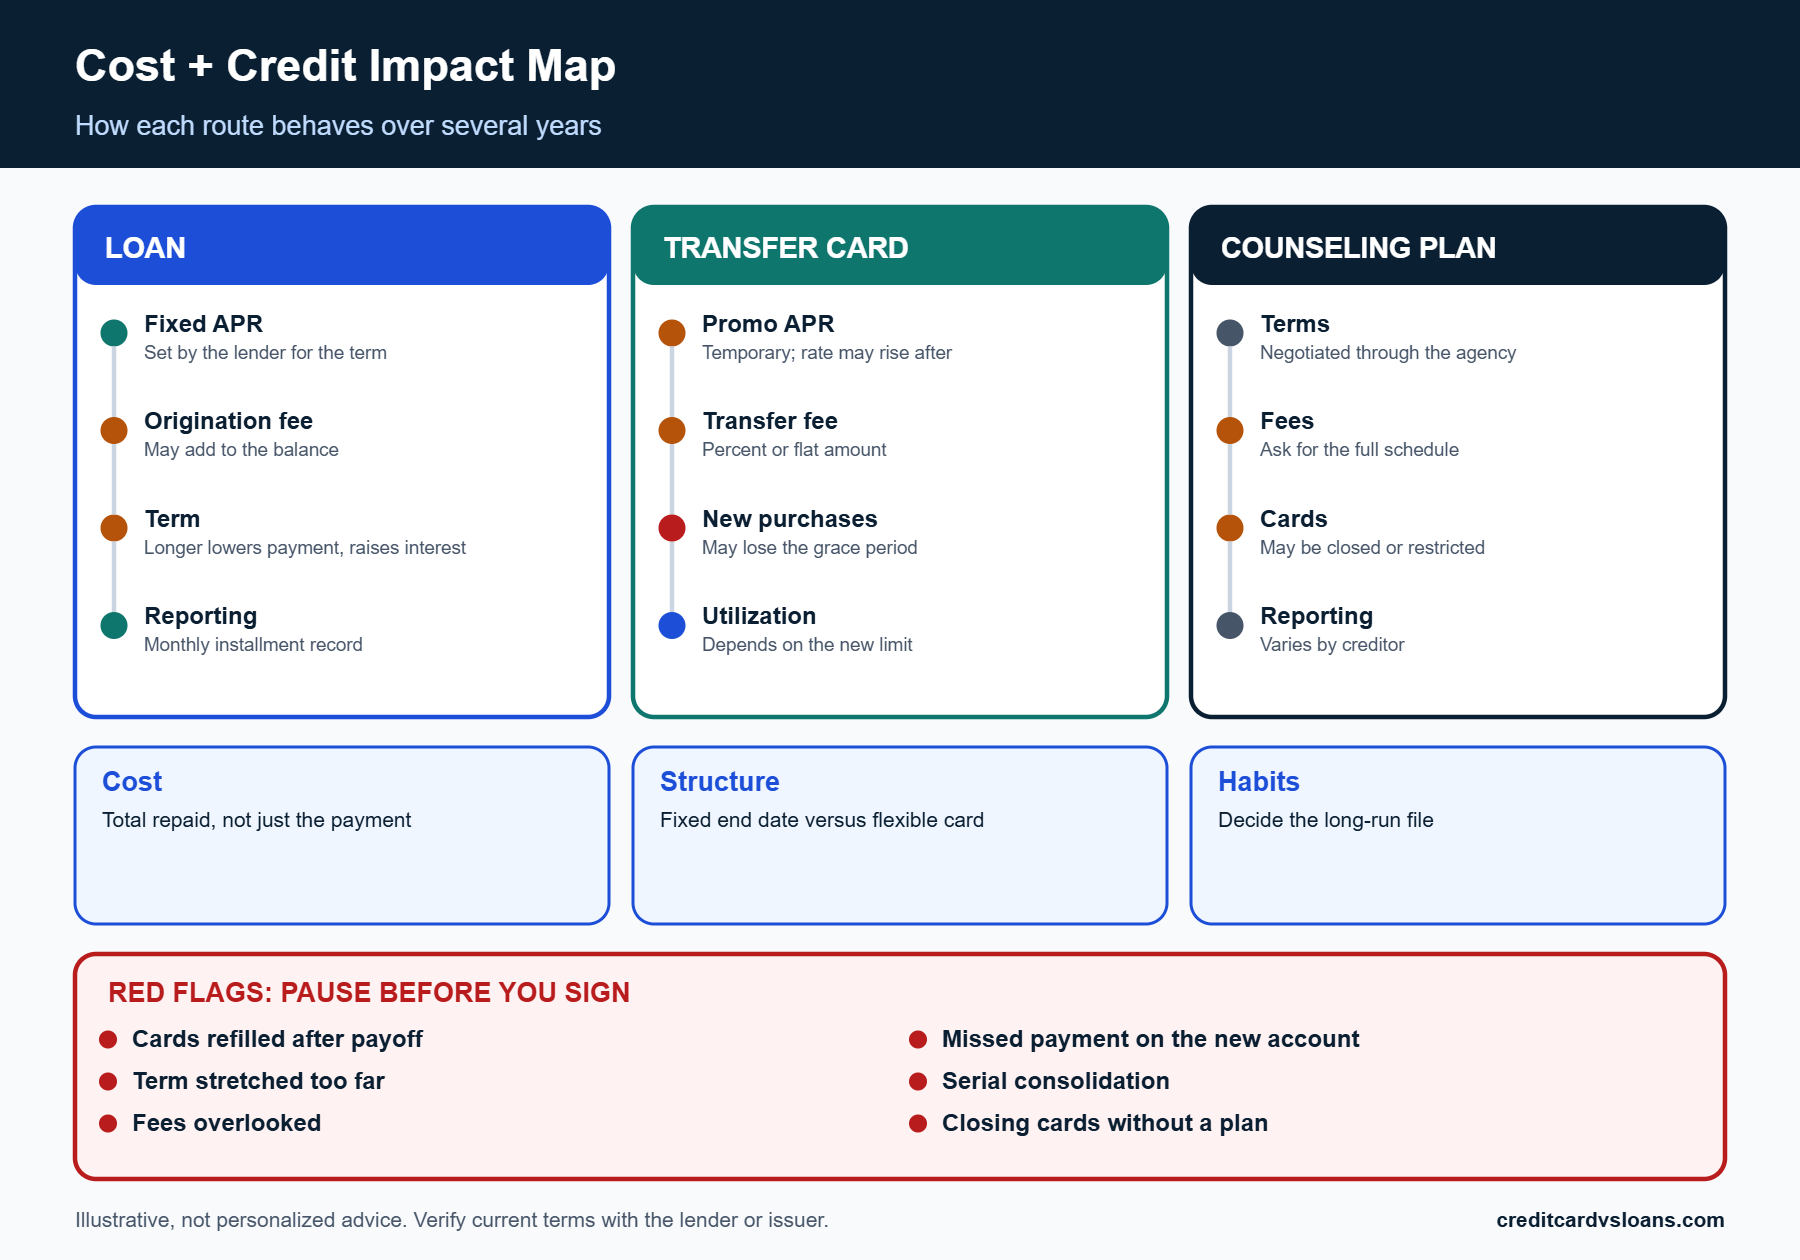
People who consolidate usually choose among a fixed-term loan, a balance transfer card, a nonprofit counseling-based plan, or paying the cards down in place. They differ in cost, in how they are reported and in how much freedom you keep to spend again. Table 2 compares them on the dimensions that matter for both cost and credit.
The details below reflect general features; each lender or agency has its own terms, and you should read them before you decide.
| Route | Rate type | Fees to check | Credit inquiry | Utilization and balance effect | Risk flags |
|---|---|---|---|---|---|
| Fixed-term loan | Fixed APR for the term, set by the lender | Origination fee, late fee, prepayment penalty | Hard inquiry on formal application | Moves card balances to an installment balance; card utilization can fall | Cards refilled; payment strain |
| Balance transfer card | Promotional APR for a limited period, then regular APR | Transfer fee (percent or flat amount), annual fee | Hard inquiry for the new card | Debt stays revolving; utilization depends on the new limit | Balance left after promotion; new purchases |
| Nonprofit counseling plan | Terms negotiated through the agency; vary | Program or monthly fees; ask for a full schedule | Often no new credit application, but reporting varies | Enrolled cards may be closed or restricted | Missed plan payments; fees |
| Pay down in place | Existing card APRs | None added | None | Balances fall only as fast as you pay | Slow progress at high APRs |
Where the market rates sit
For context, the Federal Reserve’s G.19 release of October 7, 2026 reported an average rate of 22.36% on credit card accounts assessed interest in August 2026 and 11.90% on 24-month personal loans at commercial banks. Those are averages, not offers, and borrowers with weaker credit may be quoted higher while stronger files may be quoted lower.
The gap between the two averages is the reason many people consider a loan at all, but the gap shrinks or disappears with a high-APR offer or a large fee.
How cost affects the long-run file
Interest and the speed of paydown
Hypothetically, $10,000 on a 12% loan over 36 months costs about $1,957 in interest. Year one carries the most interest because the balance is highest, and year three the least. The chart below shows the principal and interest split by year for that example.
Paying the same dollars to a lower-rate structure means more of each payment reduces the balance, which is the link between cost and a falling debt load.
Fees as a drag on the starting balance
Fees can raise the amount you have to repay. The CFPB says balance transfer fees are typically a percentage of the amount transferred or a flat amount, whichever is greater. A hypothetical 5% loan origination fee would mean borrowing about $10,526 to net $10,000, raising the payment at 12% over 36 months from about $332 to about $350.
The fee does not appear as a separate item in your credit score, but it increases the debt you carry, which is the part scoring models see.
Eligibility and the file you bring
What lenders see
Lenders look at your credit report and score, your income and your existing obligations. A better file generally helps you qualify at a better rate, as the CFPB notes, but the exact thresholds vary by lender. The debt payoff options by credit score guide describes which routes tend to be available at different score levels, without promising any outcome.
Prequalification with a soft pull is a way to see likely terms before a hard inquiry.
How your file affects the long run
A thin file feels a new account more. A file with recent late payments may be offered a higher APR, which raises cost and the risk of another missed payment. A long, clean file typically absorbs a new account with less visible change. These are tendencies, and they shape which long-run path is realistic for you.
The end of the loan and what comes after
When the account closes
A closed installment account in good standing
When the last payment posts, the loan closes. Experian explains that closed accounts that are not past due will generally remain on your credit reports for up to 10 years and can keep helping your scores during that time. They also keep counting toward account age until they fall off.
So the payoff itself is not a cliff. The account stays in your history as a record of on-time repayment.
What can feel like a dip
Experian also notes that closing your only installment loan can reduce the benefit of your credit mix. If the loan was your only installment account, you might see a small shift when it closes. That is a reason to avoid over-reading a score change right after a payoff, not a reason to delay paying off a loan.
Closed cards and the 10-year window
Cards you closed along the way
If you closed cards after paying them off, they too remain on the report for up to 10 years if they were in good standing, according to Experian. When they fall off, your average account age can drop if they were among your oldest accounts. That change is gradual and predictable, which allows you to plan.
The utilization effect of closing is immediate, however, since the limit is gone. Experian’s example is a $1,500 balance on $10,000 of limits at 15% rising to 21% when a $3,000 card closes.
Cards you kept open
Cards kept open with small or zero balances preserve available credit and keep adding history. If a card has no annual fee, a small recurring charge paid in full can keep it active, subject to the issuer’s rules. The long-run value of that choice depends on your discipline.
Compare the cost of keeping a card, if any, with its benefit before deciding.
A hypothetical three-year file, side by side
Two borrowers, one loan
The setup
Take the hypothetical $10,000 loan at 12% over 36 months, used to clear $10,000 on cards with $15,000 in combined limits. Both borrowers pay the loan on time every month. Borrower A leaves the cards untouched. Borrower B adds $2,500 of card charges each year and carries them forward. These are illustrations, not real people, and the numbers are arithmetic, not predicted score changes.
The question is what the file looks like at each year-end for each borrower.
What changes and what does not
For both, payment history on the loan is clean, the inquiry stops counting in FICO scores after 12 months, and the loan account ages. The difference is in amounts owed. Borrower A’s revolving utilization stays near 0% while the loan balance falls; Borrower B’s utilization climbs from about 17% to about 50% over three years while the loan balance falls to zero.
Table 4 shows the path.
| Year-end | Loan balance | A: card balance (utilization) | B: card balance (utilization) | B: total debt |
|---|---|---|---|---|
| Start | $10,000 | $0 (0%) | $0 (0%) | $10,000 |
| Year 1 | $7,056 | $0 (0%) | $2,500 (about 17%) | $9,556 |
| Year 2 | $3,738 | $0 (0%) | $5,000 (about 33%) | $8,738 |
| Year 3 | $0 | $0 (0%) | $7,500 (50%) | $7,500 |
Reading the comparison
Why Borrower B’s file can mislead
Borrower B’s total debt falls from $10,000 to $7,500 over the three years, which sounds like progress. But the debt has moved back to revolving cards, where interest rates are typically higher, and utilization has risen to 50%. If the card APRs are near the 22.36% average the Federal Reserve reported for August 2026, the interest on that balance can add up quickly.
A falling total can hide a deteriorating mix, which is why the type and cost of the debt matter alongside the amount.
What this means for the long view
For both borrowers, the payment record is the same. What differs is the amounts-owed category, which FICO weights at 30%, and the cost of carrying the balance. The consolidation did not decide the outcome; the behavior afterward did.
This is the central idea of the whole long-run picture, and it is why a loan is a tool and not a result.
Special circumstances that change the arc
Life events and file types
A planned mortgage or auto loan
If you plan to apply for a major loan within a year or two, the timing of a consolidation matters, since a new inquiry and new account can show up while the lender reviews your file. Lenders also look at your total debts and your payment record. There is no universal waiting period, so ask the lender what they look for.
Avoid opening unrelated accounts around the time of a major application.
Income changes
A drop in income can turn a comfortable payment into a strained one. If your income might change, choose a payment that still works in a lower-income month, and consider a buffer. Contact the lender early if you run into trouble.
Different starting points
High balances relative to limits
If your cards are close to their limits, the early utilization drop after consolidation can be the largest piece of the change. The same drop is smaller when starting utilization is already low. The utilization guide explains why.
Low balances and a strong score
When your balances are already low and your history is long, the credit effect of consolidating may be small, and the decision comes down to cost. A simpler approach, such as paying the balance down directly, may fit better.
The five FICO categories over the long run
The heavy categories
Payment history (35%)
In the long run, this is the category with the most upside and the most downside. Every on-time month adds to the record, and a late payment of 30 days or more can be reported, though the exact reporting rules depend on the lender. myFICO says one or two late credit card payments can be outweighed by a generally strong history, and that recent, large and numerous delinquencies count more.
Over three years of loan payments, you build 36 data points. That is a substantial record, and it is why protecting each payment date matters more than almost any other choice.
Amounts owed (30%)
Amounts owed covers both how much you owe in total and how much of your available credit you use. After consolidation, revolving utilization may fall, while the installment balance declines on its schedule. myFICO notes that carrying debt is not automatically negative, but high utilization on revolving accounts can suggest you are overextended.
Over several years, the key question is whether revolving balances stay low or drift upward again, which is the difference between Borrower A and Borrower B in the earlier table.
The lighter categories
Length of credit history (15%) and new credit (10%)
The new loan lowers average account age at first, then helps as it ages and stays on your report. The inquiry counts for 12 months in FICO scores and stays on the report for two years. By year two, the new-credit effect of the original application is gone, unless you have applied for other credit since.
If you open several accounts in a short span later, new credit can weigh again, so spacing out applications matters.
Credit mix (10%)
Mix is the variety of credit types, such as cards and installment loans, and myFICO says you do not need one of each. A consolidation loan can add an installment account to a card-only file. When the loan closes, Experian notes that closing your only installment loan can reduce the benefit of your credit mix.
Because mix is usually less influential than the other categories, it is a poor reason to take or keep a loan. Treat it as a minor side effect.
Year five and beyond: negative marks, habits and the recovery arc
How long the past stays on the report
The seven-year rule of thumb
The CFPB says a company generally can report most negative information for seven years, bankruptcies for up to ten, and positive payment history for longer. Late payments that led to your consolidation are therefore not erased by the loan, but their weight fades. myFICO says newer negative items count more than older ones and that scores can improve as time passes and on-time payments accumulate.
So the long-run effect of consolidation can include something quiet: it gives you a stretch of on-time payments that begins to outweigh older problems.
What consolidation cannot rewrite
Consolidating does not delete late payments or collections already on your report. If an old account was past due before you consolidated, it generally keeps its original timeline. If you are unsure what is on your reports, review them for accuracy and dispute errors through the bureaus.
A clean report going forward matters more than any single account.
Habits that decide year five
The refill risk over a longer horizon
The Federal Reserve’s G.19 release of October 7, 2026 reported total revolving credit outstanding of about $1,352.4 billion (seasonally adjusted, August 2026), a reminder of how common card balances are. Over several years, the typical way a consolidation loses its value is gradual: a few unplanned charges, then a few more.
If the cards fill again while the loan is still being paid, you may be carrying both, and the long-run file looks worse than it did before.
What keeps the arc favorable
Three habits do most of the work: automatic payments, a small emergency fund and a rule about the cleared cards. None is glamorous. Together they make it more likely that the early dip is followed by years of clean data. The utilization guide explains how card balances show up in scoring, and why low balances on open cards usually look better than high ones.
Where the long view can go wrong
Patterns that undo the benefit
Serial consolidation
Consolidating again every time balances rebuild creates repeated inquiries and new accounts, and each new loan may carry a new origination fee. FICO says opening several new accounts in a short period is viewed as riskier, especially with a short credit history. A pattern of serial consolidation can also be a sign that the underlying budget needs attention.
This does not mean a second loan is never reasonable, only that it deserves a hard look at why the first did not hold.
Stretching the term too far
A longer loan term lowers the payment but increases interest and keeps you in debt longer. On the hypothetical $10,000 at 12%, a 60-month term costs about $3,347 in interest, compared with about $1,957 over 36 months. If a longer term makes on-time payments possible, it can still be the right call, but weigh it knowingly.
Warning signs along the way
Signs in your balances
A loan balance that is not falling as scheduled, cards that rise month after month, or reliance on minimum payments are signs to act sooner. They do not mean failure, but they are easier to fix early.
Consider talking to a nonprofit credit counselor if multiple debts are getting out of hand.
Signs in your budget
If the monthly payment leaves nothing for emergencies, a single surprise can lead to a missed payment. A payment you can sustain through a bad month usually protects the payment record better than the lowest possible rate.
Review your budget when income changes, and contact the lender before a due date if you foresee a problem.
Which path fits over time? A decision matrix
Matching horizon to route
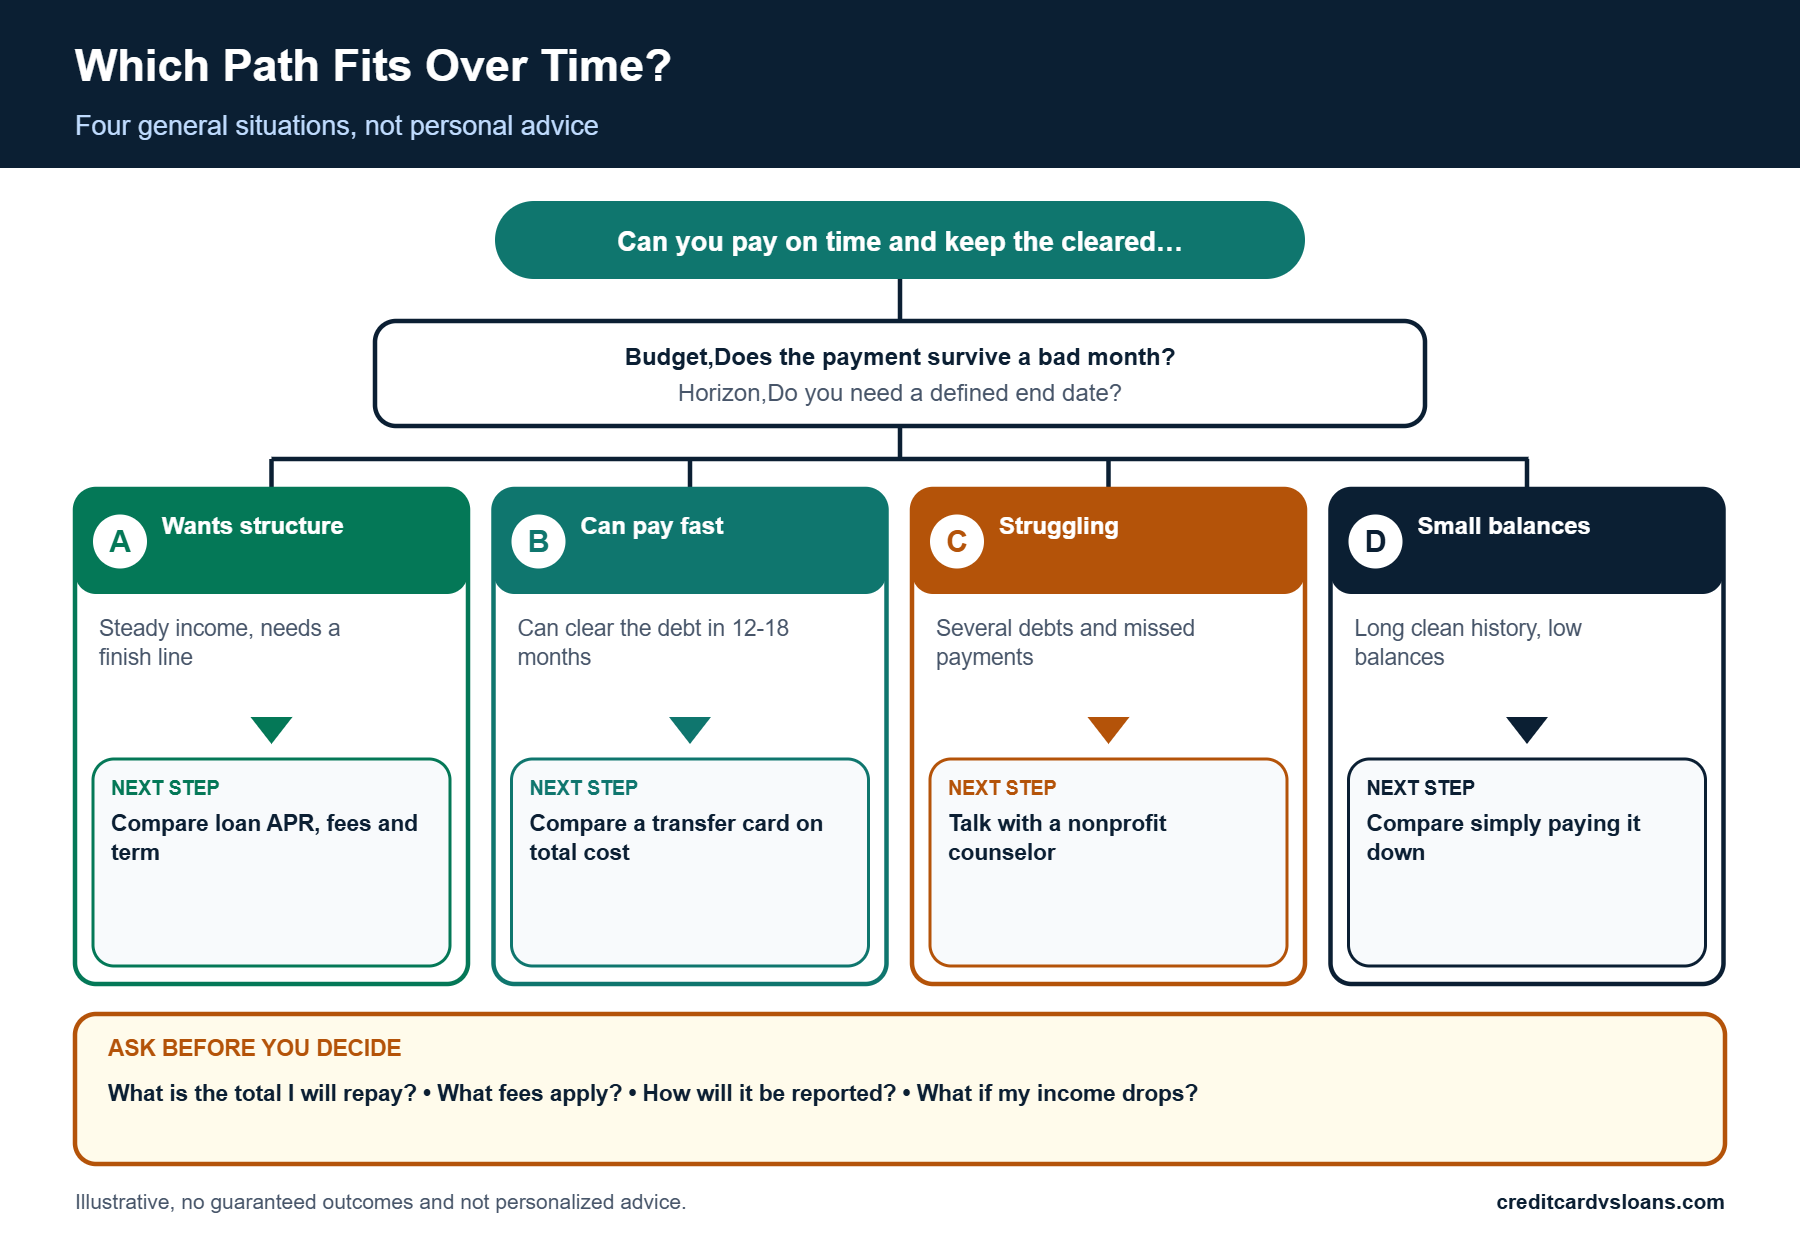
If you want a defined end date
A fixed-term loan has a built-in finish line, which can help borrowers who do better with structure. Consider it if you can qualify at a rate and fee that make sense after you compare the total cost. The personal loan credit impact guide covers how loans are reported.
If you can clear the debt quickly
A balance transfer card can fit if the balance can be paid within the promotional period and the new limit is large enough. The factor-by-factor transfer guide explains how its mechanics differ.
Matching your file to the choice
Thin or recently damaged files
On a thin file, one new account and one inquiry matter more; on a file with recent late payments, offers may be costly. In both cases, a slower, simpler approach or a conversation with a nonprofit counselor may deserve a look first.
Established files with moderate balances
For established files with moderate balances, the credit effect of consolidating is likely to be small either way, and the decision comes down to interest cost, fees and whether the structure helps you pay on time. Table 3 gives a matrix.
| Situation | Route to investigate | Why | What to verify | When to avoid it |
|---|---|---|---|---|
| Needs a fixed end date | Consolidation loan | Fixed payment, clear finish line | APR, fees, term, prepayment rules | If payment is tight or APR is very high |
| Can pay within 12 to 18 months | Balance transfer card | Low promotional interest speeds paydown | Fee, limit, rate after promotion | If you will keep spending on the cards |
| Several debts and trouble keeping up | Nonprofit counseling | Structured plan and guidance | Agency credentials, fees, how accounts report | If you need to keep cards open for work |
| Small balances, long clean history | Pay down in place | No inquiry, no new account | Interest cost versus time | A new account may add little |
| Recent late payments or collections | Address the cause first | New credit will not fix a payment pattern | Report accuracy; dispute errors | If you would apply widely for credit |
Questions people ask about the long-run effect
Choosing and committing
Is it better to consolidate everything or just the most expensive debt?
It depends on the rates, the fees and your payment capacity. Consolidating only the highest-APR balances can keep the loan smaller and the payment lower, but leaves more accounts to manage. Consolidating everything simplifies, but a loan with a higher APR than some of your existing debts can raise your cost on those balances.
Compare total cost for each version before you choose.
Can I ask for a different due date?
Many lenders allow a due-date change, though policies differ. Aligning the date with your paycheck can reduce the risk of a missed payment, which protects the part of your file that matters most. Ask before you sign.
Timing and expectations
When will my score look “normal” again?
There is no standard date. The inquiry stops counting in FICO scores after 12 months, the new account ages with time, and balances change as you pay. Many people notice the early dip fading before the one-year mark, but that depends on the file and the model.
Focus on the inputs you control rather than a date on the calendar.
Does paying the loan off early help?
Paying early reduces interest and removes the debt sooner. The score effect of closing an installment account in good standing is usually modest, and the interest saved is real. Check for a prepayment penalty first.
Scoring models and sources
Why do two scores differ?
The CFPB says there is no single credit score: scores vary by scoring model, data source and the date they are calculated. That is why a bank app, a lender and a free service can show different numbers for the same person on the same day.
Track the same score from the same source over time to see your trend.
Where do I check the details?
Your credit reports show account status, balances, limits and inquiries. Checking your own report does not affect your FICO scores, according to myFICO. Review it after the loan posts, again a few months later, and before any big application.
Tracking your progress
What to write down each quarter
Every three months, record the same score from the same source, the loan balance, each card’s balance and limit, and the date of your last payment. After a year you will have four data points; after three years, twelve. Patterns become visible that a single check cannot show.
If the score moves in a way you do not understand, compare the dates against your report: a new inquiry, a closed account or a change in a reported limit often explains it.
When to revisit the plan
Review the plan when your income changes, when a card balance starts rising, or when you are within a few months of the loan ending. These moments are natural decision points: whether to keep or close cards, whether to borrow again, or whether to redirect the freed-up payment to savings.
A common and sensible choice after the final payment is to send the old loan payment into an emergency fund, so the next surprise does not land on a card.
Mistakes that cost the most
Judging the result too soon
Many people check a score after a week, see a dip and conclude the loan was a mistake, or see a rise and conclude the problem is solved. Reporting lags, scoring models differ, and the early period is the noisiest. Give it at least a couple of billing cycles, and then look at the trend over quarters rather than days.
Treating the loan as the finish line
The loan restructures the debt; it does not remove it. The finish line is the final payment, and the work between now and then is mostly ordinary: paying on time, keeping the cards quiet and adjusting the budget when life changes. Borrowers who treat the first month as the achievement tend to relax at exactly the wrong time.
Conclusion and next steps
The long-run takeaway
Early noise, later signal
Expect a small, temporary effect from new credit, then a record that reflects your payments and balances. Over years, that record matters more than the choice of consolidation route.
Debt consolidation credit score impact unfolds over time. The first weeks are about new credit, the next years about payments and balances, and the long run about habits. The routes differ in cost and structure, and none can promise a score outcome.
What to do with it
Choose the structure that you can pay on time, at a total cost you understand, and set up systems that keep the cleared cards quiet. Then let time and on-time payments do the slow work.
A concrete next-step list
Before you consolidate
- Review your reports for errors, and note balances, limits and APRs on every card.
- Prequalify where possible, and compare APR, fees, term and prepayment rules on total cost.
- Confirm the payment fits your budget with a cushion.
- Decide what happens to each card after it is paid off.
After you consolidate
- Set autopay and keep a small buffer in the account.
- Check your reports after a cycle or two to confirm balances and statuses.
- Keep card balances low and avoid new charges you cannot pay in full.
- Revisit the plan if payments become hard, and talk to the lender or a nonprofit counselor early.
- CFPB: What is a credit score?
- CFPB: What is a hard inquiry?
- CFPB: How long does negative information remain on my credit report?
- CFPB: What is a balance transfer?
- myFICO: What is in your credit score?
- myFICO: New credit and your FICO Score
- myFICO: Length of credit history and your FICO Score
- myFICO: Payment history and your FICO Score
- Federal Reserve: Consumer Credit – G.19 (Release of October 7, 2026 (August 2026 data))
- Experian: How long do closed accounts stay on your credit report?
Last updated: October 22, 2026. Rates, fees and lender rules change; verify current terms before acting.
The information on creditcardvsloans.com is provided for general educational and informational purposes only. It is not financial, legal, tax, credit, accounting or investment advice, and reading it does not create an advisor-client, fiduciary or any other professional relationship. Nothing here is an offer, solicitation or recommendation to borrow, lend or apply for any product.
Credit scores, interest rates, fees, eligibility rules, lender policies and laws change frequently and vary by lender, location and individual circumstances. Examples, figures and scenarios are illustrative only, do not predict your results and do not guarantee approval, savings, a particular rate or a credit-score outcome. Always confirm current terms directly with the lender or issuer and read the full agreement before you apply or sign.
Although we aim for accuracy and use reputable sources, we make no representations or warranties, express or implied, about the completeness, accuracy, reliability or timeliness of the content. Content may be drafted with the assistance of automated tools, so errors or omissions may still occur. Links to third-party sites are provided for convenience; we don’t control and aren’t responsible for their content.
To the fullest extent permitted by law, creditcardvsloans.com and its owners, editors, authors, contributors and affiliates disclaim all liability for any loss, damage or expense arising directly or indirectly from your use of, or reliance on, this content. Before making financial decisions, consult a licensed professional, such as a qualified financial advisor, attorney, tax professional or nonprofit credit counselor, who can consider your complete situation.