Travel rewards vs cash back comes down to a single question: how much of your spending, and how much of your willingness to plan, goes toward travel? If you fly or book hotels several times a year and enjoy planning redemptions, a travel card can return more; if your spending is everyday and local, a plain cash back card usually returns almost as much with far less work and risk.
This guide starts with you rather than with the cards. It sorts spending habits into four illustrative profiles, shows what each kind of reward quietly assumes about the way you live, and then walks through the costs and risks that tip the choice. For the mechanics of how points, miles and cash back work in general, see our overview of how rewards credit cards work; for a method to compare cash back offers, see how to compare cash back credit cards by real value.
Nothing here is a recommendation of a specific card. All dollar examples are hypothetical, and the federal figures are there to anchor the discussion in real data.
- Travel rewards pay off for people who travel often enough, and book flexibly enough, to redeem at a good value. Cash back pays off for nearly everyone else.
- A travel card has to beat cash back after its annual fee. In a hypothetical case with a $95 fee and 2 points per dollar, points must be worth more than 1 cent each before the card can ever pull ahead of a 2 percent cash back card.
- Award availability and program changes make travel value less predictable than cash. The CFPB cites a Department of Transportation review in which only 13 percent of holiday-week flights offered a seat at the lowest award level.
- Interest dwarfs both rewards: the Federal Reserve reported an average rate of 22.15 percent on accounts assessed interest in the second quarter of 2026.
- If you carry a balance, neither reward is the priority; the cost of the debt is.
Rate figures come from the Federal Reserve’s G.19 release of Sept. 8, 2026. Rewards market figures come from the CFPB’s May 2024 issue spotlight, which draws on earlier Bureau data. Point values and fees shown here are hypothetical and meant for comparison, not quotes.
Table of contents
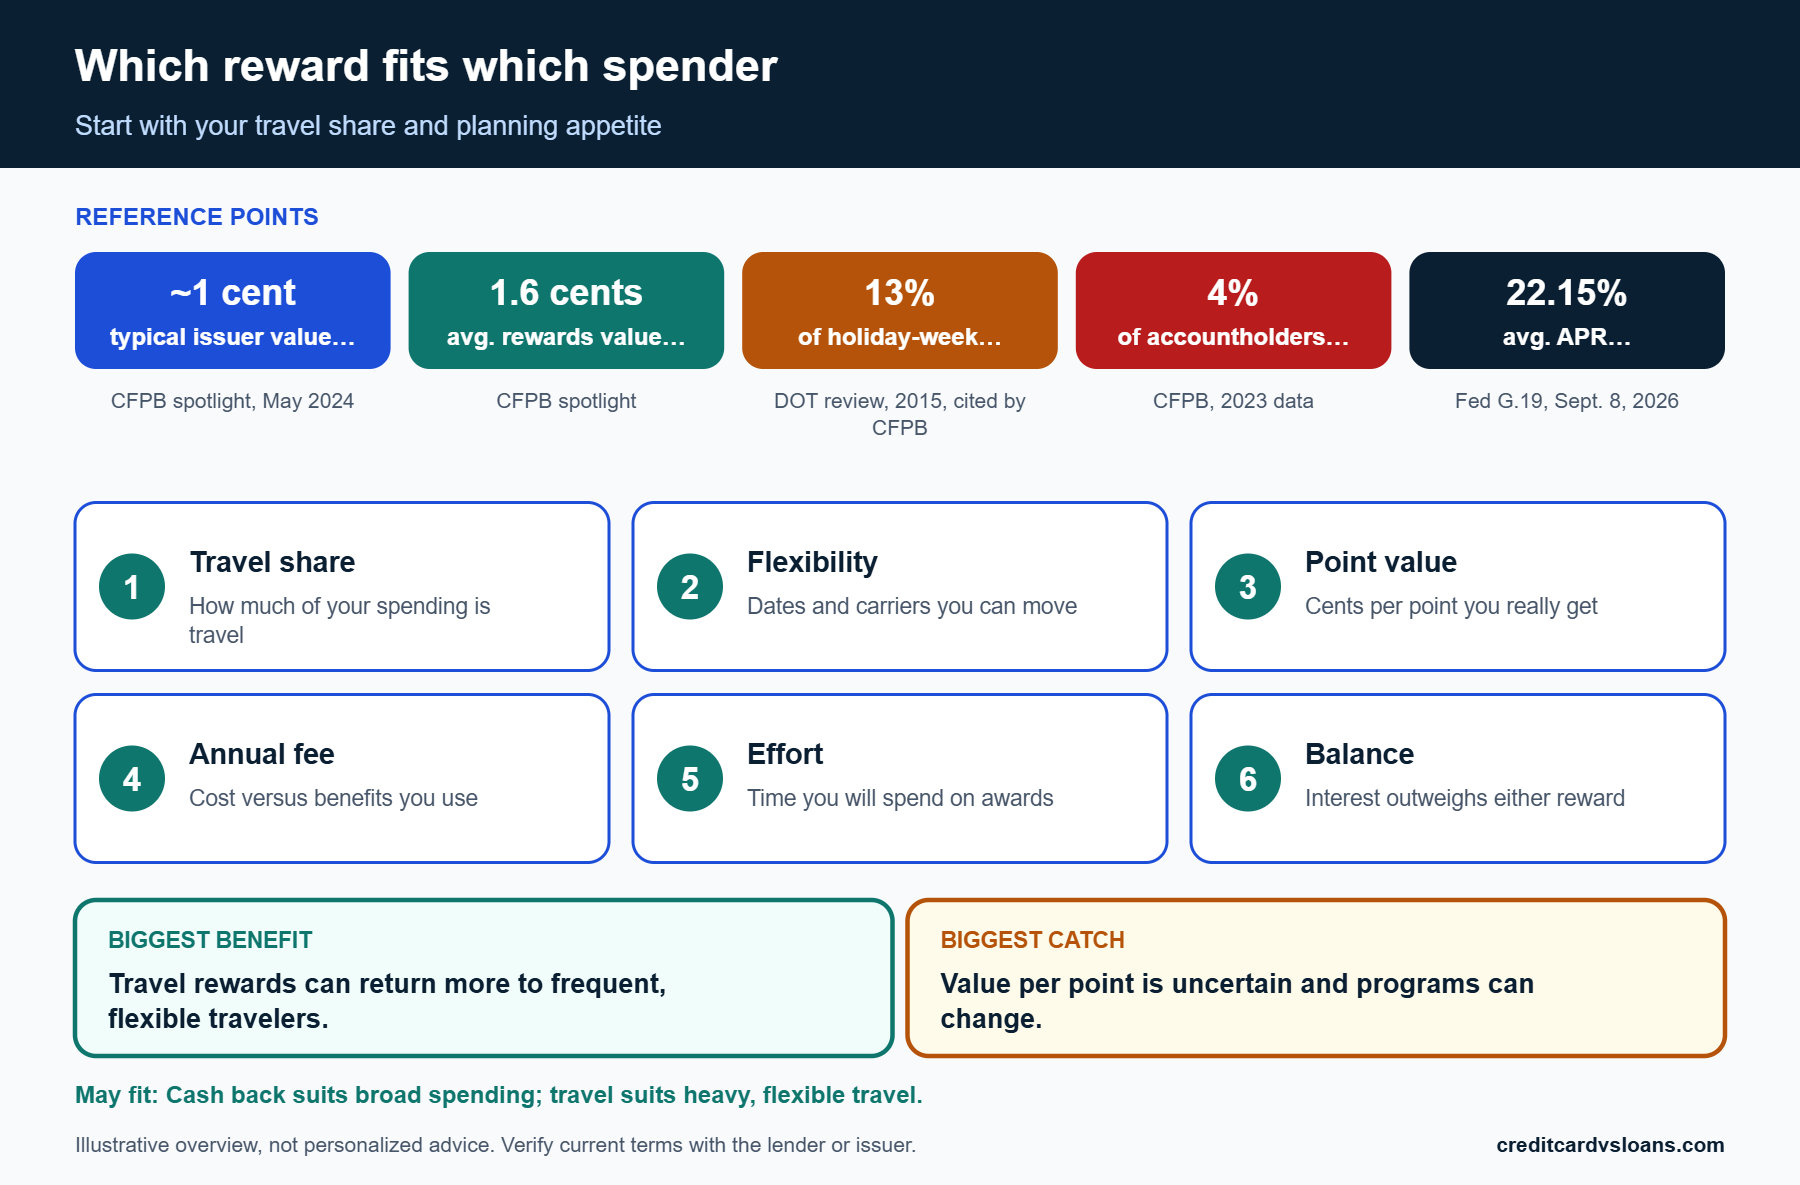
Which reward fits which spender: the short answer
Start with the shape of your year
Count your travel dollars honestly
Pull a year of statements and add up everything that is genuinely travel: flights, lodging, rental cars, trains, and the parts of a trip that can earn at a travel rate. Then compare that sum to your total card spending. If travel is a small slice, a travel card’s big headline rate applies to only a little of your money, and its everyday earn rate is probably no better than a good flat cash back card.
It also helps to separate trips you must take from trips you choose to take. Required travel is a predictable base that rewards can attach to; discretionary travel can rise because you hold a travel card, and that is how spending creeps.
Count your planning appetite too
Travel rewards ask for effort. You compare award prices, watch for availability, time transfers and keep an eye on program changes. If that sounds enjoyable, the effort is part of the benefit. If it sounds like a chore, the time you will not spend is a hidden cost of the card.
Cash back removes this variable. A statement credit or deposit is the same on every day of the year, and nobody has to hold a spreadsheet of award charts to use it.
Four illustrative spending profiles
Everyday spenders and occasional travelers
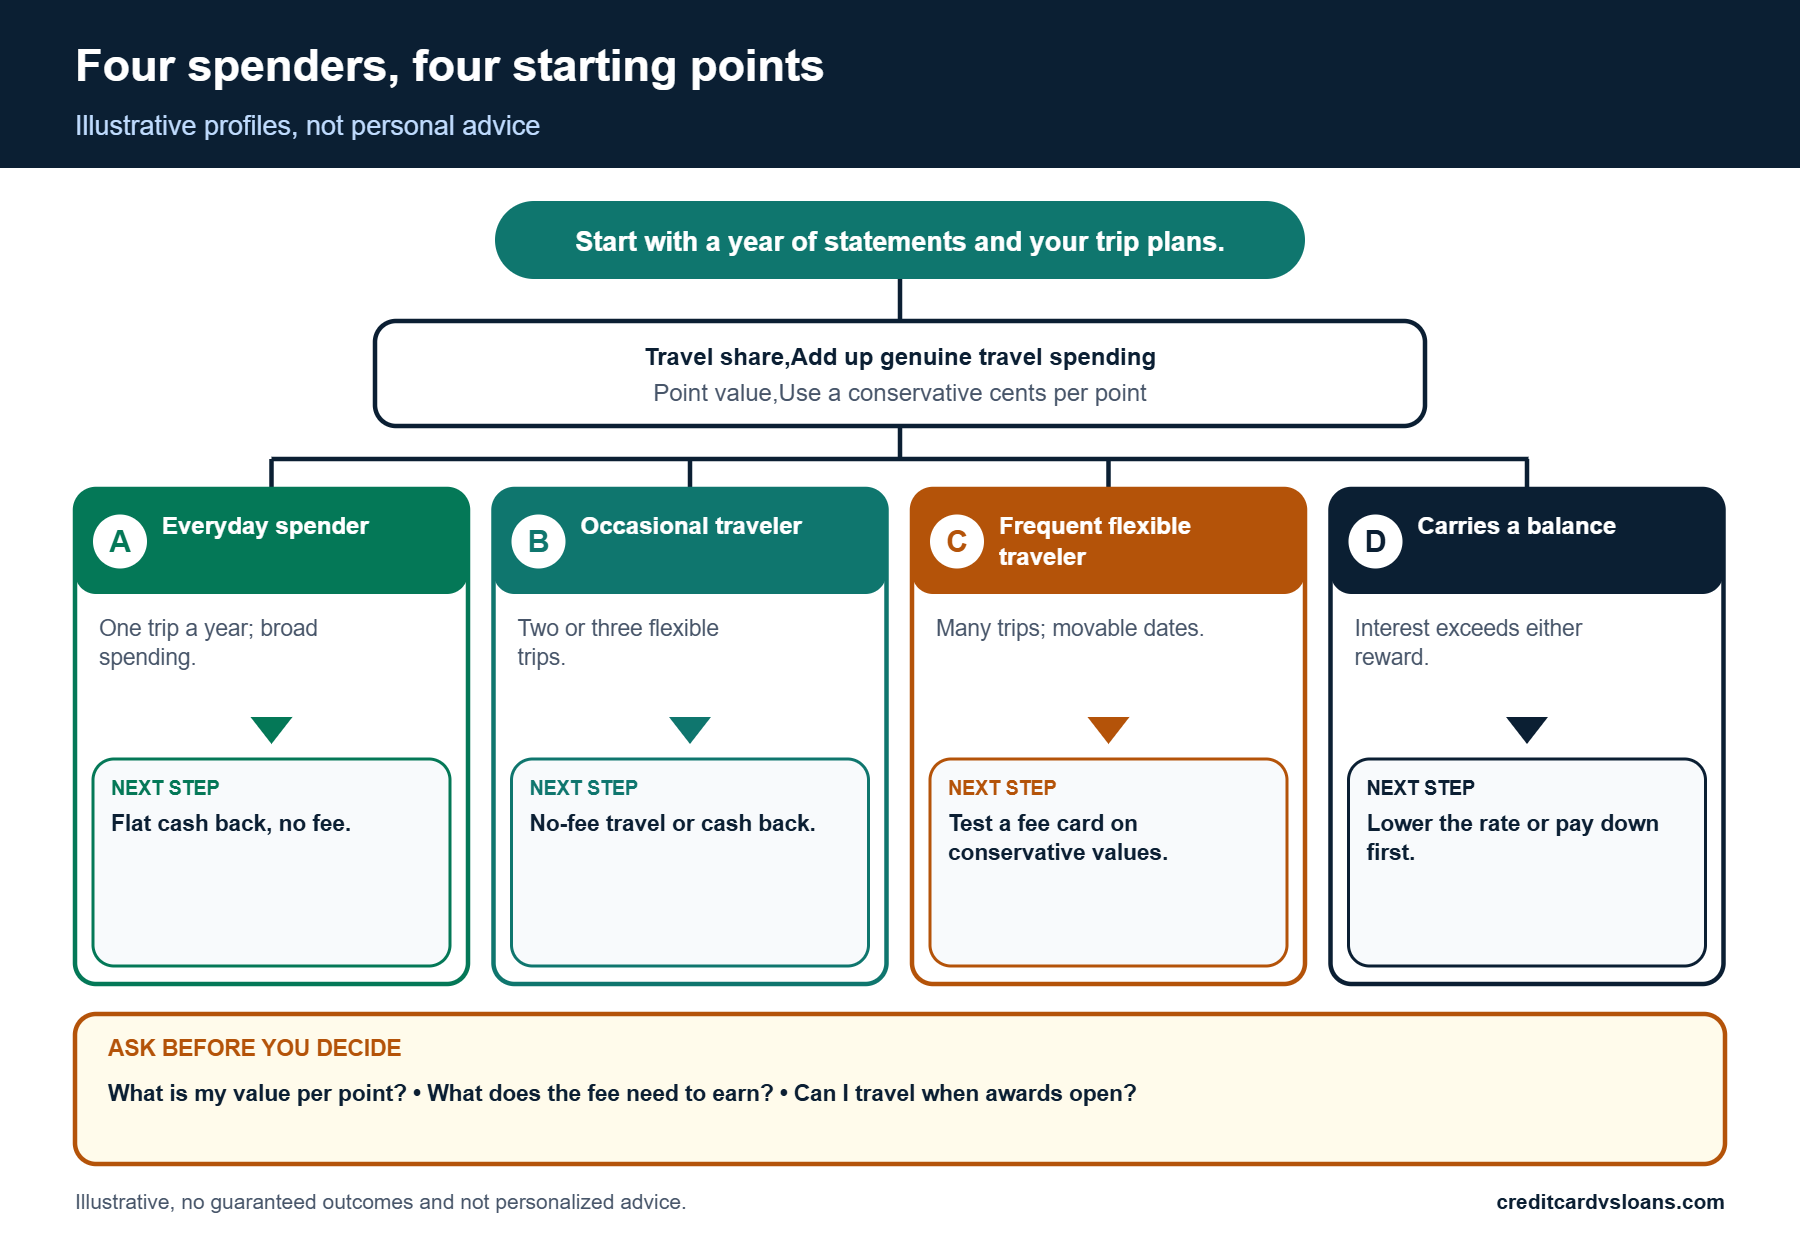
Profile one is a household whose spending is mostly groceries, bills, gas and online shopping, with a trip or two a year. For this profile, a flat cash back card is usually the baseline to beat, and a travel card would need to pay enough on everyday categories to cover a fee. The extra complexity rarely pays off.
Profile two travels a little more: perhaps two or three round trips a year, with flexible dates. A no-fee travel card or a cash back card that allows redemption toward travel can work, because the fee risk is low and the redemption is simple.
Frequent travelers and business spenders
Profile three travels often and has flexibility on dates and airlines. A travel rewards card with an annual fee can make sense here, provided the points are valued sensibly and the redemption options match the way trips are booked. Frequent travelers are also the group most likely to use partner transfers, which the CFPB spotlight says only a handful of large issuers offered at the time of its writing.
Profile four is a small business owner whose spending includes travel. The purchase can be business spending on a business card, which has different terms from a personal card. Our guides on business credit card versus business loan and 0% APR business credit cards explain how business card economics differ from personal card economics.
| Profile | Typical spending pattern | Reward that usually fits first | Why |
|---|---|---|---|
| Everyday spender | Mostly groceries, bills, gas; one trip a year | Flat cash back, no fee | Simplicity beats a fee that travel perks cannot cover |
| Occasional traveler | Two or three flexible trips a year | No-fee travel or cash back with travel redemption | Low fee risk, easy redemption |
| Frequent traveler | Many trips; flexible on dates and carriers | Travel rewards, fee only if the math works | Redemptions can beat cash value |
| Business traveler | Travel plus operating expenses | Business card terms first | Business cards have different terms and uses |
Choose travel rewards when travel is a large, flexible part of your spending and you are willing to do the work. Choose cash back when your spending is broad, you value simplicity and you want the reward to be worth the same on every day.
What travel rewards pay for, and what they assume about you
How travel rewards turn into trips
Points and miles with fixed and variable values
Travel cards pay in points or miles. According to the CFPB’s rewards spotlight, points can be redeemed as cash back, converted to miles through transfer partners, or used for travel, gift cards and merchandise, and major issuers typically value a point at about one cent. Miles are airline-branded credits redeemed at prices the airline sets. Because the redemption value is not fixed, two people with the same card can get very different value from the same points.
The CFPB spotlight also cited a 2015 Department of Transportation Inspector General review of two large airlines: 99 percent of round-trip flights had award seats, 63 percent had them at the lowest award level, but only 13 percent of holiday-week flights did. The data is dated, but the pattern is the point: the cheapest award is the hardest one to find when you most want to travel.
Portals, credits and transfer partners
Many travel cards offer three redemption routes. A travel portal lets you book through the issuer at a set points price. Statement credits against travel purchases offer a simple, near-fixed value. Transfers to airline or hotel partners can offer higher value for specific awards, but they require more research and are usually one-way, so a transfer made too early cannot be undone.
The CFPB spotlight noted that five issuers offered transfers to hotel and airline partners at the time of writing, and that smaller issuers rarely do. If transfer value is the reason you want a travel card, confirm that the partners you would use are available before you apply.
Perks, credits and fees that come with the card
Annual fees and the benefits meant to offset them
Many travel cards carry an annual fee and offset it with credits, lounge access, or insurance-style benefits. Those benefits only help if you would have bought the thing anyway. A $100 airline credit is worth $100 to someone who flies that airline regularly, and it is worth little to someone who has to buy something to use it.
Value the benefits that you will actually use at what you would otherwise have paid, and give the rest a value of zero. Then see whether the card still clears its fee.
Foreign transaction fees and the travel-card promise
Cards designed for travel often waive foreign transaction fees, which can be a real saving abroad because the fee is charged on each purchase processed outside the U.S. A card without that waiver can add a few percent to every dinner and taxi overseas. Check the fee line in the rates and fees table rather than assuming that a travel label means the waiver.
If you never travel abroad, this benefit is worth nothing to you, and the card should be judged on the rest of its terms.
Reading a sign-up offer before you chase it
The spending requirement and the window
A sign-up bonus is paid when you spend a set amount within a set number of months. Divide the requirement by the number of months to see the monthly spending the card is asking for, then compare that to what you already spend on the card. If the gap is large, the bonus is an invitation to spend more, and the bonus has to be weighed against the cost of that extra spending and any interest that follows.
Also check which purchases count. Some transactions, such as cash advances, balance transfers or certain payment-service purchases, may not count toward the requirement, and the bonus may be paid weeks after the window closes.
Timing the application
If you know a large purchase is coming, such as a flight you have already decided to buy or a planned repair, applying shortly before it can let the purchase count toward the requirement without distorting your budget. Applying and then looking for things to buy is the reverse of that, and it is the pattern the CFPB data on missed bonus requirements hints at.
Also leave room in your credit calendar. A hard pull and a new account are modest effects, but stacking several applications close together is not a good way to build a thin file.
The cost side: fees, interest and break-even math
Break-even: when a travel card beats cash back
The hypothetical setup
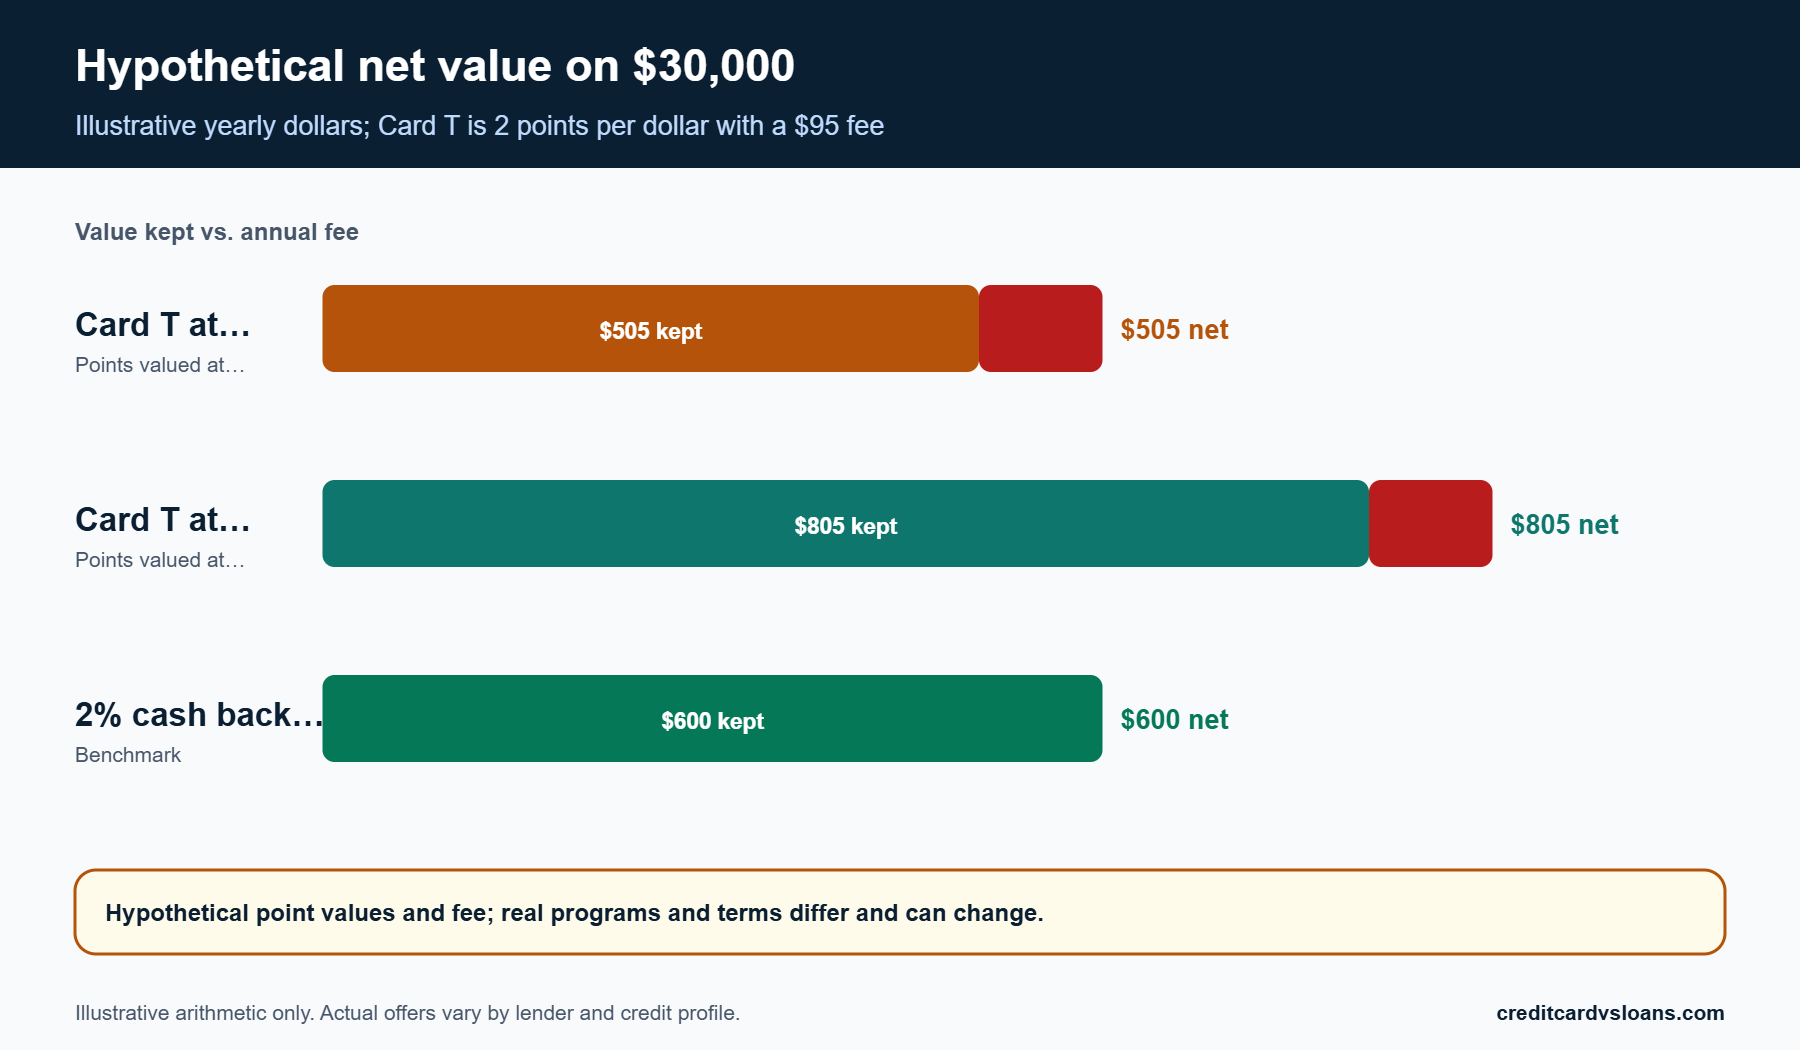
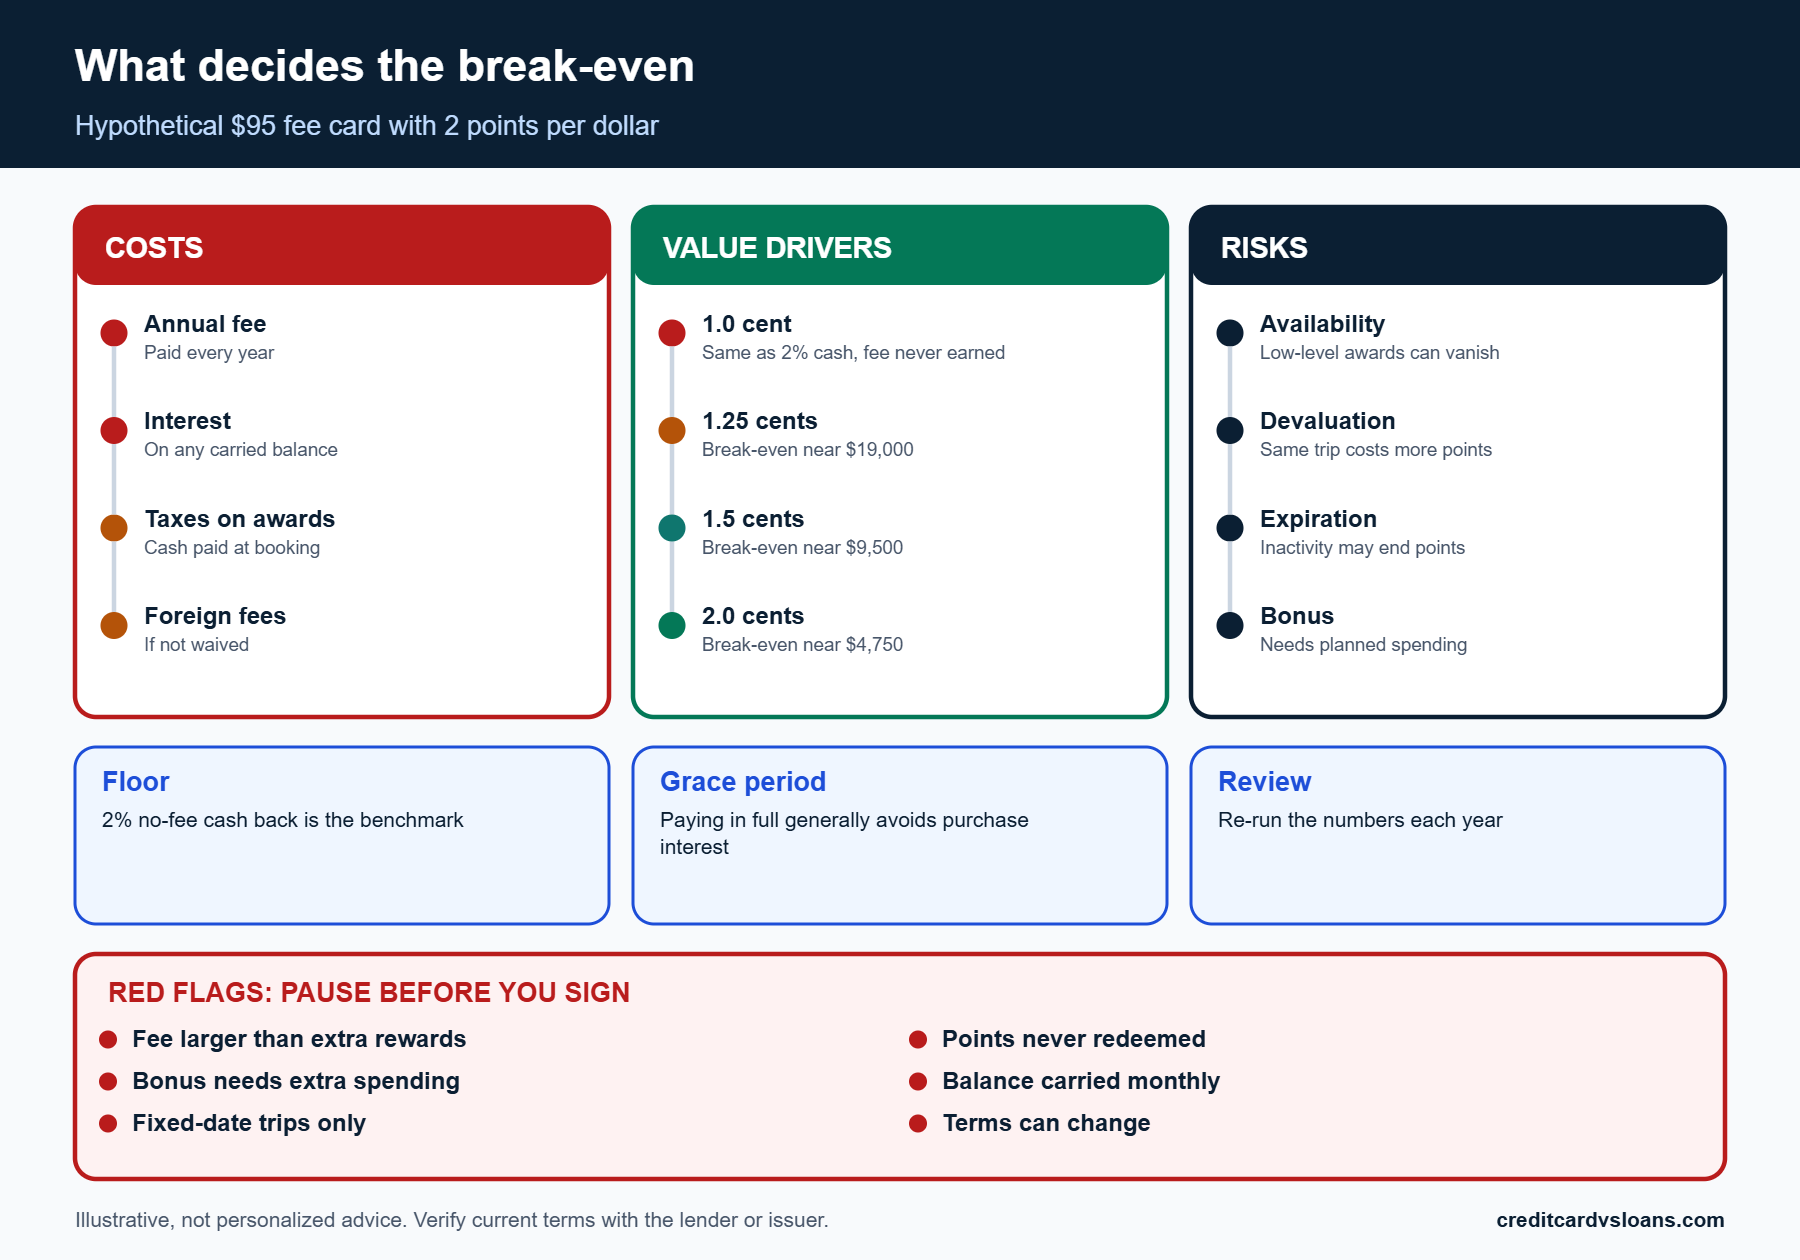
To see the trade, compare two hypothetical cards. Card T earns 2 points per dollar on all purchases with a $95 annual fee. Card C earns 2 percent cash back with no fee. The only unknown is what a point is worth to you. At 1 cent per point, Card T earns the same 2 percent as Card C but charges a fee, so it never wins. At 1.25 cents it earns an effective 2.5 percent, at 1.5 cents 3 percent, and at 2 cents 4 percent.
These point values are assumptions, not market data. The point of the exercise is to find the value your own redemptions would need to hit and then ask whether you will realistically get there.
What the numbers say
Against the 2 percent cash back card, the fee card breaks even at $19,000 of annual spending if a point is worth 1.25 cents, at $9,500 if it is worth 1.5 cents, and at $4,750 if it is worth 2 cents. At spending of $30,000 and points valued at 1.5 cents, Card T nets $805 after the fee versus $600 for Card C. At 1.0 cent it nets $505, which is $95 less than the cash card.
The lesson is that the value per point matters more than the number of points. If your realistic redemptions come out around one cent, the fee card is just a more expensive way to earn cash back.
| Annual spending | Card T at 1.0 cent per point | Card T at 1.25 cents | Card T at 1.5 cents | Card T at 2.0 cents | 2% cash back, no fee |
|---|---|---|---|---|---|
| $15,000 | $205 | $280 | $355 | $505 | $300 |
| $30,000 | $505 | $655 | $805 | $1,105 | $600 |
| $45,000 | $805 | $1,030 | $1,255 | $1,705 | $900 |
Annual fee decisions over time
The first-year bonus versus the steady state
A fee card often looks best in year one, when a sign-up bonus and a first-year fee waiver can both apply. The decision that matters is year two, when the bonus is gone and the fee is real. Judge the card on its steady-state numbers: the rewards you earn from ordinary spending, the benefits you use, and the fee you will pay every year after.
If the card only works with the bonus, treat it as a one-time offer and plan a move to a no-fee card before the second fee posts.
Asking for a downgrade or a retention offer
Before you cancel a card because of its fee, ask the issuer whether it offers a no-fee version or a retention offer. Terms vary and nothing is promised, but the question is free, and a downgrade preserves the account history. Redeem your points first, because the terms may treat unredeemed rewards differently after a change.
Get any change in writing or in a secure message so that you have a record of what was agreed.
Interest and fees can outweigh either reward
The rate on a balance
The Federal Reserve’s G.19 release of Sept. 8, 2026 reported an average credit card interest rate of 22.15 percent on accounts assessed interest for the second quarter of 2026, and 20.94 percent across all accounts. A simple annual estimate of interest on a $2,000 balance held all year at that rate is about $443. For comparison, 2 percent cash back on $20,000 of spending earns $400, and 2 points per dollar on the same spending (40,000 points) would be worth $400 at one cent per point or $800 at two cents. In this hypothetical, the interest on the balance cancels all of the cash back and more than half of an optimistic points valuation.
The CFPB’s grace period guidance explains the dividing line: pay the full balance by the due date and you generally are not charged interest on purchases; carry a balance and new purchases accrue interest from the day they post.
Late fees and other costs
Late fees, returned-payment fees and cash advance fees earn nothing and can cost more than a month’s rewards. Cash advances typically accrue interest from the transaction date. Most travel and cash back programs exclude these transactions from earning, so a cash advance costs you twice.
Set autopay for the full statement balance, or at least the minimum, and keep a reminder for the due date. For people who sometimes carry a balance, the cheaper path is described in our guide to 0% balance transfer cards.
When cash back is the better fit
The case for simplicity
A reward that is worth the same every day
Cash back does not need a conversion chart. One cent earned is one cent you can spend, and it cannot be undermined by a change in an airline’s award pricing. For anyone who values predictability, that is a feature that is worth some foregone upside. It also means the comparison between two cash back cards is a matter of arithmetic, not of research.
The CFPB spotlight reports that average rewards value in major issuers’ general purpose cards was 1.6 cents per dollar spent in 2022. A flat cash back rate in that neighborhood is close to the national average value, which suggests that a simple card is competitive for many households.
Fewer ways to lose value
Points and miles can lose value through program changes, award availability, expiration or forfeiture. The CFPB spotlight reported that each quarter about 4 percent of accountholders lose access to at least some of their rewards, and that issuers forfeit, expire or revoke hundreds of millions of dollars of earned rewards each year, based on 2023 report data. Cash back is exposed to some of those risks, such as closure, but it is exposed to fewer.
The CFPB’s Circular 2024-07 also warns that devaluing rewards a consumer has already earned can be unfair or deceptive, which is a signal that the problem is real enough to draw regulatory attention.
Hybrid options that sit between the two
Cash back that can be used for travel
Some programs let you redeem cash back toward travel purchases at a fixed rate, which gives you the simplicity of cash with the option to book a trip. This works well for occasional travelers who do not want to manage a points balance. The trade-off is that you do not get the upside of high-value transfers.
Because the redemption value is fixed, you can compare these cards to a flat cash back card in a single step. If the rate is the same, the choice depends on the terms, not on a points valuation.
Keeping both kinds of card
Some households hold one cash back card for everyday spending and a travel card for trips. That can work if you pay both in full every month, track the due dates and the annual fee on the travel card is justified by the travel spending. The risk is that two cards double the chances of a missed payment or an unused fee.
If you are tempted to hold both, run the break-even test on the travel card alone, using only the spending you would put on it.
| Dimension | Travel rewards | Cash back |
|---|---|---|
| Value per unit | Varies by redemption, route and date | Fixed at one cent per cent earned |
| Typical annual fee | More likely to carry a fee | No-fee options are common |
| Effort required | Higher: research and timing | Low |
| Upside | Higher on well-priced awards | Capped at the stated rate |
| Exposure to program changes | Higher | Lower, though earn rates can change |
| Fits | Frequent, flexible travelers | Broad, everyday spending |
Keeping the choice under review
When your travel pattern changes
A card that fit last year can stop fitting this year. A new job with less travel, a family that now travels at fixed dates, or a move closer to relatives can change both how much you travel and how flexible you are. Revisit the break-even test whenever your travel plans change materially, and not only when the annual fee posts.
It is easier to change cards early in the relationship than to remember a fee after it has been charged. Many issuers offer a way to move to a no-fee card in the same family, which keeps the account and its history open.
A yearly rewards review
Once a year, add up what the card earned, what you redeemed, what you paid in fees and interest, and compare the net to your benchmark flat card. If the card did not clear the benchmark, change something: your redemptions, your category usage, or the card itself.
That small ritual keeps the card a tool you chose rather than a default you drifted into.
Credit score impact and who qualifies
What a new card does to your credit
The same mechanics for both kinds of card
A travel card and a cash back card affect your credit in the same ways. An application usually triggers a hard pull, a new account changes the average age of your accounts, and the balance you report affects utilization. Rewards themselves are not reported to the credit bureaus and do not change scoring.
Prequalification, where offered, generally uses a soft pull that does not affect your score, although it is not a promise of approval. Use it to compare offers before you decide on a full application.
Annual fees and keeping the account open
If you decide a travel card no longer fits, think before you close it. Closing an account can reduce your total available credit and can end an old account’s contribution to your average account age over time. Ask the issuer about a no-fee version of the card, which may preserve the account without the cost.
Redeem or transfer any points before you close or downgrade the account, because the terms may say unredeemed rewards are forfeited.
Qualifying for a travel or cash back card
Credit profile and income
Cards with annual fees and richer travel benefits are generally marketed to applicants with established credit histories, while no-fee cash back cards and starter cards are available more broadly. There is no single published threshold, and issuers consider income and existing debt as well as scores.
If your credit history is short, a plain starter card used lightly and paid in full may be the sensible first step. Our guide to how rewards credit cards work explains why complexity is not the same as value.
What to do if you are declined
A decline usually comes with a notice explaining the main reasons. Check your credit reports for errors, reduce revolving balances if utilization is high and give the account history time to age. Reapplying right away tends to add hard pulls without changing the reasons.
In the meantime, consider a card with a lower fee or none, and reconsider travel rewards when your profile has improved.
Big trips and your reported balance
How a large booking affects utilization
A single airfare or hotel booking can be a large share of your credit limit. If the statement closes before you pay, that balance can be reported to the bureaus and raise your utilization for the month, even if you pay it in full a few days later. Making a payment before the statement date is one way to lower the reported figure, and it does not change what you owe.
Utilization is not a permanent mark; it reflects the balance reported in a given period. Still, if you are about to apply for a mortgage or an auto loan, it is worth keeping balances low in the months before.
Planning payments around travel season
Travel spending is lumpy. Holidays, summer vacations and family events can all land in a few months of the year. Build a small cash buffer before the heavy months so that the bills are paid in full, and avoid financing a trip on the card because the reward looks attractive.
If a trip has to be financed, compare the cost of a card balance at roughly 22 percent, the Federal Reserve’s second-quarter 2026 average for accounts assessed interest, with other options before you decide.
A sign-up bonus is the biggest single number on a travel card and often the least repeatable. The CFPB spotlight reported that about one in four consumers eligible for a promotional bonus failed to meet its requirements in 2022. Count a bonus only if you would hit the spending target without changing your habits.
Risks that matter more with travel rewards
Redemption risk: the trip you want may not be available
Award space and blackout dates
A points balance is a claim on a program’s willingness to sell you something at a price. Airlines and hotels control that price and the number of seats or rooms offered at it. Holiday weeks, summer weekends and popular routes are the hardest to book at low award levels, which is the pattern in the Department of Transportation review the CFPB cited.
Plan on flexibility. If your trips are tied to fixed dates, such as school breaks or a family event, assume that award prices will be higher and recompute the value of your points on that assumption.
Taxes, fees and surcharges on award bookings
Even an award ticket may involve taxes, airport fees or carrier-imposed charges that you pay in cash, and those can be a material part of the cost on some itineraries. The value of an award is the cash price you avoid, minus those out-of-pocket charges, divided by the points you spend.
Hypothetical example: a $350 flight bought with 30,000 points and $5.60 in taxes saves $344.40, which values each point at about 1.15 cents. A $220 flight bought with 25,000 points and the same taxes values each point at about 0.86 cents, which is less than the one cent a cash back redemption would have paid. The same card can produce good and poor redemptions in the same year.
Program risk: rules can change
Devaluation and expiration
The CFPB’s Circular 2024-07, published Dec. 18, 2024, says that reducing the value of rewards already earned, or revoking them on vague grounds, can be unfair or deceptive. The circular is a statement of how the agency reads existing law and does not create new rights, but it signals the practices that worry regulators.
For you, the practical lesson is to avoid stockpiling. Points held for years are exposed to program changes and expiration rules, and the CFPB spotlight said most issuers with rewards have expiration policies, usually tied to inactivity. A plan that redeems within a year or two limits that exposure.
When trips change
Cancelled trips can involve fees to redeposit points or may leave you with an airline credit that expires. Read the cancellation and change rules for awards before you book, and consider whether a refundable cash fare is worth the price when plans are uncertain.
For card charges that go wrong, the FTC explains that you can dispute billing errors in writing within 60 days of the first statement that shows the error. That protection applies to the charge, not to the points you hoped to earn.
| Risk | What it looks like | Question to ask before you commit |
|---|---|---|
| Award availability | No seats at the low award level on your dates | Can I travel when award space is likely? |
| Surcharges | Cash taxes and fees reduce the savings | What do I pay out of pocket per booking? |
| Devaluation | Same trip costs more points later | Will I use the points soon enough? |
| Expiration | Inactivity ends the balance | What counts as activity? |
| Fee creep | Annual fee renews while benefits go unused | Will I use the benefits that justify the fee? |
Alternatives, business spending and hybrid setups
If the real issue is a balance, not the reward
Lower-rate and promotional-rate cards
If you often carry a balance, a lower-rate card or a promotional rate on transfers may beat any reward. The key is a plan to pay the balance before the promotional period ends, and a close read of fees and the rate that applies afterward. Our guide to 0% balance transfer cards covers the details.
Choosing a reward card first and fixing the balance later puts the rebate ahead of the cost, which usually gets the order backward.
Consolidation and other routes
Fixed-rate installment loans, debt management plans and structured repayment can also lower the cost of existing card debt. The choice depends on the rate you can get and your discipline. Rewards should not be the reason to keep or add card debt.
When the balance is large relative to income, speak to a nonprofit credit counselor, and be careful with anyone who promises results before reviewing your situation.
Business owners: a different set of terms
Business cards versus personal cards
If you spend on travel for a business, a business credit card can separate expenses and provide different rewards structures, although the terms and consumer protections differ from those of personal cards. Our comparison of a business credit card versus a business loan explains how cash flow and cost compare in a business setting.
Keep personal and business spending apart where you can, and ask a tax professional about how rewards are treated, since the answer depends on how they were earned.
Introductory offers for businesses
Some business cards advertise a 0% introductory APR. The same logic applies as for personal cards: the offer is useful if the balance will be repaid in the promotional window and risky if it becomes a rolling balance. Our guide to 0% APR business credit cards weighs the benefits and the cash-flow traps.
A rewards rate is secondary when the main job of the card is short-term financing.
Keeping rewards from driving your spending
Set a budget first, then the rewards
Decide what you will spend on travel and everyday needs before you decide which card to use. The rewards should follow the budget; they should not enlarge it. A useful test is to ask whether you would buy the same thing at the same price with a debit card. If not, the reward is nudging you.
Treat the reward as a rebate on money already allocated, and keep the card paid in full so that you are not borrowing to earn it.
Redeem with a purpose
Points that are redeemed for a specific goal tend to get used well. Write the goal down, whether it is a flight home, a hotel night or a statement credit to reduce a bill, and compute the cents per point of the redemption. If the number is lower than your cash back alternative, choose the cash.
A rewards balance that has no goal tends to sit unused and exposed to expiration or devaluation. Redeeming on a schedule is dull, and it works.
A decision checklist for choosing between travel rewards and cash back
Run the numbers once
The three-line check
Line one: your annual card spending and the share that is travel. Line two: the realistic value per point from your own redemptions, which you can estimate from two or three trips you actually took or plan to take. Line three: the annual fee and the benefits you will really use. Put those into the break-even comparison against a flat cash back floor.
If the travel card wins only under optimistic point values, treat that as a no. If it wins under conservative ones, it is a candidate worth reading the terms on.
Pressure-test the result
Ask three questions. What happens if I travel half as much next year? What if my usual airline or hotel changes its award prices? What if I carry a balance for two months? A choice that survives all three is more robust than one that works only in the best case.
Write down the answers so that you can revisit them when the annual fee posts.
Next steps
If you lean travel rewards
- List the trips you expect in the next twelve months and how flexible the dates are.
- Estimate your value per point from real award searches and use a conservative figure.
- Confirm whether the card waives foreign transaction fees if you travel abroad.
- Check the expiration, transfer and change terms before you apply.
- Plan to redeem within a year or two and to pay the full balance every month.
If you lean cash back
- Pick a flat-rate, no-fee card as your floor and compare any alternative to it.
- Read the payout method, minimum and expiration terms.
- Use autopay for the full statement balance.
- Review your spending and the card’s rate once a year.
Travel rewards are a specialist tool: they can return more, but only for people who travel enough, book flexibly and redeem carefully. For everyone else, a no-fee cash back card is a sturdy default, and avoiding interest matters far more than which reward you choose.
- Cash Back Credit Cards: How to Compare Real Value
- Rewards Credit Cards: How Points, Miles and Cash Back Really Work
- 0% Balance Transfer Credit Cards: How to Use Them Without a Debt Trap
- 0% APR Business Credit Cards: Useful Tool or Cash-Flow Trap?
- Business Credit Card vs. Business Loan: Which Fits Your Cash Flow?
- CFPB: Credit card rewards: Issue spotlight (May 2024)
- CFPB: Consumer Financial Protection Circular 2024-07: Design, marketing, and administration of credit card rewards programs
- CFPB: What is a grace period?
- Federal Reserve: Consumer Credit – G.19 (release of Sept. 8, 2026)
- FTC: Using credit cards and disputing charges
Last updated: October 22, 2026. Rates, fees and lender rules change; verify current terms before acting.
The information on creditcardvsloans.com is provided for general educational and informational purposes only. It is not financial, legal, tax, credit, accounting or investment advice, and reading it does not create an advisor-client, fiduciary or any other professional relationship. Nothing here is an offer, solicitation or recommendation to borrow, lend or apply for any product.
Credit scores, interest rates, fees, eligibility rules, lender policies and laws change frequently and vary by lender, location and individual circumstances. Examples, figures and scenarios are illustrative only, do not predict your results and do not guarantee approval, savings, a particular rate or a credit-score outcome. Always confirm current terms directly with the lender or issuer and read the full agreement before you apply or sign.
Although we aim for accuracy and use reputable sources, we make no representations or warranties, express or implied, about the completeness, accuracy, reliability or timeliness of the content. Content may be drafted with the assistance of automated tools, so errors or omissions may still occur. Links to third-party sites are provided for convenience; we don’t control and aren’t responsible for their content.
To the fullest extent permitted by law, creditcardvsloans.com and its owners, editors, authors, contributors and affiliates disclaim all liability for any loss, damage or expense arising directly or indirectly from your use of, or reliance on, this content. Before making financial decisions, consult a licensed professional, such as a qualified financial advisor, attorney, tax professional or nonprofit credit counselor, who can consider your complete situation.